Shell - A beat on earnings, cash flow and increased buyback bodes well for the near future
Analyst’s view:
Today's results are strong with positive surprises on earnings, cash flow and the scale of the ongoing buyback. In light of this, we should view the company positively. However, I think commodity plays should always come with an element of caution. After all, the commodity gods can often take away what they have only recently given. For that reason, I take a slightly more restrained AMBER/GREEN stance.
Up 3% to 4072p (£226bn) - Q3 Results
When I previewed these results, I said that the moving parts here were largely known. However, the adjusted earnings figure still makes for pleasant reading. At $10.81bn, quarterly earnings came in nearly double a year earlier and the highest since 2022. More importantly, this figure was almost 5% ahead of the $10.33bn analyst consensus from the company-compiled number. That’s also 10% up from the $9.84bn delivered in Q2.
As expected, Refining was the big driver. Chemicals & Products adjusted earnings rose to $3.86bn, a huge increase from the $550m reported year earlier. The Products business contributed almost all of that profit, coming in at $3.75bn. Chemicals stayed weak, although consistent with the lower chemicals margin guided.
The Integrated Gas business was another highlight, where earnings rose 42% on higher gas and LNG prices, to $3.04bn. Trading and Optimisation was flat versus Q2.
However, Upstream earnings were slightly lower quarter-on-quarter at $3.19bn. This was due to lower liquids prices and higher well write-offs. Write-offs were already flagged at roughly $300m, and the $309m number came in in line with these effects.
Cashflow:
Cash flow guidance going into this update featured a wide working capital range and emissions-certificate outflow risks.
However, because tax, working capital and derivatives all came in at the favourable end of their ranges, operating cash flow stayed at $21.0bn. Excluding working capital, it was $21.7bn, and organic free cash flow was $17.0bn.
Although the guided $2.5bn outflow from the timing of German BEHG (fuel emissions trading) certificate payments came in pretty close at $2.2bn net, at the group level, this was more than absorbed by the positive derivatives inflow.
Net debt fell to $39.7bn and gearing to 16.6%. Excluding leases, gearing is only 2.7%, remarkably low for a company of this scale.
Buyback:
In my preview, I said investors would be looking closely at shareholder returns for signals about the company's confidence in the future. The open question was the size of the next tranche, after a $3bn programme (plus the leftover $1.2bn) last time. Shell announced $5 billion of buybacks for the next three months, in a period where analysts were framing holding the $3bn as acceptable. The higher rate of quarterly buybacks is a clear positive signal.
Against Shell’s own payout framework, the buyback is less generous than it looks. Shell’s stated policy is to distribute 40% to 50% of CFFO, making the recent returns below the bottom of the range. However, Shell applies the policy through the cycle rather than quarter by quarter. This means Shell may expect the current CFFO rate to be a temporary positive, rather than the new normal. Still, it means the $5bn is genuinely paid from operating cash flow, not increasing net debt.
Q4 Outlook:
The company provides a summary of what we can expect from Q4:
Integrated Gas production rises to 1,080–1,180 kboe/d with a full quarter of ARC.
Upstream production is guided at 1,700–1,900 kboe/d, with an allowance for Gulf of America [sic] weather.
Full-year capex is now $23–25bn, down from $24-26bn in a move the company describes as disciplined spending.
We haven't looked at Shell on the DSMR for over a year, and since then, world events have overtaken the oil price environment. It is clear that these events have had a far bigger impact on the finances of Shell than any management execution:
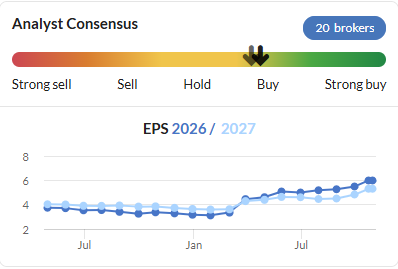
Refining margins, in particular, have been a massive tailwind for the company.
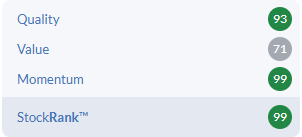
The net result is that the company has significant momentum behind it, while it remains modestly valued on current earnings forecasts:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Shell (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?