SIF Folio: Beximco Pharmaceuticals - a buying opportunity?

It’s been seven weeks since I added a stock to the SIF folio. In that time, all I seem to have done is sell shares. After last week’s disposal of Wynnstay, SIF is now 38% in cash and has just 12 holdings.
This lack of buying is not due to any market-timing efforts on my part. What’s happened is that my buying screen has been unable to find suitable stocks to add to the portfolio. For many weeks, the screen has returned only a few stocks. Usually, they’ve been existing holdings or otherwise unsuitable..
This remains true. My screen is returning just four results at the time of writing. However, one of these is a company that appears to tick all the boxes and would give SIF some useful exposure to the healthcare market.
Beximco Pharmaceuticals: an unusual UK share
Beximco Pharmaceuticals (LON:BXP) is a Bangladeshi company which makes generic medicines and active pharmaceutical ingredients. It was founded in 1976 as an importer and distributor of medicines from western pharma firms. The group has since become a manufacturer in its own right and now exports widely, including to western markets. Beximco is listed on the Dhaka Stock Exchange but has had a dual listing in London since 2005.
This is not the first time I’ve looked at this business on these pages. I held Beximco in SIF in 2016/17, exiting the position in May 2017 with a 70% gain.
I’ve kept an eye on this business since then and have been impressed by its continued growth and stable profitability. According to Stockopedia data, sales and profits have both grown by a compound average of 18% per year since 2015. Operating margins have averaged 22% over this period.
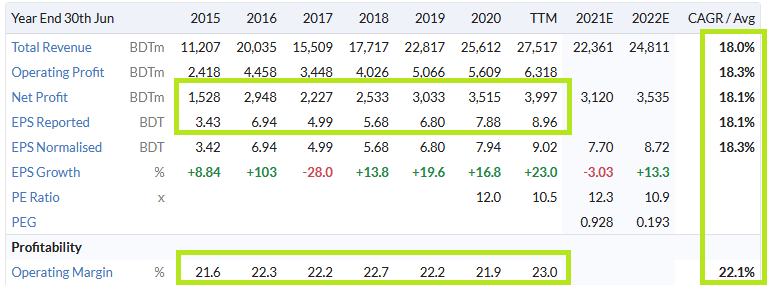
With a UK market cap of £364m, Beximco isn’t particularly large. But one reason for this is the shares’ unusual dual listing structure and dual valuation.
The company’s primary listing is on the Dhaka Stock Exchange, in Bangladesh. Beximco’s market cap on its home exchange is a rather racier £725m. How can this be?
This situation has arisen because Beximco’s UK-listed GDRs (Global Depositary Receipt) and its Dhaka-listed shares are not fungible. What this means is that you cannot exchange a GDR for the underlying share.
This is somewhat unusual, but I don’t think there’s anything sinister about it. In some ways, I think it’s reassuring that investors in the company’s home market are willing to assign a more typical valuation of 24 times forecast earnings, while we’re able to buy them on a P/E of 12.
Should I add Beximco to SIF? The shares pass all of my screening tests, which is a good starting point. Stockopedia’s algorithms also seem to be impressed, awarding a StockRank of 84 and a Contrarian style to the stock.

The omens are good, but I’ll take a look at Beximco’s QVM factor scores before making a decision.
Value: No complaints
Beximco’s ValueRank of 73 does not suggest any serious concerns. Looking more closely, the valuation seems affordable to me for a business with 20%+ operating margins:

The TTM valuation snapshot on the StockReport provides a one-stop look at a stock’s valuation, but the ValueRank also uses some other metrics which I find useful:
Trailing P/E ratio: 12
Earnings yield (EBIT/EV): 12%
Dividend yield: 1.6%
These numbers all look reasonable to me. I think this stock could be attractively valued.
One slight negative, in my view, is the company’s semi-regular habit of paying stock dividends in addition to cash dividends. For example, last year, Beximco paid a stock dividend of 10 shares for every 100 shares held in addition to the cash dividend I’ve listed above.
The advantage of this choice was that it allowed for a larger proportion of free cash flow to be used to reduce net debt:

The disadvantage of stock dividends on this scale is that they dilute future earnings per share growth. I wonder if this might limit the potential of the shares to re-rate.
After the reduction seen over the last 18 months, Beximco’s debt levels appear manageable to me:
TTM net debt: BDT 8,543m - equivalent to 2.1 times trailing net profits
Quality: Improving?
Beximco’s QualityRank of 97 suggests that this is a profitable, cash-generative business. I think that’s true, at least based on recent performance:

However, the company does seem to have been investing heavily in recent years. Free cash flow was negative in 2015, 2017, 2018 and 2019. This was due to capital expenditure exceeding operating cash flow.
This isn’t necessarily a red flag for me, unless it’s accompanied by excessive debt or worsening performance. In this case, the extra investment appears to have led to renewed growth. As I mentioned earlier, net debt has also fallen to a more comfortable level over the last couple of years.
I hope that these numbers tell us that Beximco’s management is successfully investing for the future. But I should stress that in keeping with the quantitative nature of the SIF strategy, I haven’t researched all these cash flow movements in detail.
However, my view that Beximco’s fundamental performance is improving does appear to be supported by its impressive Piotroski F-Score - a perfect 9/9:

The Piotroski F-Score is heavily-weighted in the QualityRank. It’s said to be an especially useful predictive indicator for small caps. A score of 9/9 shows improving fundamental performance - click through to see a full breakdown of the measures used.
Overall, I feel comfortable with Beximco’s quality metrics.
Momentum: opportunity?
Beximco’s MomentumRank of 40 is by far its lowest factor score. The red down arrow next to the rank also tells us that this score has fallen over the last 30 days:

Turning to the chart, we can see that Beximco’s share price has performed strongly over the last 12 months but has weakened recently:

Fortunately, I don’t think the situation is quite as bad as this slump might suggest.
Earnings estimates: I’ve checked the RNS feed for the latest news from the company and found two items that seem relevant to recent price action:
Update on supply of Covid-19 vaccine (28/4): Beximco has a contract to import 30m Covid-19 vaccine doses from India to Bangladesh. This was expected to make “a material positive difference” to profits for the year to 30 June 2021.
However, vaccine exports from India are currently suspended. This means that the completion of this contract will be delayed. Profit for the final quarter of the current year is now likely to be lower than previously expected, although we’re not told the expected impact.
Q3 results (30/4): these nine-month numbers show sales up by14% to BDT 21,762m for the nine months to 31 March. After-tax profit for the period rose by 40.8% to BDT 3,695m.
At this level, after-tax profit is already higher than that reported for the 12 months previously. Managing Director Nazmul Hassan says the company is still confident of “a strong result for the full year”. To me, this suggests the final quarter should be profitable despite the vaccine delays.
I’d estimate full-year after-tax profit of at least BDT 4,000m. My sums suggest this would put the stock on around 11 times 2021 forecast earnings.
Price Momentum (technical): The sell-off seen since January has weakened some measure of price momentum. But the one-year relative strength metric I use in my screening remains high, showing the stock has outperformed the market over the last year. We can also see that volumes have increased over the last 10 days - a bullish sign:

Beximco isn’t the most liquid stock on the market. Broker coverage is not very good either. As a result, I think shareholders can expect some volatility from time-to-time. Such moves can also
provide buying opportunities. I think this may be one of them, given the company’s strong performance for the nine months to 31 March.
My decision
Beximco Pharmaceuticals’ strange dual listing structure and valuation disconnect make it an oddity. But the company has been listed on the London market for more than 15 years and developed a solid reputation.
Unlike with Alumasc recently, I don’t see any reason to override my screen results here. I’ll be adding Beximco Pharmaceuticals to SIF and to my personal holdings this week, after this article has been published.
As always, I’d welcome your views. What do you think of this unusual stock? Is the valuation as attractive as it appears to me?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

22 comments
The share Purchase Agreement signed for the acquisition of a majority stake in Sanofi Bangladesh Limited bodes well for Beximco Pharmaceuticals (LON:BXP) (I hold) - reported in todays RNS.
“…the Company has now entered into the share purchase agreement to acquire the majority stake in Sanofi Bangladesh Limited ("Sanofi Bangladesh") (the "Acquisition"). The proposed earnings accretive Acquisition is in line with Beximco Pharma's strategy to expand its capabilities and product offering into new specialty therapy areas while enabling the Company to consolidate its position as a leading pharmaceutical in Bangladesh by adding an established business with a reputation for high-quality products.”
I topped up today to average down my holding today...
Any thoughts on why Beximco Pharmaceuticals has been drifting downwards in recent weeks (I bought not so long ago at 88p)? Could this be an opportunity to buy in or add, I wonder....
Belated thanks Roland for a very thorough write-up and far more than I could accomplish in 3 mins for a stock slam!
I did see your comments on the fact that the shares are not fungible. For anyone with access to Research Tree, the broker for the company, SP Angel, put out a very detailed research note of 33 pages a while back. For those researching the company, despite it being a couple of years old now, it's still very helpful for company background. In the note, it did cover the fungibility of shares issue:
"The Company’s GDRs and the underlying shares are not fungible. As a result, it is not possible for these shares to be traded on the Bangladeshi stock exchanges. The Bangladesh Securities Exchange Commission gave its approval to the admission of GDRs onto AIM on the condition that the GDRs and the underlying shares cannot be traded on the Bangladeshi stock exchanges. The Company has approached the Bangladeshi SEC twice for fungibility, but their requests were rejected."
I take from this that there is little likelihood of this ever changing and the shares would only ever trade at par with those on the Dhaka market in the event of a takeover, which I personally rate as low.
Hi Roland,
I follow your SIF screen but have not found this stock listed, do you work outside of your SIF Screen when looking for stocks and if so why do you run the screen.
Best wishes
Melvyngd
The issue I see with this stock is that the spread between buying and selling price seems very high at 565bps.
I have held BXP on and off since 2015, both in ISA and in SIPP. Although as you say, the London listing is non fungible with Dhaka, I always check the discount to the Dhaka share price before buying or selling. This share was described recently as a “beauty” by Evil Knievil.
I've been quite fascinated by this company since I saw them pitched on the stock slam, it immediately got my attention as I work in the industry and I had not heard of them before.
Having looked into them a bit more I see why, it looks like (according to their 20/06/2020 FY report that only around 10% of their sales come from export markets, they have no presence in the UK and though they mention they are launching one or two products in the US, they don't seem to be getting any traction at the moment with purchasers.
It's also interesting that they have developed the world's first generic version of the drug Remdesivir (which has proved effective against Covid 19 in trials) which they have begun selling, and indeed donating to hospitals, however they will not export this product as it is still patented in most of their export markets.
The US market is quite traditionally hard to crack, not least due to some protectionist legislation and attitudes, I will watch them with interest because they seem keen to do it and potentially grow in other export markets too.
There are dozens of Indian manufacturers who have taken this path over the years and have performed very well and there could be space for a company with a different outlook not least because many western governments got a very big shock last year when the Indian government banned the export of 26 pharmaceutical ingredients and their finished dosages (including paracetamol). Story here: https://www.theguardian.com/wo...
This has damaged the reputation and view of the reliability of Indian pharma and lots of governments are looking at different options to secure medicine supply longer term, including our own.
I don't hold but I will watch with interest!
Hi Bullygig,
Thanks for your comments, very interesting to hear an industry perspective on this business.
Roland
I thought this 'unusual' stock was a good candidate for diversification, so added to my portfolio today. Agree that Beximco isn’t the most liquid stock on the market. In it's February news update, Beximo says that despite delivery of covid vaccine delivery from India being delayed, "the impact of importing and distributing the vaccine is still expected to have a material positive impact on the Company’s full year results."
recent fall down the investors taking capital gains for the year as this is not isaable?
If it’s not ISA-able, that explains why I can’t buy it
You can buy it in an ISA although that will depend on which platform you use, both HL and IG you can buy it.
check out April’s Stock Slam on piworld, Beximco was pitched there
Covid -19, or rather the Indian variant, bothers me. India seems to be honouring its contracted foreign exports of vaccine but there's no guarantee Bangladesh or any other country will receive theirs when there is a critical need for India's production of vaccine to be used domestically where the disease is raging. Covid-19 also provides for a handy smokescreen for drops in performance. I'll wait and see.
I have used interactive investor with no problems.Rumour on BBS is that Beximco may start to produce Covid vacine
Sadly, it's not coming up on Barclays SmartInvestor so I can't buy it. I'm guessing it's the dual listing. Who are you all using to buy it?
Both IG and Hargreaves Lansdown have £BEX listed to trade.
I've had this share for a few years now and consider your analysis very fair. I sold 1/2 my stake when the stock price hit £1 and I'm sort of regretting it. On analysis its hard to fault good sector, screens well and shows growth.. Not many stocks around like that. Because no ones heard of it its unlikely to price at anything less than a discount but who cares because you should be ok in the long term.
I think I'm back in buy mode here as well
Hi Roland.
Excellent write up on Beximco Pharmaceuticals (LON:BXP) . Slightly odd company, not least its segregated dual listing (although the much higher domestic valuation does give some comfort). I bought in a few years ago notwithstanding some concerns about jurisdiction/ currency risk but have been pleasantly surprised with its performance and the company is always timely and meticulous in its reporting. Not necessarily a “coffee can” stock but happy to tuck away a decent dividend stream and hopefully ride a capital gain through their steady growth. Also quite a unique and diversifying exposure in my portfolio.
Gus.
I thought the stock divvy a waste of time at the start ( I first bought in 2012, and had several "stock instead of cash" dividends in the earlier years)
But now my initial 100k purchase has grown to 161,812, and all are drawing the cash divvy, whilst now worth 6 times their purchase price. My only worry would be trying to sell in bulk at any reasonable price, if I chose to.
There are worse problems to have :)