SIF Folio: Vertu Motors could tick all the boxes

In last week’s SIF update I tweaked my screen to find new stocks and found that electricity utility Drax was a near-perfect match for the buying criteria I use in this rules-based portfolio.
This week I’ve tried a slightly different approach, stripping out my dividend requirements to find companies whose payouts were suspended last year but which otherwise pass all of my tests. I was hoping to find a company whose dividend is expected to resume this year in line with pre-pandemic levels, rather than being rebased -- or cut, as you and I might call it.
Car dealership group Vertu Motors (LON:VTU) ticked all of the boxes in my screen except for a dividend payout. Fortunately, management have already said they’re confident dividend payments will be resumed for the current (FY22) financial year. Broker forecasts suggest a payout of 1.6p per share this year, only marginally below the FY20 payout of 1.65p per share.
(Of course, these are only forecasts at this stage, but I feel it’s reasonable to compare them with similar forecasts for other companies which suggest material dividend cuts are likely when payouts resume.)
Vertu Motors (LON:VTU)
AIM-listed Vertu was founded by CEO Robert Forrester in 2006, to act as a consolidator of UK motor retail businesses. Its best-known brand is probably Bristol Street Motors, but Vertu also operates under a number of other brands. The company says it is now the fifth-largest motor retailer in the UK, with 149 outlets representing many of the major manufacturers.
The three executive directors all worked together at dealership group Reg Vardy until 2006, when that company was sold to listed operator Pendragon.
Vertu has a market cap of £163m and turnover of £3.1bn, pre-pandemic. Margins are low, as is the norm in this sector, but the group has a strong balance sheet and has historically been quite cash generative.
Stockopedia’s algorithms like the stock, awarding it a StockRank of 98 and Super Stock status.

I’ve taken a look at the numbers behind these factor scores to find out more. Should I add Vertu Motors to SIF?
Value: below net asset value
Car dealership groups usually trade on modest multiples of earnings, so I’d expect Vertu to score well for value. It does, with a ValueRank of 98.
The shares currently trade on less than 10x pre-pandemic earnings, with a historic dividend yield of 3.6%. (I’ve disregarded the 2020/21 pre-tax profit of £22.4m. This appears to have been entirely generated by government support measures totalling £36.5m, which the company does not intend to repay.)
Most other car dealers also look cheap relative to past earnings. But one thing that differentiates Vertu is its sizable freehold property estate. The latest accounts show a tangible net asset value of 50.2p per share. The share price is 45p at the time of writing, pricing the stock at a 10% discount to NTAV. That seems cheap to me, especially since the group ended last year with an adjusted net cash position of £1.4m.
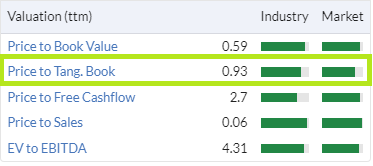
I think Vertu shares look genuinely cheap -- freehold property will normally find buyers even in distressed times. The current valuation suggests to me that the market is assigning a very low value to Vertu’s operating business. I’m not sure that such a pessimistic view is justified.
Quality: better than it looks?
Vertu’s QualityRank of 71 might seem counterintuitive for a business with an operating margin of 1.2% in a good year.
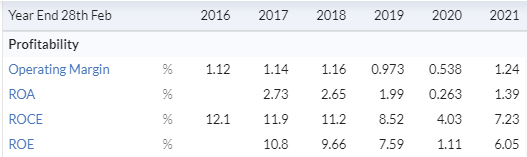
How can a business that appears to be only marginally profitable score well for quality?
I think there are a couple of points to make here.
Profitability is about returns as well as margins: Vertu’s operating margins are slim, but this isn’t the only way to judge profitability. A more meaningful measure, in my view, is to look at the returns on capital employed generated by the business.
Car dealers normally use a secured credit facility to fund their stock. This enables them to magnify the returns they earn on each car sold. Vertu’s six-year average ROCE is 9.2%, which is significantly better than its operating margin might suggest.
Aftersales work also makes a strong contribution to these returns, as profit margins are much higher on servicing and repairs. Vertu says that aftersales work generated a gross profit margin of 49% last year, compared to a gross margin of 4% on new vehicle sales. In the year before the pandemic, aftersales generated 43% of the group’s gross profit.
I think that the superior profitability and less cyclical nature of aftersales revenue supports the case for physical dealership networks. Although some car sales are shifting online, I reckon dealers with physical locations should still be able to add value versus online-only offerings.
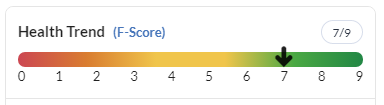
F-Score shows improving fundamentals: Profitability is one important element in quality scoring. But the F-Score measure of fundamental health is also heavily weighted in the QualityRank. The F-score measures trends for nine factors including margins, cash generation and leverage. Vertu scores quite well:
Free cash flow: I normally focus quite heavily on free cash flow, but I haven’t with Vertu. The reason for this is that the company’s cash movements last year were heavily distorted by circumstances.
Net cash from operating activities rose from £19.5m to £74.9m during the year to 28 February 2021. The main driver of this was a £29.6m reduction in working capital, which fell as reduced sales resulted in lower inventories and receivables. Business rates relief of £8.7m also resulted in additional cash being retained within the business. I’d expect that such cash flows would reverse and normalise this year, so I don’t intend to place much emphasis on last year’s bumper cash performance.
These factors may have boosted some of Vertu’s quality metrics, although I don’t think the overall impact on the QualityRank should be too significant.
Momentum: solid outlook
In my view, Vertu’s value and quality metrics do not flag up any serious concerns. I also think the current valuation offers good downside protection, thanks to the extensive property backing.
However, cheap small cap stocks will sometimes stay cheap for long periods, if they’re unable to demonstrate that they deserve a higher valuation.
This is where momentum becomes important. This factor has two primary components - earnings growth and technical momentum, which is driven by price action.
Vertu’s MomentumRank of 88 suggests the stock scores quite well in both regards, so let’s take a look.
Price momentum: Vertu’s shares have outperformed the market over the last year, resulting in strong relative strength scores. Volumes appear to have weakened over the last couple of weeks, but I’d expect this as the buying activity triggered by May’s results dies down. Small caps are less liquid than larger firms, but this isn’t necessarily significant.
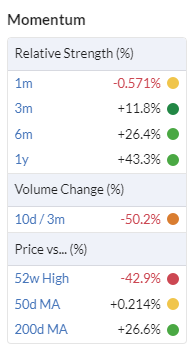
I’m pleased to see the shares are still trading above their 50-day and 200-day moving averages. Technically, this suggests the current uptrend may still be intact.
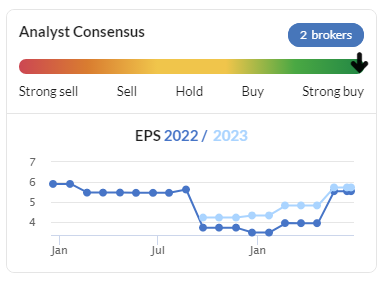
Earnings estimates: May’s full-year results triggered a round of earnings upgrades for Vertu. Note that FY23 growth is expected to be minimal, after a stronger recovery this year:

These have returned the earnings outlook to pre-pandemic levels:
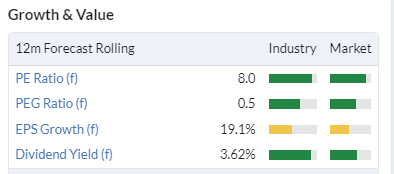
These forecasts price Vertu shares on eight times forecast earnings, with a dividend yield of 3.6%:
Share buybacks? The company has said that share buybacks may be used to soak up “excess FCF [free cash flow] at share prices below intrinsic value”. So if trading remains strong and the share price remains below its tangible net asset value, we may see some buyback activity later this year. This might help to support a higher share price.
On balance, I think Vertu’s momentum looks appealing. Demand for cars appears to be strong and broker forecasts suggest that the group’s profits could exceed pre-pandemic levels this year. Based on this outlook, the current valuation looks very affordable to me.
My decision
The outlook for UK car retailers isn’t without risk. A global shortage of semiconductors is threatening to limit supplies and distort the pricing of new and used cars. Broader inflation could also make a return after years of absence, putting pressure on household budgets.
Another concern for me is that we don’t yet know how the economy will behave when government support measures - especially furlough - finally come to an end.
However, my policy with SIF stock selections is to (mostly) avoid macro issues and focus on fundamentals. Vertu looks attractive to me on this basis.
I’ve decided to add Vertu Motors shares to the SIF folio and to my personal holdings this week. As always, I’ll make the trades after this piece has been published.
I’d be interested to hear your views on car dealerships and other consumer stocks. Is the good news already in the price, or can we expect to see a sustained period of strong performance as the pandemic eases?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

29 comments
Vertu Motors (LON:VTU) presentation on PI World next week will likely be worth a watch - can register here.
Quick update. I found pretty much the same situation at the Mercedes dealer. Quickly dwindling used car stock, and whilst you can order a new car, there's no guarantee as to when it will be delivered; very possibly not this year. Same situation as at Audi.
The good news is I managed to buy a new A220d AMG Line sitting in the port with a £6,800 discount due to it now being an old spec model. Pretty good deal and the Merc interior is spectacular quality compared to the A3 we drove.
FWLIW I ditched my Vertu Motors (LON:VTU) holding on Friday. Given what I found, there's a bit too much uncertainty on the sales front for H1 next year for my liking. It's clear to me any broker estimates of revenue for H2 and H1 2022 are pure guesswork.
All the best, Si
Quick update. I realise this is highly circumstantial but I returned to Audi yesterday for a test drive. As an aside, when I got in I was absolutely shocked at the amount of cheap plastic in a supposedly upmarket German car. Really shocking quality interior compared to our old Audi.
Yesterday, I tried to order a new car. Well, it turns out there are simply no production slots left for the model I wanted, and none for other models either. Of course, not all the available slots will be for cars heading to the UK... The salesman was pretty cheesed off, maybe he'd had a bad weekend, but I know how I'd feel turning up for work every day knowing full well I had virtually no cars to sell.
With regard to second hand cars, I was told they were now bidding on second hand stock from Audi UK and they were paying more than the list price of the car I had test driven for the same car spec and age. By the time they have put their own margin on top and stuck it on the lot, the price will not be far short of that of a new car. Who in their right mind is going to buy a second hand car that is less than 5% cheaper than a brand new one unless they are in some kind of blind panic to own a car? Not me!
I'm off to a Merc dealer tomorrow so will report back. Looks to me like the dealers will have a bumper end to this year but could be a famine start of next.
All the best, Si
Not just me then, we looked at Audis last month and was extremely disappointed with the plastics too. Having had awful experiences with Mercs in the past we went to the BMW showroom. Quality is infinitely better but delivery times were too far away and PCP prices seemed high. In the end purchased a 235 Grand Coupe from a leasing company on a 3 year lease with delivery just 25 days away. Price was 25% less per month than that quoted at our local dealer. Might be worth checking the leasing companies to see what they have available for immediate delivery?
Thanks, Graham. I'm going to sound old fashioned here, but we don't change cars that often and so PCP does not work for a number of reasons. We're only looking for a run about for the other half so A3 Audi or A200 Merc. After yesterday, assuming I can get one, the Merc will win hands down. How much more cheap plastic and poor quality other materials can you get into a cabin that size :)
All the best, Si
The car makers are all cutting costs because they have to develop electric cars alongside internal combustion. VW group are particularly bad due to dieselgate but I saw last week that BMW are also planning to cut production costs per vehicle by 25% by 2025 so I'm not sure how long their quality will last.
Cars seem to be going back to the bad old days of just lasting until the end of the warranty period. By the time people notice and resale values take a hit they will be pushing us to go electric.
Vertu Motors (LON:VTU) I believe the AGM is tomorrow so might get a trading update. I hold.
Vertu Motors (LON:VTU) decent update today. Albeit tempered by new vehicle delays and high Wholesale prices for used cars.
I like this bit though
"in light of the strong trading performance to date, driven largely by the exceptional used car market environment, the Board now anticipates that the Group's full year adjusted profit before tax will be above current expectations and in the range of GBP28m - GBP32m".
Roland, thanks very much for your analysis of this company and your explanation.
Maybe I’m a bit thick but when you said the following statement this it got me a bit confused (not too hard) isn’t that bad news if they don’t plan to pay it back.
“This appears to have been entirely generated by government support measures totalling £36.5m, which the company does not intend to repay.”
Also, interesting what you said about tangible assets and how you worked it out it’s something which I hadn’t really thought about before. How did you get to the figure of 50p per share? Is it something like (share price 45p) divided by (tangible assets O.93 = 48.37p ?
Cheers and thanks,
Martin
Hi martin,
I have to admit I used the company's own figure for tangible net assets per share, which I took from the FY21 results presentation.
To calculate this myself, I'd take the net assets (total assets - total liabilities) from the balance sheet and then subtract any goodwill and intangible assets. I'd then divide the remaining sum by the share count for Vertu Motors (LON:VTU), which is shown at the bottom of the StockReport.
I've just done this quickly and got a figure of 48.3p per share, so slightly below the company's own measure, but close enough.
In my view, balance sheet asset values are a useful guide, but aren't cast in stone -- they're a snapshot at a single point in time.
Regards,
Roland
I've held Vertu Motors (LON:VTU) on a few occasions over the years and last bought a year ago at half the current share price. I also happen to be in the market for a new car and so visitied a local Audi dealership yesterday, and given what I found, I am seriously consider selling up. I suggest anyone that is thinking of buying into car dealerships do a bit of mystery shopping first.
Yesterday I experienced...
1. A computer screen showing all the incoming cars they were expecting with already ordered new cars not expected until end of the year.
2. Tales of whole model ranges they could not source at all, used or new e.g. Audi Q3.
3. If you're strange enough to want a new car with a sunroof? Not until 2022 at the earliest, sir!!
4. I witnessed used cars parked so far apart on the forecourt that it was obvious they had virtually no stock (unless I missed the government instruction that Audi Q2's should maintain a social distance of 4 metres!)
The salesman also told me last weekend he had two parties virtually fighting over one estate car just like they were buying loo roll at the start of a pandemic!
So all the news is incredibly positive currently with very strong trading in the the first half, as Marshall Motor Holdings (LON:MMH) has also reported this AM. However, the concerns about longer term trading expressed in the recent trading statements by listed dealers appear to be very real. It's a low margin business, so what happens when they don't have any cars to sell?
All the best, Si
I was listening to a US Motley Fool podcast last week that told a similar story. Large dealer lots that would normally have many hundreds of new and used cars on sale with barely a dozen cars left.
The more popular used cars are selling for more than they were going for two years ago.
It's interesting to see how this progresses. Used car prices increasing should push up the value of their inventory and improve margins. Although any new stock they get would cost them more. If there are delays in delivery of new cars I wonder if that means people will keep older cars for longer and therefore lead to an increase in high margin services/mots?
At least this is an industry specific issue and not a company specific one.
I have looked at their website and the amount of used cars has been fluctuating between the 7000's and the 8000's (currently 8011) which suggests they're making sales and getting more inventory.
They currently also have 2260 new cars available.
Now 7945 used cars in stock. Which suggests they've sold 66 so far today.
Compared to additions to stock? I believe the statistic is a net movement?
Right. The amount of cars showing now is 7821. So 190 less than this morning. My conclusion therefore is that they have sold at least 190 cars today as there could also have been some additions.
I also don't know if every used car gets listed on the website or if they try and sell through walk ins to the local dealer first. I imagine that would save on photography/listing costs.
Back up to 8051 cars now. So definitely constantly moving both ways.
Strong start to new financial year with trading profits at a record level in the two months to April 2021. Adjusted profit before tax in the two months of £19.2m compared to £14.8m in the same months in 2019
The Board expect the Group will deliver an adjusted profit before tax for the year ending 28 February 2022 in the range of £24.0m to £28.0m
Vertu Motors (LON:VTU) (I hold) Board is being very cautious on the outlook for Feb 2022. With £19.2m PBT in first 2 months, I expect them to be comfortably ahead of the expectation of £28m for the full year. Latest EU car sales number for May is at record high. - https://www.reuters.com/articl...
Good piece Roland - I also like (and hold) Vertu. I particularly like their strong online offer, competing with the likes of Cazoo (home delivery, 14-day money back guarantee) but valued at a fraction of the price. As you say the freehold property more than backs the current valuation. I like to get a handle on traffic stats and organic search footprint for businesses that sell online, and similarweb estimates Bristol St Motors gets nearly 900k monthly visits, growing considerably over the last 6 months, with a healthy portion of that being via organic search, refferals and direct (i.e. free traffic): https://www.similarweb.com/web... Their other brand sites, while not quite as impressive as this, still show healthy traffic and search stats.
I'm not particularly concerned about the chip shortage, they may be able to improve margins on 2nd hand vehicles as that unwinds. Obviously cyclical so inflation / unemployment increases, or general economic downgrades will hit the share price. It won't set our portfolios on fire, but I believe it's a good long term hold and may re-rate in time, if they continue to perform and resume divis.
Thanks for the excellent write up. I hold Vertu Motors (LON:VTU) and consider the U.K. auto retail/service sector in general as being good value at the moment.
One additional plus for me is that although CEO Robert Forrester and his senior management have a decent amount of skin in the game (Forrester himself holds about 2%), the shareholder list is nicely spread with a number of decent institutional names but no dominant holder(s). Schroder’s is the largest with about 6.5%. Contrast this to Cambria Automobiles (LON:CAMB) where the Chairman is in the process of arranging a low premium MBI/legging over private shareholders by running off with the upside just when the story was starting to get interesting. Never say never, but seems unlikely with Vertu Motors (LON:VTU) .
Gus.
I've held shares in Vertu Motors for a couple of years now only to see them decline. I had intended selling once they recovered (as early as last week). Given your report, I think I may hold on.
Good read Roland! This is my favorite share at the moment partly because of the semiconductor shortage. The USA is seeing new car buyers forced to move in to the used car market, where there was already a high demand, causing prices to rise. I'm hoping this trend is the same here in the UK and that Vertu can capitalise on it.
Thanks Roland for your usual excellent research paper , into a company I have long admired and held for over 3 years . it’s a share I will continue to keep for the foreseeable future and I am sure you will not regret adding it to your portfolio
Nice article, thanks Roland!
I also rate Vertu Motors (LON:VTU) (I hold) highly as a value share - cheap on earnings multiple, and copper-bottomed on a balance sheet basis with all that lovely freehold property.
Just one thing - I don't know what SIF Folio is! Maybe the articles could start with a brief summary of what SIF Folio is about, for anyone new to the concept?
Regards, Paul.
Paul - I think the magnifying glass is meant to be a clue - Stocks in Focus!
Is there anywhere to see the full portfolio and it's performance?
Hi Dicky,
I include a full snapshot of the portfolio and discuss recent performance in my monthly write ups.
The latest one (from May) is here:
https://www.stockopedia.com/co...
Hope this helps!
Regards,
Roland
Hi Paul,
Thanks for the feedback - good point about SIF (which stands for Stock In Focus).
I try to include periodic refreshers about the concept behind this rules-based portfolio but I haven't done one for a while. I'll include something next time.
In short, I use a set of screening rules to create a shortlist of stocks that are eligible for the portfolio. Here's the current screen:
https://www.stockopedia.com/sc...
I then choose which stocks to add to the portfolio, making sure that I'm comfortable with them and that they create a reasonably diversified portfolio (although this is subjective).
I use a second, more lax set of criteria to govern when I should sell stocks. You can see the latest monthly write-up (for May) here:
https://www.stockopedia.com/co...
Regards,
Roland