SIF Portfolio: Can Air Partner fly higher in 2017?

This week’s stock is a company I’ve never paid much attention to before. Aviation services group Air Partner has only recently crept over my £50m minimum market cap. But having done so it’s now qualified for my screen.
Should I add this small cap to the SIF Portfolio? My view on the airline industry is fairly cautious, but Air Partner seems to focus on niche areas where growth is continuing. The group is also diversifying through acquisitions.
What does Air Partner do?
If you’re not familiar with Air Partner, here’s a summary of the group’s activities:
- Commercial and private jet charter and leasing services
- Freight aircraft charter
- Aircraft remarketing services
- Travel agency services
- Training and consultancy
The company’s private jet clients are high-net worth individuals and organisations. Commercial jet customers include sports teams, the oil and gas industry and governments. For example, Air Partner won contracts to organise European flights for Leicester City and Manchester City during the first half of the year. Another specialty is government aid work, including emergency evacuation flights.
Where does the cash come from?
In terms of revenue and profit, the bulk of Air Partner’s income comes from its charter operations. During the first half of the current year, commercial, private and freight services generated an underlying operating profit of £3.8m.
These underlying figures must be stated before central costs, because the group’s underlying operating profit was only £3.0m during the same period. To give you an idea of the scale of the business, Air Partner generated revenue of £22.2m from transactions worth £112.9m during the first half.
Is Air Partner good value?
Let’s take a look at some of the numbers behind Air Partner’s outstanding StockRank of 99.
The group’s ValueRank of 81 is the lowest of its three QVM ranks, but doesn’t highlight any particular concerns, in my view:
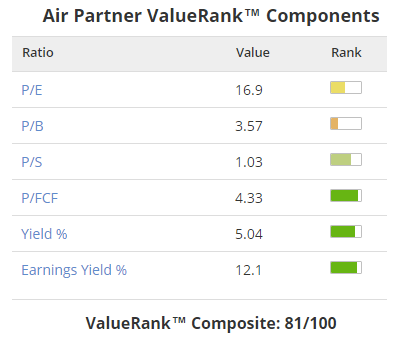
There are some clear attractions. The group’s 5% dividend yield and 12.1% earnings yield are very appealing. The price/free cash flow ratio of 4.3 is even better, but is so low I decided I should take a closer look.
The Stockopedia data suggest that Air Partner’s cash flow is quite lumpy. That’s not surprising for a business of this type where large one-off contracts can skew results, but it’s worth bearing in mind:
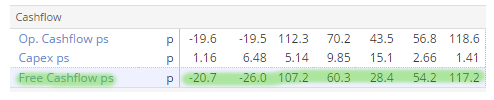
Looking at the actual accounts, acquisitions and working capital movements have both had a big impact on cash flow over the last couple of years. However, the Stockopedia figures figures appear to exclude acquisitions.
My calculations confirm the P/FCF of 4.3 excluding acquisitions, but Air Partner spent £5.9m on two acquisitions last year. When these are included, the P/FCF ratio rises to about 8.5. That’s still very attractive and covers the trailing dividend twice. I also think it’s a more prudent way to value the stock, given that regular acquisitions are part of the firm’s stated strategy.
Overall, I’m happy that while future cash flow may be lumpy, the group’s ability to generate cash is real. Air Partner’s 5% yield looks well supported and attractive, given the outlook for earnings growth.
Sky-high quality?
Air Partner is hoping to expand its private jet charter business by becoming a top player in the pre-pay private jet market. The group’s JetCard service allows would-be high flyers to pay up front for a certain amount of all-inclusive private jet travel.
JetCard cash deposits rose by 18% to £16.1m during the first half of the year, with card numbers up 9 to 218. That’s an average of £73,853 per card! It’s not a cheap way to travel, but it is much cheaper than owning or leasing a private jet. JetCard utilisation rose by 25% during the first half, and I can see the appeal of this service for high-net worth individuals and corporate customers.
I can also see the appeal of JetCard for Air Partner and its shareholders. This service generates significant upfront cash flows. At the end of last year, Air Partner had £16.8m of JetCard cash on its balance sheet. This is presumably one of the main reasons for the group’s high level of deferred income, which stood at £38.2m at the end of July.
High levels of deferred income can be a risk, as they often require significant expenditure to unwind. In this case I’m not too concerned. At the end of July, gross debt was £3.3m and the group’s cash balance stood at £24.6m. That’s enough to cover about two-thirds of deferred income.
However, it’s worth noting that when JetCard cash is excluded, the group’s net cash is just £5.2.m. That’s significantly lower than the £18.9m reported by Stockopedia, which isn’t able to separate the group’s two types of cash balance.
Moving away from the balance sheet, Air Partner’s other quality metrics look fairly sound. The stock has a QualityRank of 88 and scores highly in most areas:
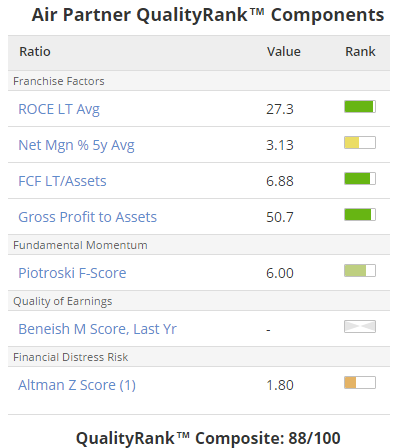
The Piotriski F-Score of 6 is the minimum allowed by my screen, but is still a decent score. These figures don’t seem to highlight any obvious problems, but one risk that is worth mentioning relates to profit margins.
Air Partner’s operating margin has risen strongly in recent years, and currently stands at a record level of 7.95%. However, Air Partner is a people business. Administrative costs accounted for 59% of revenue during the first half of the year. What this means is that a relatively small fall in revenue could trigger a big fall in profit margins.
In the event of a downturn, Air Partner might be able alleviate this risk by laying off staff, but the risk is worth bearing in mind. This probably isn’t a stock to own during a recession.
Jet-powered momentum
Broker forecasts for mainstream airlines have generally been cut this year, but forecasts for Air Partner have edged higher:
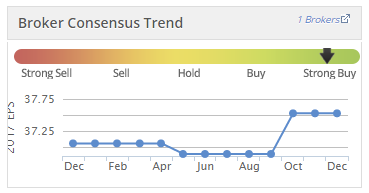
Underlying earnings per share are expected to rise by 43% to 37.5p this year, putting Air Partner on a forecast P/E of 13.2. EPS growth of 15% is expected next year, putting the stock on a forecast P/E of 11.4. This seems a fairly modest valuation for such strong earnings growth and a cash-backed 5% dividend yield.
Air Partner’s share price has risen by 18% so far in 2016 and is trading within 5% of its 52-week high. A strong set of results in January could help to drive further gains. With this hope and the stock’s high StockRank in mind, I’m going to add this stock to the SIF Portfolio this week.
I’ll be back next week to reveal which stocks will leave the portfolio in December. But in the meantime, I’d like to thank you all for reading this year, and wish you all the best for the festive season.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

3 comments
Thanks for insight, Roland. Not usually the sort of company I'd go for with such a narrow, and lumpy, profit margin but on this occasion I'm in, if only a small punt for now.
Rowland, nice article. You might be similarly interested in Gama Aviation (GMAA). This trades currently at 131p, on a P/E of only 5 on consensus forecasts of 26.7p EPS for the year about to end on 31/12/16 from WH Ireland and Cantor. They also pay a dividend, expected to be around 2.4p or so.
In addition, it has only a small exposure to the cyclical aircraft/jet charter markets, being more concentrated on aviation services/maintenance etc than Air Partner.
GMAA is one of the five largest aviation service operators globally, It also has a decent Balance Sheet.
The share price, which has always been illiquid, has been decimated imo by an extremely badly handled selldown by an investment fund, with stop-losses being triggered and confidence consequently decimated.
Even if forecasts come in say 20% below forecasts assuming the worst, then GMAA would still be good value.
GMAA achieved 15.8p adjusted EPS in H1 at current dollar exchange rates, so with a stronger H2 forecast in the outlook statement I'm hopeful of a recovery to more sensible levels of 200p+.
The share price has recently begun to recover, and there has been hardly any stock available to buy online, whilst one can sell quite a lot of stock. This hopefully indicates that the seller has - finally - finished, and any decent interest may translate into a bigger bounce.
We await a year end trading statement in Jan'17.
Rowland - Nice write up. I brought 2 lots of Air Partner (LON:AIR) earlier this week because they look to have potential. My buying notes below:
Too cheap for cash with EV/FCF of just 2.7. SR 99 and 97 QM. Close to 52 week high. Broker upgrade. Introduced a "Customer First" programme to improve customer experience, so important when dealing with high net worth clients. New safety acquisitions gives more visibility. Lord Lee holds and trusts CEO. 5% Divi. Sales likely to improve.
Lord Lee Interview: https://www.shareradio.co.uk/podcasts/my-portfolio...