Small Cap Report (10 May) - HGV, QPP, ASH, OCDO, KENZ, CTO

Pre 8 a.m. comments
Communications group Hasgrove (LON:HGV) looks an unusual situation. They seem to have sold off their largest subsidiary, and now have surplus cash of £12.5m as at 10 May 2013. They intend returning £10.25m of this cash to shareholders via a tender offer at 82p (the shares are currently 78p), and then De-List.
As the market cap is only £18m, this means shareholders should get over half their money out, but I don't suppose they'll be thrilled with the de-listing, and the shares are likely to fall today as a result. I believe companies should only ever de-List as a last resort, when there really are no other options. Otherwise they are breaking what I regard as an implied contract with shareholders - i.e. when we buy shares in a Listed company, we are doing so on the basis that we will in future always have the facility to trade those shares on the stock market. To remove that facility totally changes the situation. Most investors don't want to hold shares in private companies, and of course if you hold them via spread bets or CFDs then you are forced to close, as you cannot hold unlisted shares via those instruments.
The Quindell Portfolio (LON:QPP) saga continues with a clarification statement last night that raises as many questions as it answers. They have not provided a proper explanation of their derivatives contracts entered into, other than to play them down as not being material. But they do admit to engaging in an "equity swap" (whatever that is!) as part of a fund-raising last year. This appears to have involved guaranteeing the losses of a new investor, in order to get a Placing away.
This is clearly outrageous behaviour, and might even be illegal? You cannot secretly guarantee that a new investor cannot suffer any losses if the share price falls! Since to do so would be favouring one shareholder over others, something that is totally against at least the spirit of company law.
It just confirms my suspicions that this is a company with a really bad smell around it. Hence a total bargepole situation as far as I'm concerned. I would expect more nasties to come out of the woodwork here in due course.
Post 8 a.m. comments
I'm intrigued by the trading & strategy update from Ashley House (LON:ASH) this morning. I've not looked at this company before, as it's below my £10m usual market cap cut-off point, at £6.7m market cap last night (up 13% so far today). It seems to be involved in the problematic area of consultancy to the healthcare market.
Net debt has reduced sharply to £2.7m, and is expected to reduce further from settlement of legacy claims against PCTs. They are diversifying revenue into new areas, and refer to a, "much better outlook in the next couple of years".
Profit for the year ended 30 April 2013 is expected to be in line with market expectations, which seems to be for £1.69m pre-tax, or 2.88p EPS. So at the current 13p that means a PER of a very modest 4.5. Looks worthy of further research.
Do any members have a view on Capital Drilling (LON:CAPD) ? I had a little flutter on the shares a few months back, after they had issues with a major customer (Centamin, if my memory serves me correctly?) not being able to use their rigs due to problems with the Egyptian Government. Something like that anyway.
Capital Drilling shares bounced, but have slipped back again, and are down 10% today to 27p. Time is limited, so I'm just wondering if any of you have looked at them, and whether they are any good? I was talking to their PR company last week, who were raving about them - yes, I know that's what they are paid to do, but they could have mentioned any other of their clients, but specifically mentioned CAPD when I asked for their most interesting situation at the moment.
It's not a small cap, but I see the lunacy continues at Ocado (LON:OCDO), with the share price now up to 236p. So that's a £1.34bn valuation for a company that's never made a profit, and has spent a large amount on capex to distribute other people's groceries on a non-exclusive basis, on low margins. What a shockingly bad business model, and an absolutely bonkers valuation!
Goldman Sachs have put out a 300p price target and buy note apparently.
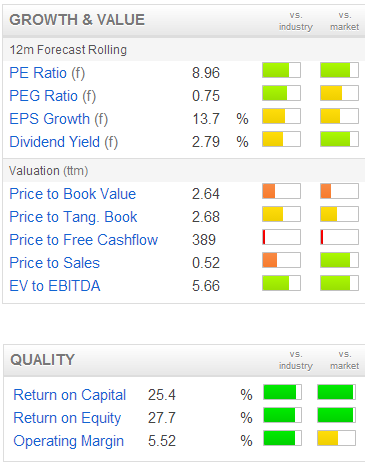
I'm thinking about doubling up my long position on Kentz (LON:KENZ). They put out a really good trading statement last week, the shares went up a bit, but have now come down and are lower than before.
The valuation looks really attractive to me there, given a smashing track record of growth in sales and earnings, especially considering the solid balance sheet too.
T Clarke (LON:CTO) have issued an in line with expectations trading update. The order book is up against last year, and they have a net cash position. The trouble with this business is that it's a wafer thin margin contractor. Although if you look back at the historic figures, the margins were better pre-crash. So I suppose the shares are mainly a bet on margins improving once the economy improves.
It also pays a reasonable dividend. Not really my type of thing, as I like businesses that make at least 5% (preferably more) operating profit margins. Below that, and you're just in a competitive area where customers will keep squeezing you until there's no margin left.
Finally, I was lucky enough to be able to attend the London Value Investor Conference yesterday. It's very much the Rolls-Royce of the investor conference circuit, with top-notch speakers, and an audience of mainly fund managers, staff from family investment offices, hedge funds, etc. Although I did spot a handful of friendly faces from the private investor community too.
For me it was the investor equivalent of a weekend at a spa retreat, I feel my value investing ethics have been suitably refreshed and recharged! I'll put together some thoughts about the most interesting speeches there over the weekend hopefully, and post it here.
That's it for this week! Have a super weekend, and I shall see you bright-eyed and bushy tailed (as I'm having a healthy weekend of no boozing, and lots of jogging & cycling!) on Monday morning.
Regards, Paul.
(of the companies mentioned today, Paul has a long position in KENZ, and no short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

29 comments
https://docs.google.com/spreadsheet/pub?key=0Aqs4doStlDDbdHhWemdTanJDaHNEZVAwU3VhRTd5YWc&single=true&gid=13&output=html
Take a look, welcome your comments
Paul
I know there is some mistrust in QPP but please bear with me, (Pardon the pun)
I have analysed QPP vs GWRE, Guidwire listed in NYSE
Either QPP is well undervalued ot Guidwire is very overvalued, give me you email address so I can send you the speadsheet.
.
Re CAPD. There was a Q1 IMS on May 17, 2012 so we can hope for a Q1 2013 IMS in about a week. My guess is that the share price has fallen too far. We should find out soon!
Just a word on T Clarke. They are below the radar of most investors, being very small cap and unfashionable. However their excellent management and expertise, plus rock solid financials, make them the John Lewis of electrical installations for major projects. They don't accept contracts without reasonable margins, and are seeing weaker competitors go to the wall. A fair bet for medium term recovery in my book, and good covered divi in the meantime.
Crusty
@Crusty, what do you think of T Clarke's pension situation? Not necessarily a show stopper but the deficit is sizeable and they're a bit unusual in having a live defined benefit scheme.
cig, the T Clarke annual report showed an increased pension scheme deficit of £11.9m, but in common with many companies this reflects the peculiarly low discount rates. IMO they have it under control with employer contributions circa £0.8m per annum, and with any half-decent recovery it will fade in significance. The benefits of the scheme, in the shape of well motivated, loyal and skilled staff, probably contrasts with much of the construction industry these days.
Last years' results are at: http://moneyextra.uk-wire.com/Article.aspx?id=201303190700262876A and make interesting reading.
@Crusty, I like that they're treating their employees well and the benefits are not exuberantly generous (half of career average for a notional 40 years there if I got it right) but it makes valuing a company hard (and that's true of every company with open ended pension commitments), because the actuarial valuations are close to useless (that 11m could turn into a 50m deficit or 50m surplus in 10 years...) and the pensioners effectively have an option on the company equity, so shareholders can be zapped even if the company is well run and profitable.
For closed DB schemes it's a bit easier because the problem is at least naturally shrinking with time. Ideally for an open DB scheme I'd like it to be run on a matched liability basis so that there's structurally no deficit or surplus possible and the business can be valued (and run!) net of pension issues. Of course unfortunately it would cost an arm and a leg to match liabilities (e.g. with 100% index linked gilts) at the moment, but the thing is if the market is even vaguely right about how it prices linkers, it will cost an arm and a leg anyway later on...
Still I decided to live dangerously and bought a stake :-)
Paul, Equity Swap is normally a synonym for Equity CFD. It should be economically the same as a straight equity share transaction except there is no SDRT on the buy leg. However protecting the investor against downside sounds more like a written put option. No mention of a premium suppose? I agree very bargepoley.
Hi Monty,
There's an interesting post on the advfn bulletin board, post 6323 (amongst hundreds of total garbage posts - the QPP board there really is Muppet Central!) where a knowledgeable poster, CockneyRebel, quotes Killicks as saying that the 97m share Placing at 17.5p was not in fact a straightforward Placing. Rather it was a equity financing facility whereby QPP issues 1/12th of the Placing shares each month, in return for the current market value of those shares at the time they are issued. Hence why the monies appear as a Debtor. Of course as the share price has dropped by two thirds, then they will need to take a P&L hit for circa £8m by my calculations, if the share price remains low.
This also explains why the CEO has been so desperate to talk up the share price! None of this was disclosed at the time, so really the company's previous announcements about the fund-raising appear to have misled the market. It's also badly back-fired.
I don't see how the CEO's positions is tenable any more. He's played fast & loose, and it's going badly wrong.
Also consider that there are numerous vendors of businesses to Quindell who were paid in shares, who have lock-ins expiring in the coming year, and who are likely to be seriously annoyed at the collapse in value of the shares. This is likely to be a constant stream of sellers. Meanwhile, there is only one Institutions on the >3% list at QPP (Investec, with 4.4%), and after all the recent shenanigans I doubt whether any fund managers will take the career risk of buying into the company now.
The interesting thing is whether the P&L figures are real. If they are, then the business could be very good value - it's on a forecast PER of just 3.3. But for me, the forecasts simply don't make sense. They've taken a load of fairly humdrum insurance-related companies, combined them rapidly, and all of a sudden we're supposed to believe that this is generating spectacular profits. To be blunt, I simply don't believe the numbers.
But time will tell.
Regards, Paul.
Paul -
There is an interesting discussion in today's (Saturday) Investor Interactive forum about the nature of the swap. Killik's statement appears to say that the price risk is borne by QPP. QPP issue 1/12 of the total placing in shares ever month and receive the "prevailing market price" for each share. This is not a swap in any sense of the term. But then I wonder what's in it for the counterparty - there is no commercial value in this deal. However if QPP have covered themselves by taking out a swap with a second counterparty to cover any loss (i.e. the price falling below 17.5p) then that would be swap and QPP would have paid a consideration for this in December. Anything from 4% to 10% I would guess. The trouble is that there is too much speculation and not enough facts. I have googled and cannot find Killik's statement that every forum board seems to quote from. Let's hope the sunday papers throw more light.
Ram
Re Ocado, I recommend downloading and looking at the short disclosures on the new FCA web-site. There is a LOT of short interest. Personally, I wouldn't bet against a hedge fund. I've read Einhorn's book and the analysis was incredible.
http://www.fca.org.uk/firms/markets/international-markets/eu/short-selling-regulations/notifications-disclosures
Anthony,
Re: Short Interest - when it was first published I used to download the spreadsheet and analyse in excel. However Castellain Capital has done the hard work for us here:
www.shorttracker.co.uk
So I don't bother with my own analysis and just look here now.
With Ocado (LON:OCDO) et al. I really don't want to bet against the hedge funds, I'd really like to be short with them but can't be at a reasonable risk/reward level because the existing large short positions means that the borrow is expensive and there's a high chance of a short squeeze at some point.
That said I don't think hedge funds are infallible since Einhorn's book also describes a world where hedge fund managers share ideas quite extensively so are open to herding. There are also the ego battles e.g. Ackman vs. Ichaan where taking sides and being proven right seem to be more important than superior uncorrelated risk-adjusted returns to the managers.
The one I'd really like to hear the hedge fund bear case for is Home Retail (LON:HOME) the fourth most shorted UK share. My feeling is that these are 'story shorts' who have a negative view on UK retail and are shorting Home Retail (LON:HOME) as one of the biggest UK retailers maybe based on what appears superficially to be a largeish P/E. However it was PP who first pointed out their fully owned storecard debtor book asset of £0.5b, when you combine this with their £0.4bn cash then their £1.2b market cap is really only an underlying EV of £0.3b which equals last year's OCF or 1.5x last year's £0.2b FCF. And this in a tough retail environment. I can't make the case that this is an amazing business but surely the UK's no.2 internet retailer deserves an EV/FCF rating greater then 1.5? Hence I'd love to know what the hedge funds' rationale really is. Because if they have it wrong with 12%+ stock outstanding then this really should be a big farm bet for me!
Cheers,
Danger
From memory Capital Drilling (LON:CAPD) gets approx 20%-25% of revenue from Centamin (LON:CEY), its certainly not the majority of their revenue and of course in the medium term drilling rigs are relocatable. IMS is due middle of this month, at current levels a lot of the potential bad news is priced in imo. Beans4tea has done some good posts on CAPD & its sector over on MF in the past few months.
Capital Drilling are intrinsically linked to Centamin (LON:CEY) unfortunately as the majority of their revenue comes from them. Both are great undervalued companies but the Egypt court case for Centamin over mining rights is a heavy burden.
A bad RNS for Centamin indicating their court case is not as cut and dry as first thought and gold prices being down today are the root causes.
Re Ocado, the other reason for treating anything Goldmans say about it with a bucket of salt is that several of the founders are ex-GS! IMHO GS are the most obviously prejudiced research house, whose analysts consistently talk their traders' book.
Hi Paul and all,
There was a late released trading update this morning (11:30am) from Zytronic (£ZYT), the material part of which reads:
"...as a consequence the result for the year will be very significantly behind market expectations, with year to date profitability more than halved."
It's hit the share price pretty hard at 31% down currently. The statement ends with:
"The company continues to be cash generative and is in a strong financial position with cash of £4.6 million and borrowings of £1.8 million as at 31 March 2013 and is still in a position of having several very interesting projects with the potential to materially improve future performance."
I'm pretty displeased with the profit warning this morning from Zytronic (LON:ZYT).
It was my understanding that management were supposed to warn as soon as it becomes apparent that profits are on track to be more than 10% below consensus estimates, but the Zytronic (LON:ZYT) Directors have instead waited to drop the bombshell that profits will be ~50% below?
Very poor shareholder communication imo....will now be going along to the presentation on 21 May to have a cathartic shout at them!
Francis
Hi Francis (and Chris, who mentioned the same thing earlier in the thread),
Yes indeed, very disappointing news from Zytronic (LON:ZYT). I don't hold any shares in it, because as I mentioned in the conclusion to my article from Dec 2012, although I liked the company, I didn't see much upside on the share price (around 318p then) based on previous forecasts.
Now that they've announced that they're going to miss those forecasts by seemingly quite a long way, then really all bets are off. They've screwed up their previously excellent 5-year track record of EPS growth, which is a real pity.
The big question is whether sales have just been lumpy due to the nature of client projects (and therefore could recover), or whether they are losing contracts to competitors?
I'm not tempted to buy any yet, because the outlook has completely changed, from positive to uncertain/negative. Pity, but there we go - these things happen.
Regards, Paul.
Hi Paul,
Re: Goldman note on Ocado (LON:OCDO) - I note that Goldman were joint bookrunner for Ocado (LON:OCDO) 's last placing and stabilisation manager for their flotation - may help explain their positive view on the company.
The problem with all the obviously overpriced shares (ASOS (LON:ASC), Ocado (LON:OCDO), £CPR) is that they have pretty extensive existing shorts outstanding on them making them prone to short squeezes and too expensive to get the borrow. It's a shame there are not readily available significantly OTM long term put options available because one could take a long term view with limited risk and without being stopped out.
Re: Kentz (LON:KENZ) - Cashflow is a concern as a lot of their profit is getting sucked into working capital. Before taking a big position you may wish to make sure you are happy with the company's explanation for this.
CEV gives a much better analysis of this than me here:
http://www.stockopedia.com/content/kentz-beneish-m-score-flagging-high-risk-72742/
Cheers,
Danger (Long Kentz (LON:KENZ), Ocado (LON:OCDO) no position)
I guess the risk is what happens if the 10M isn't enough to buy back all the shares at 82p ???
the logical thing to do if you hold over 50k is to sell all but 50k, meaning everyone will be left with 50k or less, and yet only half the shares can be bought back ? I guess if some is held by insiders or people happy with taking it private then it's not a problem, not sure if this can be assessed, which I guess is where the small risk to my suggest wheeze above comes in,
K
if you can sell back 50k shares at 82p guarenteed, and you can buy at 78p this morning, is this not a risk free way of making between 1 and 2 thousand pounds risk free ?
buying at 78.39 (including stamp duty), =39,195 + say 10 pounds trading costs,
selling free of costs at 82p =41,000
not big bucks, but anyone with a pile of cash, waiting for opportunities, could take advantage,
I don't know what the timescales of getting the cash would be, but if it's just a few weeks, not a bad risk free return,
K
Hi Paul,
I agree with Gostevie, the price of CAPD has moved up and down in recent months with CEY and the legal proceedings surrounding this Egyptian mining share.
Merlin51
Hi Paul
Re. QPP. You have a superb nose for ferreting out dodgy dealings leaving the traditional analysts at the starting gate. I think we ought to insure it like starlets insure their precious body parts! :)) Dodgy pension deficit accounting is another one that you have turned your flashlight on in the past. Superb attention to detail. Thank you. Ram
Hi Paul,
This RNS from Centamin might explain why Capital Drilling are down again today:
http://www.investegate.co.uk/centamin-plc--cey-/rns/egyptian-legal-proceedings-update/201305100703024160E/
Centamin are also down about 13% at the moment.
Steve
Hi C
I think the report says the company will spend £10.5m buying its own shares back at 82p (ie it will buy c12.35 million of the company's existing c23.7 million shares) and this will be done by tender (ie you apply for it). Those left holding (those who do not apply to the tender, or who do not get taken up if it is over-subscribed) will be shareholders in a private firm, which makes trading the share quite difficult. I agree with Shanklin (if my interpretation is right). It suggets the bigger shareholders want to keep a potentially very good thing for themselves. My, the world is ill divid! [Sorry, I took so long to type this Shanklin got there first!!!]
Yes, but if you have 50k HGV shares or less, you have the option of being paid 82p/share on your entire shareholding.
They intend returning £10.25m of this cash to shareholders via a tender offer at 82p (the shares are currently 78p), and then De-List.
this means shareholders should get over half their money out, but I don't suppose they'll be thrilled with the de-listing,
do you mean a special divvi, or do you actually mean a placing?
Paul, in terms of your analysis of HGV I think a better comparison would be with Lee Foods which de-listed at a small premium to the SP of that time and has apparently thrived since de-listing. Essentially, it appears that management and some of the major shareholders are seeking to gain the vast majority of the upside in HGV whilst squeezing out the small shareholders.