Small Cap Report (22 May) - ZYT, PGB, INL, CHH, PMP, SID, APH

Pre 8 a.m. comments
I'll comment on Zytronic (LON:ZYT) after 8 a.m., as it's not especially time sensitive.
Things that might be time sensitive include a contract win announcement from Pilat Media Global (LON:PGB). This is an Anglo/Israeli company with interesting-sounding company which supplies software to the television sector, globally. I have been a shareholder since being very impressed with their cheap valuation (in my opinion) relative to what struck me as good results, and also an amazing balance sheet which has around half the market cap in genuinely surplus net cash.
Pilat (pronounced "pill-at") had already issued an upbeat outlook for this year, so another contract win should give things a nice boost. It's for AUS$7.5m which at £1= AUS$1.5 translates to £5m, which is pretty material to Pilat's results, although it's a split of licences & implementation revenues that will be spread over this year & next year.
At 40p, Pilat's market cap is only £25m, yet it had £10.7m in net cash at the last set of results, for the year-ended 31 Dec 2012, announced on 25 Mar 2013. Moreover, that's real surplus cash, not up-front payments from customers (which many software companies use to flatter their cash balance - you can check by finding out what the "deferred income" creditor is, as this should strictly be netted off against net cash).
Furthermore, Pilat's profit of £1.8m last year is after accounting for £1.1m of amortisation of intangible assets. I checked the Annual Report, and it turns out that this amortisation charge is purely historic, and no current costs are being capitalised. Therefore the real profit figure to focus on is actually £2.8m for 2012.

The outlook statement on 25 Mar 2013 was strong (see below), and this £5m contract win announced today is likely to make the 2013 results even better. As such, I reckon these shares are a bargain, but as always this is just my opinion, so please do your own research. The Israeli angle may put off some investors, but I've made enquiries and am told that this company & its management are kosher.
Pilat Media is in a very healthy position. It has a strong balance sheet with significant cash resources which it expects to grow as operating profits are expected to improve. The Group's pipeline of revenues from existing clients already enables revenues in 2013 to reach over 80% of the 2012 level.
The Group is involved with several additional opportunities already in advanced procurement phases where Pilat Media is well placed to win, although timing can not be reliably predicted. These can potentially make a significant contribution to the 2013 revenues. OTTilus also provides the Group with an opportunity to expand into new markets as well as enhancing its offering to existing clients. The Board therefore looks to 2013 as another year of significant improvement in both market position and financial results.
They couldn't have spelt things out more clearly, it's going to be a good year! Here we are two months later, and a £5m contract win is announced, so they're delivering on what they said would happen, very reassuring.
There's also a very useful audio interview with the CEO of Pilat Media on 8 Apr 2013, from BRR Media, here. I am hoping to do some audio CEO interviews myself as from next month, but only for companies hand-picked by me, not as a commercial thing, as part of my quest to disseminate good information on quality companies to the private investor community.
It just looks the wrong price to me.
As already mentioned, I am a shareholder in PGB. The shares are very illiquid, and it requires patience to buy stock.
A lot of friends have shares in Inland Homes (LON:INL) (I sold mine at 31p on a spike up a while back), so will be interested to read their latest trading update.
It sounds good - some decent-sized projects have been acquired and/or received planning consent.
As you can see from the two-year chart on the right, the shares have had a good run lately, being up 50% in the last six months, so I'm not sure how much further it can go in the short term?
Including some off balance sheet assets, NTAV is probably around 35p a share, so I reckon it could have upside to 35-40p perhaps? If you're comfortable with management here, which I am not.
Post 8 a.m. comments
Another company where I'm not comfortable with management, is Quindell Portfolio (LON:QPP). Yes, it must have been at least a week since I last mentioned it! They've announced what they call a "major UK contract win", in typically under-stated terms. Firstly, since they operate in the UK, one would expect it to be in the UK, so I assume putting in "UK" is intended to create an impression of global reach?
Initial licenses & maintenance fees are £3.5m up-front, which is hardly "major", considering broker forecasts expect £442m turnover and £92m profit this year. The shares had an initial pop, but are now settling down up 5% at 8.8p, well down from recent highs. Here is the last twelve months chart, so you can see the turbulence in the last month, when it gradually became apparent that the company had misled the market about the true terms of their last Placing.
Maybe this is a good business after all? Who knows? Personally I don't trust management as far as I could throw them, because there's so much rampiness in their announcements, and numerous other red flags - such as a ridiculous number of acquisitions done in rapid succession, inadequate explanation of where profits are actually coming from, and results that simply look too good to be true. Plus of course profits ending up in debtors. Oh, and that they misled the market about the Placing in Dec 2012, and that we still don't know who they lent £15m to, or why. I shall read the Annual Report with a fine tooth-comb, when it is issued.
So I remain a sceptic, but am perfectly willing to accept that I might be wrong. However, it will take a few more sets of results, with cash coming in consistently, before I believe this is real. By which time the shares could be multiples of the current price - as these shares are either massively over-priced, or massively under-priced. It's a binary situation - so you pays your money & takes your choice, or in my case you just don't like the smell of it at all, and steer well clear!
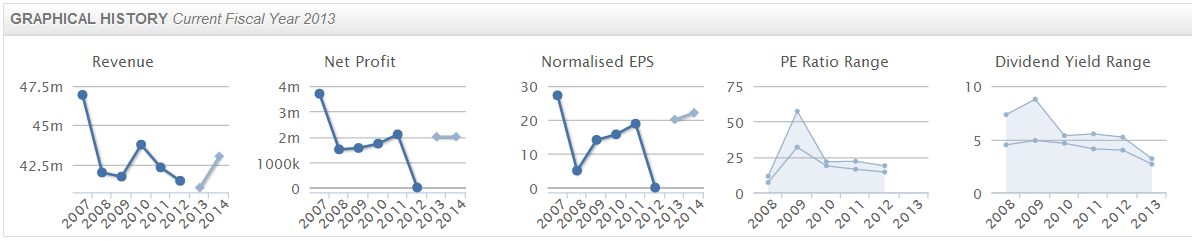
Churchill China (LON:CHH) issue an in line with expectations trading statement, describing trading as "encouraging". The shares don't look good value to me, 20p EPS is forecast for this year, so at 349p that puts them on a PER of 17.5. So I would say that the market has already priced-in a bit of out-performance above forecasts.
Churchill's five-year track record looks fairly lacklustre to me, as shown in the Stockopedia graphical summary below (which I find incredibly useful to quickly absorb loads of trends simultaneously):
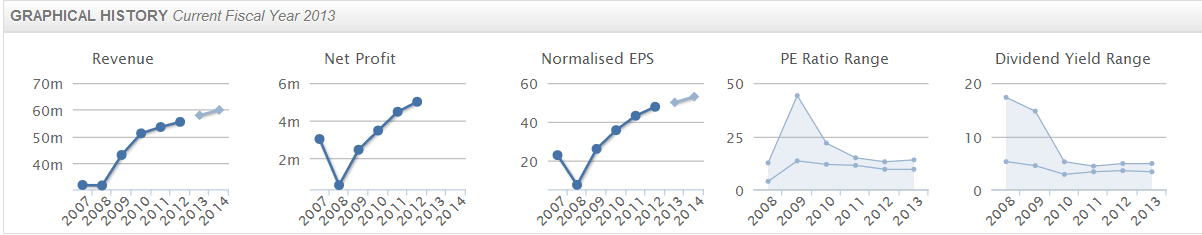
My own pick in the pottery space is Portmeirion (LON:PMP), which looks both more reasonably priced (PER of 13 on 2013 forecast earnings), and also has a fantastic five-year track record - just look at how EPS hase risen since 2008:
Silverdell (LON:SID) has announced the appointment of an experienced new Non-Exec, John Matthews.
I don't know why Silverdell shares have dropped lately, but they're down from 20p to 14p since Jan 2013. I did hear a rumour (apparently triggered by an Edison research note) that they might need another fund-raising, but that is only a rumour, so who knows? The company needs to issue a statement to confirm or deny this, in my opinion, as a material move in share price has happened and it's unsettling investors.
In my opinion it's a sound company, so I picked up a few shares this week at an average of 14p, as a long-term position. Only small though. Here's the three year chart for Silverdell, showing the sharp sell-off recently:
On a matter of house-keeping, I had to sell something to get the cash for Silverdell & other things I've bought recently, so reluctantly I've thrown in the towel on Begbies Traynor (LON:BEG). It's just taking too long, and with no sign of the insolvency market picking up for the foreseeable future, I've decided to put that money to use elsewhere.
Incidentally, you can check my current holdings any time, on this page on my Blog, which is kept up-to-date all the time. It saves cluttering up these articles with every transaction, which is not really what these reports are about.
I don't think much of the AGM statement from Alliance Pharma (LON:APH) today. It mentioned turnover being 6% ahead, but says nothing about profit compared with expectations, which is the key piece of information that investors want to know!
Mark Slater mentioned this stock at the UK Investor event recently, it's a long-term holding of his.
Regarding Zytronic (LON:ZYT), I'll add my latest thoughts to the specific thread on the company, a bit later, am a bit busy looking at other companies right now.
Stockopedia Webinar
Ed tells me that several hundred people have already signed up for his Webinar tomorrow at 1pm.
Should be really useful - where Ed will demonstrate how to get the best out of Stockopedia. It's free, so why not join, if you're available for 30-40 mins tomorrow at 1 pm? Click here for details.
Right, mental overload has well & truly set in, as usual at this time of the morning! So I'll sign off. Have a good day & see you same time tomorrow as usual.
Regards, Paul.
(of the companies mentioned today, Paul has long positions in PGB, PMP, SID, and INL (token amount). Paul has no short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
Quindell:
This is a software contract, Paul. Their software revenues for 2012 were £30.1m of which UK was £19.4m, so yes it is relevant for them to confirm it's a UK contract. Gross profit on software / licenses in 2012 was 70-90% of revenues, so even if we assume only £3.5m revenues and ignore the forward revenues then this provides a further c£2.5m profit for 2013. Not massive in itself, but add this to all the other contract news.
Hi Marky,
Fair comment. Which business of the ones they acquired is producing these stellar results, and how much did they pay for it, and when, I wonder? The bulk of their turnover comes from Ai, which only makes £3.5m profit p.a., on over £100m turnover.
It would be good to get some third party evidence, from people in the insurance industry, as to whether QPP's profits are genuine or not. I've put some feelers out, and have heard mixed messages so far.
Cheers, Paul.
Hey paul I bought some Silverdell (LON:SID) yesterday too. Just before I did I had a look round but couldn't see much other than their trading statement early last month. In it they clearly stated that they expected a Canadian deal would cost them abit now 6-7m because of expenses such as labour/equipment, but they expected to get it back on the second half as money comes back in from various projects. Im also comforted by who their typical clients would tend to be that the monies should be forthcomming without major issues too. If anthing im hoping the fall is just to do with people seeing better things for their money. As this is a boring share linked somewhat to construction
Paul, I went to Proactive Investors last week and saw Alliance CEO John Dawson present - here's a (lengthy) summary which I posted on ADVFN - may be useful for any holders out there.
--------
John is one of the few presenters I’ve seen who finished exactly on time: He presented an overview of the company, including a very useful slide showing the age of some of the products in the portfolio – the average age being 34 years!
He also showed a sales graph of the products, averaging circa 3% pa, and then walked through some P&L graphs etc, both historic and for last financial year.
One chart clearly showed the impact of Deltacortril and the massively +ve impact it had on the bottom line. Removing this one-off event, the profit trend was very clear, with a gradual rise since halting work on the sleep drug the company was developing back in the mid-2000s.
John then discussed prospects in some detail for some of the larger contributors, specifically:
Ashton & Parsons – baby food – this is very much in demand, and sells on ebay for far higher than the retail price (I checked this and it is indeed true). This product was manufactured using very old machinery (40 years rings a bell) so it kept breaking down. New machines are being commissioned to come on stream later this year (I’m not sure at whose cost – I’ll follow up with John on this). Once in place, production will resume, and given the pent-up demand there is no reason to assume that the product won’t contribute significantly later in the year.
Acne treatment – again this is a product that is being promoted (John mentioned youtube videos by youths praising the product – I’ve yet to check it out…)
Immucyst – product produced by Sanofi until the plant had issues – this will contribute in FY14 when it comes back on stream, and should be very +ve next year.
Acquisitions this year – John showed a slide with acquisitions per year; none so far this FY but given the past record and the firepower available I would be surprised if there weren’t any.
Cashflow – it was very clear that APH is very cashflow positive – a useful table showed that basically acquisitions are funded from cashflow (save a small increase in debt last year of around £2m) and that dividends are a small proportion of available cashflow.
Dividends – APH will continue to pursue a ‘progressive’ dividend policy, but without committing to % each year (cover I think is currently 4.4 times so plenty of headroom there). I asked John about this afterwards, and he was clear that dividends will be paid out of available cash and that acquiring new products are the priority – something I agree completely with.
Questions at the end:
*Amortisation – an ex-accountant asked why APH don’t amortise the value of the products they acquire. John mentioned this has been discussed many times – the accountants are happy with the current treatment. Also given the age of the products – over what period should they be amortised over? It looks like a product pays for itself after around 4 years (given a bedding in period of around a year after buying it). So clearly if you amortise over 20 years etc there would be a relatively minor P&L hit.
*Debtors – someone asked why debtors had gone up (I think by between £1-2m) when turnover was broadly the same. John didn’t know the answer to this (one for the FD) but it’s a relatively small amount in the sales context.
*Competition for new deals – interesting question about this – when Alliance Pharma (LON:APH) bid for a product, is there much competition? John said there is usually at least one other bidder, sometimes they go to auction. He also commented that APH are seeing more opportunities – as big pharma are more keen than ever to shed smaller, niche products.
Overall impressions – It’s the 2nd time I met John in the past month (1st being Master Investor), and he came across very well – very knowledgeable about the company, optimistic about future prospects etc, explained everything very clearly and concisely.
He very clearly talked through the company’s model – very much a virtual organization in terms of manpower and production, with a small core staff dedicated to finding new deals, establishing a sales presence in Europe etc. I asked John previously about expanding into manufacturing – he was less keen on this as clearly it’s something that is not their core competence – and given the diverse range of products in the portfolio, also makes sense.
Alliance Pharma (LON:APH) came across as a having a very stable core of products, with a good margin and gradual sales growth. When promoted, sales growth was shown to be in the order of 100% in some cases. Also new opportunities can produce one-off spectacular sales, such as Deltacortril provided, until generic competition enters the space.
John made the point about how they get their deals – quite often big pharma will divest a small, non-core product because it’s exactly that – and they need the manufacturing capacity for other products. So this presents opportunities for Alliance Pharma (LON:APH).
Finally it’s worth remembering the large shareholding owned by John and his family – so often companies present at these forums where the board have little or no ‘skin in the game’ – instead they have loads of options, bonuses, contracts with their own service companies etc. The fortunes of APH's CEO are aligned with the company, so there is every reason to believe his are a ‘safe pair of hands’.
Cisk,
Great stuff, thanks for sharing!
Paul.
PGB web site says "Offices strategically located in the US, UK, the Netherlands, Australia, and Israel keep Pilat Media on top of the latest industry trends and technologies. They are staffed by our international team of more than 200 professionals who are well versed in the local standards and business practices of each region."
Headquarters are in London - not sure how much also being listed on TelAviv exchange matters.
How does Pilat Media's valuation compare with other Israeli companies listed locally? You'd expect a blanket war zone discount (sadly the Middle East is more likely to blow up than say Shropshire).
Paul, Do you understand why PGB don't use some of that cash to pay a dividend?
Good question alterego! In a word, "no", I don't know why they don't pay dividends, when they clearly have plenty of cash to do so. In the past they spoke openly about plans for the cash pile, but have gone strangely quiet about it recently. Perhaps there is an acquisition in the pipeline?
There is an issue with the 2 large shareholders - one is connected to a Director, and the other tried to buy the company on the cheap a few years ago, but was rebuffed. So there are apparently some issues between these 2 shareholders, who do not see eye to eye apparently.
However, in my view that's probably a good thing for small investors, as we're not likely to get stitched up, compared with if 2 large shareholders were acting in concert & therefore controlling.
It's a pity they didn't use the cash to do share buybacks when the shares were cheaper.