Small Cap Report (8 Apr) - IND, GBO, VLK, MEC, SNCL, FDL, GHH, ECK, SSY

Pre 8 a.m. comments
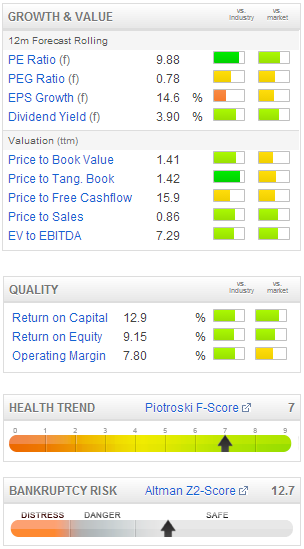
A UK fund, called New Pistoia Income Ltd has this morning announced an increase to above 4% in Indigovision (LON:IND). So what, you may ask? What intrigues me is that this is a former >3% shareholder in the company, which sold out in Dec 2011. So here they are, as a fund that knows IND well, buying back in. Therefore it seems to suggest that New Pistioia share my belief that the turnaround strategy of the new CEO at IND is credible, and stands a good chance of delivering very much better performance this year & next year.
As I've mentioned before, the main risk with IND currently is that they need to achieve an H2 (6m to 31 Jul 2013) of more than double H1 in EPS terms, in order to achieve forecast full year EPS of 32.7p. Management are upbeat about the prospects for H2, due to projects in the pipeline, and new product launches, but I can understand some investors wanting to see the figures in the bag before relying on them.
Of course the shares will be a good bit higher if you do wait for confirmation, so personally I'm anticipating success, & hoping for the best. Investing is ultimately about backing management, and I don't recall seeing a more intensely focussed CEO than IND's, who is really leading from the front to improve the company's performance in many areas. That has to deliver better figures at some point.
Results for the year ended 31 Dec 2012 from Globo (LON:GBO) look very impressive on the face of it. Turnover (from continuining operations) up 67%to E46m, EBITDA up 42% to E24m, and profit before tax up 43% to E17.2m.
As mentioned before, this company uses aggressive accounting policies, including capitalising a large amount of development spending each year. So when you look at the cashflow statement, it shows a very different picture.
Net cash from operating activites was E13.2m, but E11.6m was spent on purchases of tangible & intangible assets - in previous years this has been overwhelmingly capitalised development spending, which are internal costs, so arguably should really be fully expensed through the P&L each year.
This year there is also a £6.7m cash outflow relating to the disposal of a subsidiary, which seems to suggest that they gave away that amount of cash with the disposal of their Greek operations? Seems a bit strange to me.
Furthermore, this company which is presented as being highly profitable and successful, once again had to support itself with a E12.1m equity fundraising (on top of the E20.6m fundraising in 2011). I just don't buy it. To be worth £140m, this business should be throwing off bucketloads of cash, not consuming cash. Also, the balance sheet shows pretty high levels of debtors + work in progress, which total up to E38m in current assets, plus E9.7m of long term debtors, which look very high relative to E46m turnover from continuing operations.
So there are enough potential red flags there to make me want to deploy my bargepole with this one, despite the apparently good performance presented.
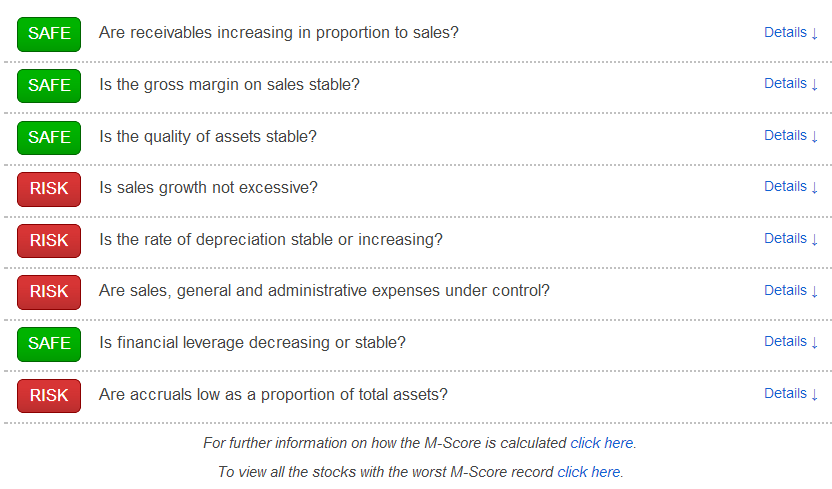
Note that GBO is showing a bad score on the Beneish M-Score - which flags up a risk of "earnings management". I've not looked into this system, but I know Ed at Stockopedia likes it, and told me it correctly predicted problems at Cupid, amongst others. Click here (or click on the screenshot) to view the relevant Stockopedia page on the M-Score analysis for Globo (this screenshot shows part of that page).
There was a positive write-up on Vislink (LON:VLK) in the FT over the weekend, highlighting the value in the company. I agree, and indeed used the sharp dip last week to 28p to top-up. This is a cash rich company which is on a growth strategy under new management, and also pays an excellent dividend yield. I covered the recent results announcement from Vislink in this column, so you can always just search by company name or ticker to look back. I think the shares are overdue a re-rating.
I'm surprised that Tesco (LON:TSCO) have failed in the USA, who face a bill of about £1bn to exit from their Fresh & Easy business in the USA, according to the Telegraph. Tesco have succeeded elsewhere overseas, so I'm curious as to why the USA didn't work for them.
Post 8 a.m. comments
Dutch and Polish publising group Mecom (LON:MEC) has put out a pretty grim sounding profits warning. I dropped this one from my portfolio quite a while ago, having done well on a re-rating, but I became concerned that their businesses were declining at a pretty alarming rate. That's continuing, with advertising down a huge 28% in Jan & Feb 2013 compared with the prior year. That has improved somewhat, but will still be over 20% declines in Mar & Apr. I wouldn't want to invest in any company that is contracting at that sort of rate, as it means that business is in terminal decline, once cost cutting can no longer keep up with declining turnover.
Interestingly, they refer to the economic situation in Holland as a crisis, one tends to think of only Southern Europe as being affected by the Eurozone crisis, but it's clearly wider than that.
Mecom is not one that I'm planning on revisiting. I see they are down 31% to 56p this morning, hardly surprising considering the statement ends by saying;
Taken together, therefore, if the adverse pressures described above do not reduce considerably from current levels, Group EBITDA is likely to fall materially short of current market expectations.
This might be a good time to look at shares in peat producer William Sinclair Holdings (LON:SNCL). They have issued a trading update today saying that exceptionally cold spring weather has caused a delay to the growing season, as you would expect. That's obviously a one-off, so shouldn't really affect how investors value the company. Which may possibly provide a buying opportunity?

It doesn't show on the above chart yet, but the latest price is down to 114p, so that looks to be a potentially favourable entry point, if you like the underlying business. It looks good value on a PER and dividend yield basis, but not enough to make me want to investigate much further, as I'm already over-committed with too many existing positions. There comes a point where you just have to reject every new share idea you come up with, unless they are amazingly cheap, which not many things are right now (although I'm still finding the odd one).
Findel (LON:FDL) issues a year-end (29 Mar 2013) statement which says that full year resuts should be in line with market expectations, that the financial position continues to improve, and net debt is lower than last year end.
I've never liked this company, and question whether it is really viable in the long run - it you total up the losses in the bad years, they seem to exceed the profits in the good years. Also it has all the headaches of running a massive extended payments debtor book to its customers, and hence carrying a load of bank debt to finance it. So there will inevitably be big write-offs whenever the economy tanks.
The number of shares in issue has increased 9-fold, in stages, since 2007 as they had to repeatedly raise money to stay afloat. It's low margin stuff, and they haven't paid a dividend since 2009. Looks pretty awful to me, but that's just my personal opinion, and DYOR as usual.
Maker of specialist optical equipment, Gooch & Housego (LON:GHH) issues a reassuring trading update. I like the way they have given it a title, to highlight the key message, namely, "Trading in line with expectations".
If done honestly, then a title like that is very helpful, because investors read every trading statement with one question in mind, namely, "is this good or bad?", and often mixed trading statements can take some time to decipher. So I like a simple title that conveys the key message, as has been done in this case.
I can't get excited about the valuation though, on a fwd PER of about 14, and a 1.4% dividend yield. It's difficult to see enough upside on those numbers to arouse my interest.
There's an interesting announcement from voice recognition software company Eckoh (LON:ECK). It's some sort of partnership agreement, but doesn't say who with. It appears to be with a payments company and the comments from Eckoh's CEO sound intriguing;
"We are delighted to have secured this strategically important agreement, which because of the financial commitment and the potential value of the opportunities already being discussed, we anticipate will generate significant revenue for Eckoh over the three year term. This partnership further extends our indirect sales channel, which has been a key focus for the business and this relationship has the promise to be the largest driver of partner activity in this new financial year."
Eckoh shares don't look cheap, on a forward PER of almost 20, but if there is stronger growth in the pipeline then it gets a lot more interesting.
I hope their voice recognition is somewhat better than Siri on my iPhone, whose jumbled results are often quite hilariously inept! I lost my rag with Siri the other day, and he responded by saying, "would you like me to look up "Offer Fox Sake" on the internet?!!!"
There is also a contract win from SCISYS (LON:SSY) to provide software to the BBC. Although a £1m contract over 3 years really shouldn't warrant a separate RNS, given that it doesn't look material to turnover of £40m p.a.
I looked at SSY a couple of months ago, and decided against buying any, as it looks a mature business, and mainly supplying public sector. Given that spending constraints are likely to be only increasing there for the foreseeable future, it's not an area I want to invest in. Although the share price has come down 62p, where a forecast PER of just 7.5 is looking attractive. Given that their operating profit is only about 4% of turnover, there must be a higer than usual chance of a profits warning here, so a low PER isn't necessarily a good thing if taken in isolation.
Well that's kept me busy this morning! See you same time tomorrow.
Regards, Paul.
(of the companies mentioned today, Paul has long positions in IND and VLK, and no short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

12 comments
Paul, New Pistoia Income looks like a trust fund linked to Andrew Fulton/Quadnetics:
http://boards.fool.co.uk/director-buys-12433532.aspx?sort=whole#12434110
Definitely knowledgeable buying going on!
I wonder if anyone has tried using Indigovision products in some Lynch style research?
I like the story, but it would be reassuring to know a bit more about their products before increasing my holding.
As for Tesco in the USA, well their successful stores in east Europe & Thailand resemble the big sheds they have in the UK. I gather they tried a different business model in the US. So it's yet another British retailer who failed in the US.
Hi jonesjeff,
The nice thing about Indigovision (LON:IND) from an investors perspective, is that there's loads of third party evidence of the product being very good, from the many systems integrators who install it. Also a lot of IND sites are named by IND themselves, with quotes from the end customer about how pleased they are with it.
Here are a couple of examples I just Googled:
http://www.sourcesecurity.com/markets/education/application/co-882-ga.957.html
http://www.securitynewsdesk.com/2011/04/15/asia%E2%80%99s-largest-ip-video-installation-at-delhi-intl-airport-using-indigovision%E2%80%99s-control-center/
OK, it's easy to get customer quotes - but only if the customer is happy with the product.
Also, you can check out the quality of the low bandwidth video yourself, here on Edinburgh Zoo's "panda-cam" supplied by IND!
http://www.edinburghzoo.org.uk/pandacam.html
Cheers, Paul.
Hi Paul,
Hope you don't mind me mentioning a distinctly non-microcap on this thread.
I attended Amec (LON:AMEC) 's AGM last Thursday and have posted a 5 page report on ShareSoc's member network*. Interestingly, even though AMEC is a FTSE100 business, there were only around 30 investors present and plenty of opportunity to ask questions and chat informally with directors afterwards, just as with smaller-cap AGMs.
As you can see both from my report and analyst forecasts, AMEC's outlook appears sound (despite concerns about the natural resources complex/commodity prices), with strong growth forecast. Stockopedia's value metrics look pretty attractive to me:
Needless to say, I hold AMEC shares.
Cheers,
Mark
*Only available to ShareSoc members (free associate membership is available)
Hi Mark,
I've just had a quick look at Amec, and must admit it looks good - very good earnings growth, on a PER of 11, and almost 4% divi yield. This shows an excellent track record:
Hi Paul - re. Globo (LON:GBO) its definitely worth investors doing some duedil on earnings quality. Obviously our earnings quality filters like the M-Score are algorithmic/mechanical but statistically these things have been shown to work across portfolios.
We have another Cheat Sheet like the Beneish M Score which is called the Montier C-Score (short for... "Cooking the books score"). It isn't flagging as extreme for GBO but does again highlight some areas of concern - http://www.stockopedia.com/apps/montier/?ticker=GBO
The one positive is that Accounts Receivable aren't growing - but both cheat sheets do highlight that GBO shows large accruals - i.e. the company isn't turning profit into cash. The kind of company you preferentially want to invest in has very conservative or low accruals - i.e. all profit becomes cash profit. Shares with low accruals vastly outperform shares with high accruals - you can read up more on this and earnings quality in general here http://www.stockopedia.com/content/the-accrual-anomaly-why-investors-should-care-about-accruals-earnings-quality-63003/
Of course with growth stocks like this a lot of people forgive a lack of cashflow as the company is investing for growth but red flags like these always worry me personally. Investing is a game of odds - I've been burnt so many times believing the dream in small caps where the story looked great but the numbers didn't quite stack up that I've learnt place my bets carefully.
The most surprising thing about GBO is that almost none of the shareholders I've spoken to have actually downloaded the app. I raised this once on the ADVFN board and was almost crucified... reminded me of this...
"A group of medieval scholars were debating how many teeth were in a horse's
mouth. To answer the question, each person stood up and cited their favorite
authority--but there was still NO agreement. A junior member of the group,
then suggested that the group should go outside and simply "COUNT" a horse's
teeth--to resolve the question once and for all! Upon hearing this, the rest
of the group became so alarmed that, according to the manuscript, they "fell
upon him, smote him hip and thigh, and cast him from the company of educated
men." (as quoted by James Trefil, READING THE MIND OF GOD, IN SEARCH OF THE
PRINCIPLE OF UNIVERSALITY, Charles Scribner's Sons, New York, 1989, pp33-4)."
Ed,
Very shrewd point IMO! When I was looking at GBO I remember trying to do google searches for "bring your own device software" etc and was struck by how a) hard it was to find Globo's products in this sector, despite this being their flagship product they tell investors about and b) how many other big names have BYOD packages - do you really want to be competing with Cisco in selling enterprise software? (As an aside, I'm surprised more investors don't do this kind of Peter Lynch style customer-level research. It would have kept them all out of Cupid PLC for one!) This combined with the aggressive financial accounting has kept me away - P/Es are meaningless here for valuation and something like the P/S ratio is probably better.
That being said the share has doubled since I did my research so what do I know? :)
"It's only when the tide goes out that you find out who's been swimming naked".
I do thoroughly believe that much enterprise software is going to be eaten by a trend that is known as the 'consumerisation of IT' - try a google search. We use Dropbox, Google Apps, Uservoice and other cloud services for many functions at Stockopedia - sure we are a small company but the trend is plain to me. I don't quite know how Globo fits into this trend.
Globo's Go! Enterprise website has several videos about their services and product that don't showcase the product - which I find odd - after a couple of years you'd think they'd have more to highlight the product than just some stock photos and some old fashioned software boxes - maybe some case studies, testimonials, press etc etc. It may be that they need to hire a better marketing & comms team - if I had the money Globo do I would definitely sort that out. http://www.goenterpriseserver.com/GOEnterprise.aspx
Beyond that I did download their application about 18 months ago from the website and found it didn't work. The company did resolve the issue within a couple of days after I contacted them, but again it made me refrain from purchasing the shares.
So today I downloaded the demo app from iTunes again. It's got the basic calendar/task/email apps as well as ERP and CRM stuff. While basic it works ok for the most part - though it crashed when I tried to send my first email. On opening again I tried to forward another email to my own account a couple of times - it couldn't do that either - both emails are just hanging in my pending actions folder (see below). Maybe just something to do with being a demo app?
[edit: I have actually received one email from the app now (I think the first one). But 2 still hanging. ]
I had a bad experience owning RCG shares (another foreign domiciled AIM tech stock) in 2007 when a facial recognition product I received from the company locked me out of my computer forever - but I was such a believer at the time that I just ignored the red flag - I managed to get out at 65p for a 50% gain but way off the 140p it peaked at - it taught me a big lesson.
Regardless, I'm surprised you don't get any sales or marketing materials through by email from Globo, or any sales people checking on you like when you sign up for a cloud enterprise app with most companies. They may want to work on their web based sales and marketing generally.
What I personally vowed to do from the financial crisis onwards to trust the numbers to do the work rather than the story - hence Stockopedia and our efforts to highlight earnings quality and financial risk through simple algorithms. It's all a game of odds and while I may miss out on the odd tenbagger I'll hope to still have my shorts on when the tide goes out ;-)
Just to clarify about Tesco, I think their total bill including previous investment may well result in a £1billion loss on their US adventure. Exit costs from the US may well run to a couple of hundred million from here, but that's part of the £billion lost. Big money, but when you consider the company makes almost £4billion a year pre tax profits, it was a gamble for them worth having a shot at. Tesco are very successful in other parts of the world, but they joined the graveyard of many British companies trying to break into the US.
I think the city will be happy once they announce their exit plan policy and despite the loss it explains a little why Tesco's share price has been recovering the last 3-6 months since they made the announcement that it was under review.
Paul,
I'm still not quite sure about the capitalization of software development costs. If a company were to build a widget manufacturing machine, which they could then use to manufacture and sell widgets profitably, then it would seem fair to represent this machine as an asset on the balance sheet.
Why is software different? If a company spends money building a great bit of software they can sell over the next few years- is that not an asset too?
I'm reasonably comfortable about the intangibles in Globo's case, as they're now getting to the point where the intagibles section of the balance sheet is not growing rapidly (they created 11 million of intangibles, but also wrote off 9 million). Sales to intangibles ratio (which should give a feel for if these are productive assets) is 2.76 in these results, as opposed to 2.25 (including discontinued) or 1.35 (continuing operations) in 2011.
In other words, the sales to intangibles ratio is growing, which means each pound of intangibles on the balance sheet is producing more sales than it was last year.
Hi Marlint,
Thanks for your thoughts on Globo. Points noted.
My feeling with software is that generally speaking development spend should be expensed through the P&L, because it is ongoing, rather than project-based for most software companies - i.e. they need to keep spending a certain amount on development, just to stand still.
Also, the pace of obsolescence is so rapid now (especially with mobile apps) that what's hot today could be old hat in 1-2 years. I much prefer the more prudent approach companies like Indigovision (LON:IND) take, of expensing all R&D each year, and showing it as a separate line on the P&L.
Globo's cashflow statement concerns me the most - where are all the profits? They just seem to disappear by the time you get to cashflow, which is a big potential warning sign in my view. It might all turn out to be fine, but cash is king in my book, and bigger profits ending up with larger & larger debtors, combined with repeated equity fundraisings, all makes me uncomfortable.
Regards, Paul.
we never know the real reasons why any business fails anywhere, so here goes ;)
There are a number of reasons (none individually significant) why Tesco (LON:TSCO) failed in US.
- their choice of locations - suburban CA and AZ metros which had seen the best of the real estate boom - for their initial stores roll-out just as the real estate bubble was beginning to pop
- in chatty laid back CA self-service check-outs (don't call them tills pls) with no human interaction was a bit too much for the typical consumer
- their convenience food choices apparently done after a lot of pre-launch research was good but NOT for the price
- unless you are within 15 miles of a top 20 metro in the US, buying in bulk is built into the consumer psyche. What are those room size fridges for then!?