Small Cap Report (9 Apr) - LOQ, GTC, DRV, NPT, NRR

Pre 8 a.m. comments
Another contract win for a widely-followed company, Lo-Q (LON:LOQ) has been announced today, this time for a theme park in Turkey. No financial details are given, but it's a 2-year contract, with an option to extend for another two years, to provide the Q-bot virtual queuing system for eight of the park's largest rides.
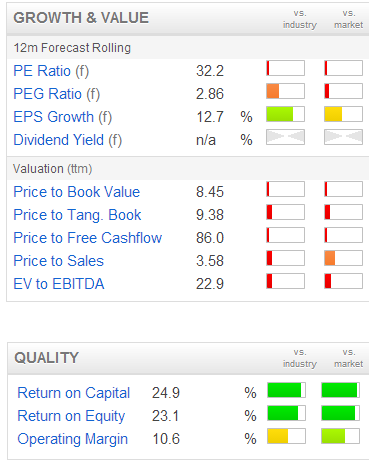
The shares recently peaked at a pretty bonkers price of around 670p (which was a forward PER of about 40!), but have since come off to a perhaps more reasonable 537p. The forward PER of 32 doesn't tempt me I'm afraid, still much too warm for my tastes. Although as supporters point out, each contract won is a stream of recurring revenues, so earnings will lag behind the valuation, which is an argument that has some merit to it.
EPS will surely need to come in a long way ahead of broker consensus of 16.2p and 17.6p this year and next year, to justify the current rating? I can get to a price of about 400p at a stretch, but a more reasonable price looks to me around 300p based on existing forecasts. But if you think they will out-perform forecasts, then it's worth more! You pays your money, and all that.
They should start paying dividends now too, in my opinion. I notice that the Beneish M-Score throws up a warning flag over possible "earnings management". Don't shoot the messenger, I'm just pointing it out as an area that investors might want to look at, and gain reassurance about.
I like the look of results from Getech (LON:GTC). This is a specialist consultancy in the resources sector, which owns a database of global garavity and magnetic information, which is licensed to oil exploration companies.
At 65p the market cap is £19m.
Interim results to 31 Jan 2013 show a very successful half year, with turnover of £4m delivering a profit before tax of £1.4m (up a whopping 290% on the equivalent prior year period), although the increase against last year's H2 is less pronounced.
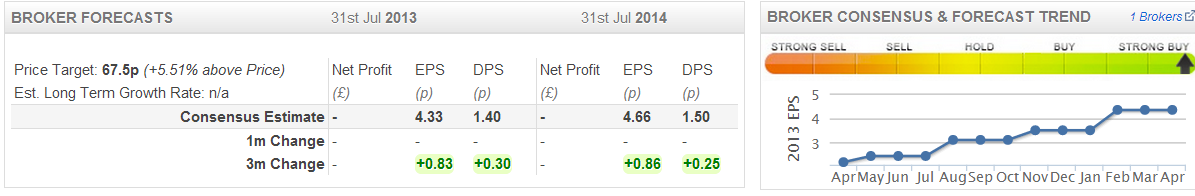
Diluted EPS is 3.328p, so if we double that (assuming no seasonality from H1 to H2) then it's about 6.7p annualised, so a PER just under 10. Looks pretty good value, if those sort of figures are sustainable (or better still can be beaten in future). That seems to be a long way ahead of broker forecasts for this year:
The interim dividend has been doubled to 0.4p, although that's only 0.6% yield for the interim dividend, plus whatever the final dividend will be on top. So not exciting for yield, but it's growing.
The balance sheet also looks pretty good. Gross cash of £5.6m contains an element of advance payments from customers, although I can't see a breakdown of that, but it will be part of the £3.7m trade payables figure (it's called deferred income, where customers have paid up-front, so should be netted off against cash to arrive at a cash balance which is the company's own funds).
The outlook statement sounds pretty positive too, but with a word of caution about full year results being dependent on "finalising a number of deals". So overall, I can see justification for the price being perhaps 20-30% higher on the back of these figures. Looks as interesting niche company with high profit margins, and such pricing power can go hand in hand with growth, as it means the product/service is in demand.
Post 8 a.m. comments
Shares in Driver (LON:DRV) are strongly up this morning on the back of a positive trading update. I am not familiar with this company, which seems to be a specialised global construction consultancy. Their historic growth figures are very impressive. They indicate the company will exceed management expectations for this year (ending 30 Sep 2013). Could be worth a look.
Interactive gambling company, NetPlay TV (LON:NPT) has had a somewhat erratic performance in the past, but seems to be firing on all cylinders at the moment. Their trading update today shows strong growth in Q1, with mobile & tablet being the "star performers". Having just bought myself an iPad, I can fully appreciate why tablets are such a growth area, so from now on when researching consumer-facing companies, I shall be searching for their iPad/iPhone App and judging them partly on how good or bad it is.
Interesting to note that Netplay say they are "confident of meeting full year market expectations", which is a bold statement to make only 4 months into your financial year, so that probably means they are likely to exceed the 1.13p broker consensus forecast. At 18p the shares look fully valued to me for now, and I don't really like investing in the gambling sector anyway.
I've been highly critical of the misleading accounting treatment for their pension deficit used by Nationwide Accident Repair Services (LON:NARS) in the past, which in my opinion resulted in a material mis-statement of the company's financial position on the balance sheet. Incredibly, the old rules on accounting for pension deficits allowed them to hide an unfunded pension fund deficit of £26.1m off balance sheet altogether, and instead they reported a fictitious pension asset of £11.4m! It just beggars belief that the auditors signed off accounts which therefore materially overstated net assets by an amount which was similar to the company's entire market cap!!
Anyway, these disgraceful accounting rules have been changed, and NARS now have to report the true position on their balance sheet, and sure enough net assets have dropped from £26m to just £697k. Bit of a difference! Strip out goodwill, and net assets becomes negative to the tune of ££5.6m.
I don't think I could bring myself to invest in a company which reported such misleading accounts in the past, even if it was within the existing rules at the time, someone should have stopped and said, "this just isn't right", to report an £11.4m asset which didn't exist, and to hide a huge pension deficit (although it was reported in the notes to their accounts, but many people don't read those, and just look at the headline figures).
Anyway, turning to the figures reported today, for the year ended 31 Dec 2012, NARS saw LFL turnover down 3%, due to a reduction in insurance repair work (they operate car repair centres). However, underlying operating profit was resilient, and actually rose to £6.8m.
The final dividend of 3.6p was maintained, giving a full year dividend of 5.5p, which gives a pretty spectacular 8.5% yield at this morning's 65p mid-price. However, there must be a high risk of the dividend being cut, as the high dividend (costing £2.4m), and funding the pension deficit (£2.6m p.a.), uses up all of the business's post-tax profits, by my calculations.
So I think buying the shares purely for the dividends is a bit risky, as it could back-fire, and a dividend cut would probably knock an instant 20-30% off the share price. Not worth the risk in my opinion.
Regulars will know that I view property REIT Newriver Retail (LON:NRR) positively. They own secondary retail space, and hence stock market sentiment is pretty down on them. However, their strategy of targeting value-orientated tenants such as Poundland, Primark, etc, is good. Plus they actively manage their properties to create letting opportunities, which is a sign of good management. I know this area quite well, having been a former retailer FD, so know it more from the tenants side of things.
Their portfolio update today is very impressive, in terms of the many actions taken to drive value from their portfolio. I don't yet have any shares in NRR, but it's high on my watch list, and might buy a few at some point.
New River's main attraction is the 8.3% dividend yield, which pays out all earnings effectively. But there is also longer term portfolio appreciation potential. Whilst rents are under pressure now, the inevitable outcome of QE is higher inflation at some point, so with a (say) 10 year view, rents will be dragged up by inflation in my opinion. So having a high yielding, and well managed REIT in commercial property is probably a good thing for a very long term portfolio such as a pension fund, and should provide a nice degree of inflation protection.
Right that's me done for today. There are some other results out today, but nothing which caught my eye. As usual, if there's something which I've missed, which fits the value investing small cap approach of this column, then do feel free to add your own summary in the comments section below. We like comments, it's good to make it interactive.
Regards, Paul.
(of the companies mentioned today, Paul has no long or short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

12 comments
Any thoughts on the bounce over the last 2 days back to £6 from £5? Quite a few £25k buys at £5.90
For any Stockopedia members tuning into LOQ for the first time I have been a very long term holder and probably well placed to explain where the likely significant growth over the next couple of years is going to come from when compared to the year just ended.
Firstly there is the fact that 2012 was not a good year for weather helping the company....Last year Lo-Q’s revenue was up 18% despite a very wet UK and a very hot US holiday season. Like-for-like sales were up 12.6%. Imagine if the weather had been more supportive to higher attendances at the parks.
Secondly the company signed a partnership with Sanderson in the Far East that should be delivering some new contracts in that region quite soon and certainly during 2013.
Thirdly the accesso deal looks to be a masterstroke not just for the two businesses being stronger as one but also due to the cross selling potential and great management team that has been acquired. They will help accesso deliver growth to LOQ in revenues and earnings in 2013.
Fourthly so far in 2013 the dollar strength has worked very well in favour of LOQs 90% overseas dollar earnings. That movement so far, if it holds and certainly could be significantly hedged at this point by management if desired, would increase flat 2013 earnings by about 10% when converted.
Finally the company has stated that year two and three in new parks see very significantly increased use of the products and repeat business that means all the new parks signed up in 2011 and 2012 will deliver VERY significant growth in 2013.
I certainly look forward to 2013 and expect very good newsflow and upgrades to forecasts to be likely if the above factors play out as I expect.
David
WHI Ireland have upped the EPS forecasts for GTC from 4.22p to 4.59p for the current year and from 4.66p 4.95p for next year.
I agree its unlikely that LOQ will ever pick up any business from Disney but just wanted to highlight:
- the huge potential market LOQ have to sell into and
- the fact that no significant competition has materialised
What I get rather frustrated about is the way that every positive RNS from LOQ is being used to justify giving it a good kicking here, whereas weak RNSes from companies such as Vianet are used to justify the suggestion that they become long-term holds.
Hi Shanklin,
I'm not kicking LOQ at all, and if you check back at my comments I think they've been pretty balanced, mentioning positive RNSs, and often saying what a good company it is, etc.
What I have repeatedly questioned is the VALUATION, because based on existing forecasts it looks far too high to me. And even then I've pointed out that if the bulls are right, and results exceed forecasts, then that would justify the valuation.
Companies on very high ratings are priced to perfection, and hence should attract closer scrutiny. Whereas companies (like Vianet, which you mentioned) on bombed out valuations due to under-performance, can become more attractive as they fall, because the dividend yield increases to a very attractive level.
As you can see from my Equity Active report on the VNET profits warning, I didn't pull any punches at all & was highly critical of management!
I appreciate though when you're long of a stock, it's not pleasant to listen to an opposing point of view, but there are many times in the past where I wished I had, as the exuberance of a hugely profitable investment can very easily make one see things through rose tinted spectacles.
Cheers, Paul.
Hi Paul
It will be interesting to see how this plays out. Currently, LOQ appears to have no competition wrt its queuing products and is winning new business at a reasonable rate.
Like many I see the market forecasts as far too low albeit the company's profitability is sometimes adversely affected by the costs associated with the first year of newly won business.
I am sure I read somewhere a statement by Tom Burnett, the LOQ CEO, that if Walt Disney adopted LOQ products they (WD) would make an extra $250M - $300M per annum, which does suggest to me that LOQ is massively under-valued by the market. As and when I find this quote I will post details here.
Best wishes, Martin
Fair point re. Disney but is there evidence that Disney may do so?
At the last meeting I saw LOQ present Tom explicitly stated he thought they had zero chance of ever getting any business from Disney as they like to do everything in house.
I do think that LOQ have strong switching costs for their existing theme park contracts and that business looks fairly wrapped up to me but like Paul I don't really buy the other queuing ideas so much (but could well be proved wrong) and the current price basically assumes everything goes too well for my liking.
Hi Paul
So you disagree with LOQ's stance that their patents provide strong protection from competitors?
Have you any evidence to support this suggestion?
Cheers, Martin
Hi Martin,
Patents usually just protect a certain method of doing something, but very rarely a whole concept.
Plus they are very expensive & difficult to protect.
So I would not personally place any reliance on the assertion that LOQ can block anyone else from developing a smartphone App to do virtual queuing.
Cheers, Paul.
Paul - I've been reading Robert Haugen's most excellent little book "The New Finance" in which he expounds on the fact that most growth estimates are far too optimistic. Mean reversion is a very powerful force - any competitor looking at LOQ right now must be thinking - wow those ROCE /ROE numbers / growth figures are great - there's money here. The world turns and shifts its resources to compete with the successful. Will LOQ still have such great numbers in a few years? Does it have a sustainable competitive advantage? Does it have an economic moat?
LOQ was David Stredder's standout pick in 2009 - it's made shareholders a tonne of money since then. I agree with you that the valuation looks to have priced perfection in - at these levels you'd have to have great conviction as a buyer - I can't see a margin of safety at this price.
Hi Ed,
Interesting thoughts.
Another point is that the markets assume growth to be steady & predictable, whereas in my experience for smaller companies, it more often tends to be quite erratic - i.e. rather than steady 20% profits growth p.a., you get a zig-zag upwards, with profits suddenly shooting up say 60% one year, then maybe 10% the next year. So I like to find good companies that have disappointed in the short term, but will out-perform in the long term (easier said than done!)
That's especially the case with operationally geared companies such as software companies, where the product is very high gross margin, but the overheads are fixed. Most overheads are salaries in that type of company, and it's difficult to adjust those in the short term. So management tend to have to estimate what their likely sales will be, put in place a fixed overhead to achieve that, but then can be wrong-footed towards the end of the year if a few sales contracts are not closed in time. Clever customers can also delay deals until year end, and squeeze out a big discount as they know the vendor is desperate to meet year-end figures.
The good thing with Lo-Q is that their revenues are recurring, although the bad thing is that they are volume dependent, and hence bad weather over the short summer trading period when most water parks operate, can whack their numbers hard.
I can see the niche for Lo-Q in water parks, and they seem to be executing in that niche very well. But I'm less convinced that Lo-Q have much of a moat in other areas, where a smartphone App can be provided by anyone. As you say, if you become very successful in a niche, that draws in competition eventually.
Also, I don't buy LOQ's CEO's claim that queues are everywhere. In reality, long queues that need a virtual queuing system are only needed in a very few places, such as theme parks, or Benefits offices (who use a paper-based system perfectly happily). So I don't believe that any smartphone system will be used at rail stations, or post offices, or anywhere else for that matter, Theme Parks are very much a unique case as they are closed environments. I think that's just hype. Same with Doctors surgeries, etc - they want you physically there, not milling around outside when the Doctor is ready to see you!
That said, if LOQ carry on picking up more theme park contracts, then earnings should gradually grow into the valuation. But I cannot see 100% upside with a 1-2 year view on the share price from here in a reasonable scenario, which is usually my key criteria for investing. Although obviously the shares have done amazingly well historically - but that means nothing. It's all about what the price does from today that should drive whether to buy more, hold, or sell.
The bulls are VERY bullish on it though, and are smart people who have done their research! But I cannot help thinking there is also a fair bit of euphoria in there too at the moment. Happy to be proved wrong though!
Cheers, Paul.