Small Cap Value Report (1 Apr 2015) - RGD, GLOK, WIN, QPP, NARS, AXS, LTHM

Good morning! I've been racking my brains to come up with an elaborate, RNS-related April Fools, but can't think of anything sufficiently funny, so will have to pass on that opportunity until next year. Although I would have assumed that Rob Terry buying 7% of Daniel Stewart was an April Fool, if the news had been issued today instead of yesterday!
I had a second wind last night, and added some more company sections to yesterday's report, so the full report is here.
Real Good Food (LON:RGD)
Share price: 36p (down 16.7% today)
No. shares: 69.6m
Market Cap: £25.1m
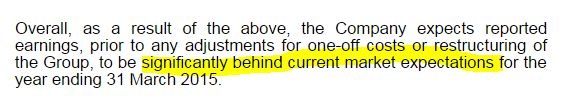
Profit warning - the company has issued a trading update the day after its 31 Mar 2015 year end. It's quite a bad profit warning too, so I'm surprised the shares haven't gone a lot lower - a 16.7% fall seems mild considering;
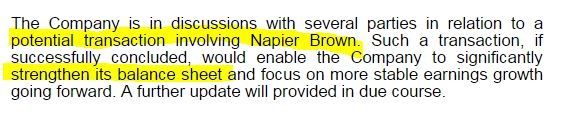
The largest subsidiary, Napier Brown, which represented just over 60% of group turnover for the last interim accounts, is up for sale;
My opinion - regulars might recall that this is one of my least favourite companies - it has everything I try to avoid - high debt, pension deficit, low margins, supplying supermarkets, it's capital intensive, has a legal dispute, subject to volatile raw materials prices, doesn't pay divis, etc. It's a complete mystery to me why anyone would want to own these shares.
Putting its biggest division up for sale suggests to me that the bank might be getting jittery & want to reduce their exposure, perhaps? Although a smaller, but less indebted group, would make a less unattractive investment proposition, so I shall await developments. In the meantime, I'm putting it on my bargepole list, as it's too high risk to consider as investable, in my opinion.
Global Lock Safety International Co (LON:GLOK)
Suspension - Allenby Capital has resigned (so things must be really bad!) as NOMAD to this tiny Chinese AIM-listed stock. So the company has one month to find another NOMAD, otherwise its listing will be cancelled. Let's hope they are unsuccessful in that endeavour, as waving goodbye to Chinese AIM stocks is something that should very much be celebrated.
Wincanton (LON:WIN)
Share price: 157.5p
No. shares: 121.7m
Market Cap: £191.7m
Trading update - there is a brief statement today, saying the company continues to trade in line with expectations.
Caveat emptor here, as this company has one of the worst balance sheets I've ever seen, hence this share is also on my bargepole list. The upward price momentum seemed to run out of steam at about 175p, and it's come off about 20p from the peak, for no apparent reason. I wonder if a Placing is on the cards?
They need to fix their balance sheet anyway, so until that is done I wouldn't consider this share as investable - it's far too risky. Just because banks are docile at the moment, doesn't mean that will always remain the case - especially when interest rates begin rising.
Quindell (LON:QPP)
Share price: 135.4p
No. shares: 440.9m
Market Cap: £597.0m
(at the time of writing I hold a long position in this share)
Disposal of division - Quindell shares are currently suspended, on publication of a circular concerning the disposal of its Personal Services Division to Australian lawyers, Slater + Gordon (who you might recognise from TV ads running at the moment).
Today's circular (link above) gives more detail on the proposed disposal (which has to be authorised by QPP shareholders, which should just be a formality) which was announced in an RNS two days ago. I can't see anything new of any major significance in today's circular, which I've just finished reading.
Key terms are;
- Quindell will receive £637m cash proceeds on completion
- deferred cash for 50% of the net profits from settlement of NIHL (hearing loss) claims over the next two years
- Quindell intends returning c.£500m (113p per share) to shareholders, with further distributions possible
- The smaller group will continue with a focus on insurance-related technology activities (e.g. telematics)
- £50m proceeds will be held back in escrow for 18 months, to settle any disputes
My opinion - I am absolutely staggered that this deal is going ahead, and that SGH are willing to pay such a high price for a business that is on its knees. I got this completely wrong, as I didn't think there was any chance this deal would happen, but it is. SGH has very highly rated shares in Australia, and apparently its shareholders are pushing it to grow aggressively, so it has raised fresh cash from its shareholders to go ahead with this deal.
There was a very interesting presentation pack on SGH's own website giving its rationale for the deal, click here to view that. What I find most interesting, is slide 21, where SGH restates Quindell's 2014 earnings using SGH's more conservative accounting treatment, and this has the result of reducing 2014 EBITDA from £289m to just £70m! So in other words, SGH is saying that almost 76% of Quindell's 2014 profits are bogus! So this very much supports the bear case, which has been based on the theory that Quindell wildly overstated its profits. That has now been shown to be correct.
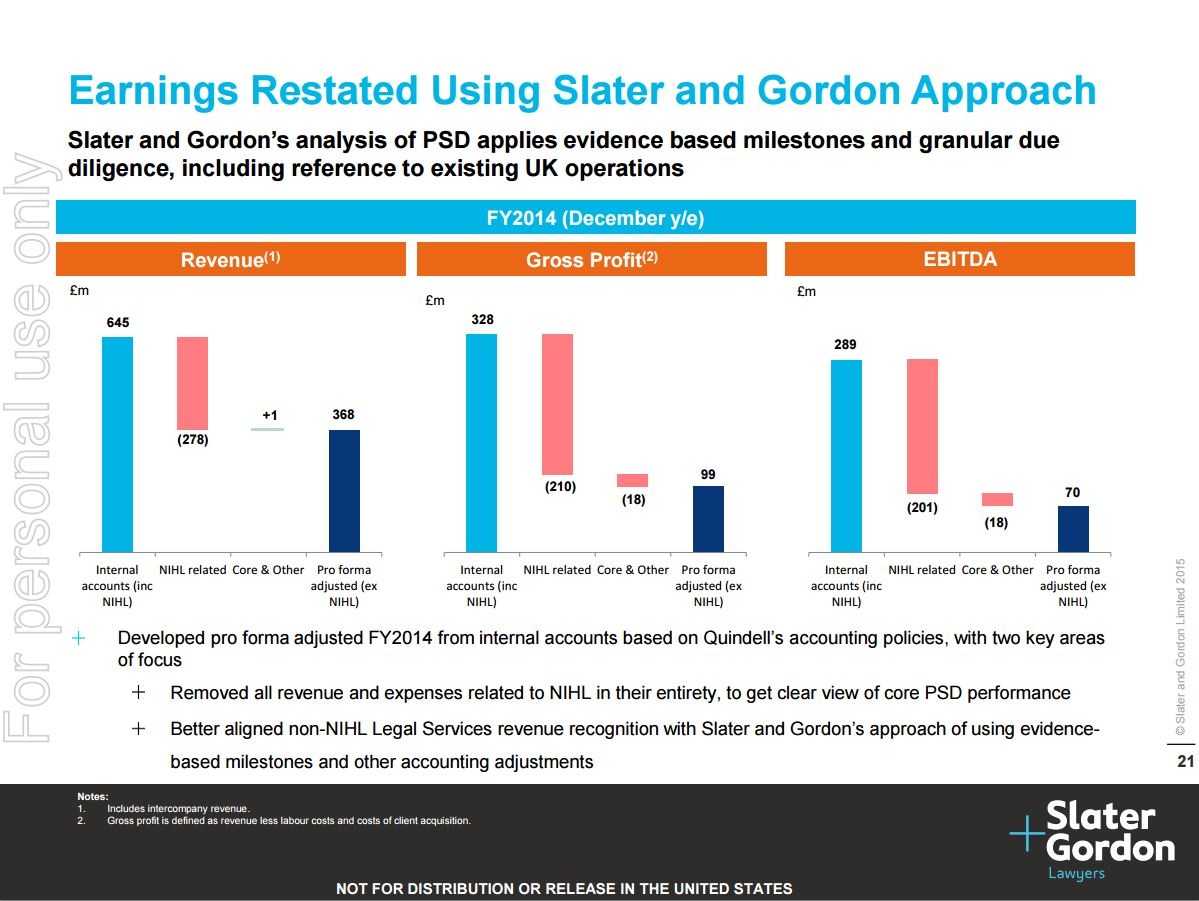
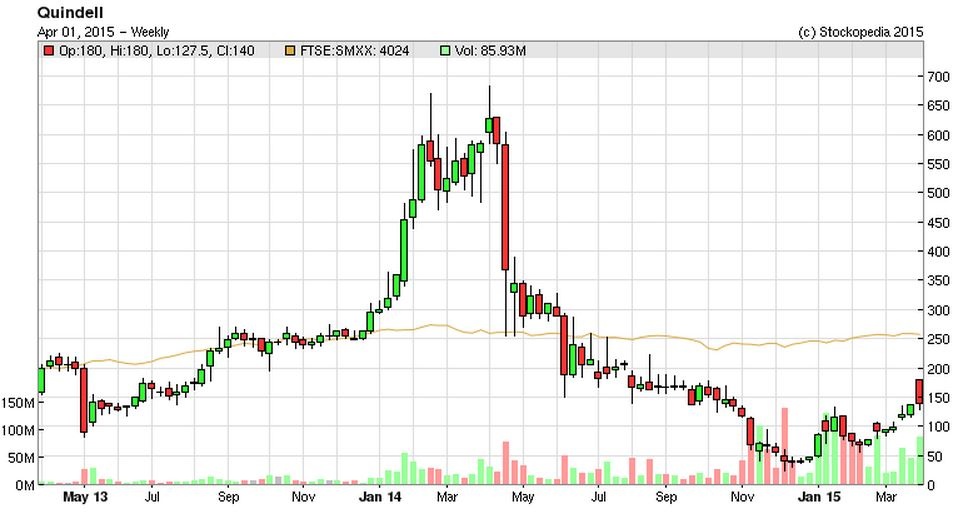
However, what some bears got wrong, was that there was considerable value in the business, even after the accounts have been corrected to a more conservative basis. That said, with the shares currently at just over 135p, they are down almost 80% from the peak of 656p about a year ago, so the bear case has been proven more right than wrong.
The eagle eyed amongst you might have noticed that I disclosed a long position in this share at the top of this section. Have I taken leave of my senses?! Not really. It looks as if this deal will go ahead, and the company intends paying a distribution to shareholders of c.113p per share (£500m). So at 135p that makes the shares about 84% backed by just the first distribution (depending on the tax treatment of the distribution, but I hold these shares in a tax-exempt account, so am not worried about that).
What is the balance worth? Who knows, but after the £50m escrow monies are released, there could be scope for another distribution of say 10-20p. Plus there will be some potentially interesting technology businesses left behind. Estimates of what they are worth vary wildly, and in all honesty, I don't have much of an idea on that.
It's not a high conviction hold for me at this level, but I like that the downside should now be underpinned by cash, so any possible upside looks to be in for free.
Note in the circular today, it says that if the deal were not to go ahead, then QPP would need to raise more funding, and that the PSD would take two years to reach an acceptable level of cashflow generation. That's really shocking, and makes it all the more perplexing why SGH have been so generous in their offer. Hats off to the QPP negotiation team, who've pulled off a blinder here!
The way I look at it, the bears have been mostly proven correct about this company, but under-estimated the potential value in the shares once the dust had settled. The bulls have, in my view, been very lucky, at being thrown a gold-plated Get Out of Jail Free card by Slater & Gordon. Without the SGH offer, the outcome could have been very much worse - an emergency fundraising at pence, and massive dilution for existing holders. Which probably explains why the founder, Rob Terry, was so keen to dump his stock as low as c.40p late last year.
Anyway, a fascinating situation which now appears to be drawing to a conclusion. The big lesson to be learned here I think is, if the accounts don't look right, that's probably because they aren't right! Also that aggressively hyped companies which grow at breakneck speed through multiple acquisitions, nearly always fall apart. Oh, and the most important lesson of all - cash is king - if a company is incapable of generating positive cashflow, then sooner or later it's going to run out of money.
There were so many red flags with this company, that it was obvious the wheels were going to come off at some point. The move into NIHL cases was the real killer, as that turned a poor cashflow business into a disastrous cashflow business, and of course they then ran out of cash in late 2014, hence ending up in the current situation. Thank goodness SGH came along as a white knight, and saved the day.
Nationwide Accident Repair Services (LON:NARS)
Takeover bid - there's a 100p cash bid for this chain of car repair centres. The bidder is asset manager Carlyle Group. This looks a fairly good deal for shareholders, at a reasonable premium price, and it looks a done deal, with 60.6% of shareholders having already agreed.
I am surprised at this bid, because the company has a big pension deficit, which I had thought normally acts as an impediment to such a deal. So it would be interesting to find out how this issue was dealt with here, as that might mean other bids could appear for companies with pension deficits.
Accsys Technologies (LON:AXS)
(at the time of writing I hold a long position in this share)
Update - a positive-sounding update today, which says that the company has replaced its JV partner with a "large international chemical group", with which it has signed a memorandum of understanding, with full agreements likely to follow later in 2015.
The aim is to get a production plant up and running by end 2017, to increase supply of its Tricoya wood product. Sales grew 70% in 2014.
In my view this looks a very interesting growth company, which has a product that is clearly in demand. Producing it in sufficient quantity has been the problem so far, but it sounds as if progress is being made to resolve future supply.
My track record on more speculative stocks has been fairly poor lately, so let's hope this might be one that works out a bit better! I went long about 60p a few months ago, and so far so good (30% up at 78p).
Although it is still currently loss-making, and the £69m market cap may not look an obvious bargain, but you're paying up-front for some of the future potential.
James Latham (LON:LTHM)
(at the time of writing, I hold a long position in this share)
Trading update - this sounds OK, but suggests margins might have come under pressure, or maybe some additional costs? The main thing though is that profits are in line.
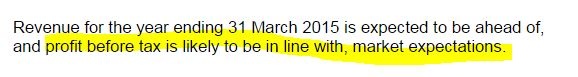
Valuation - EPS is forecast to dip slightly to 39.5p, so that puts it on a PER of 15.4, which sounds about right to me.
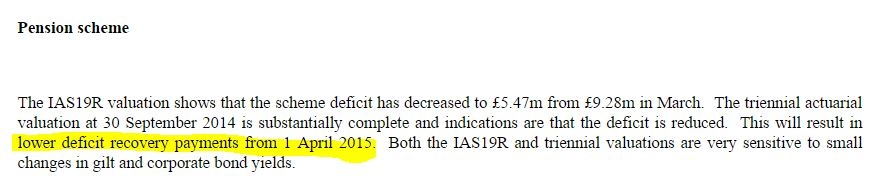
Pernsion deficit - an update is given on this, and is very surprising. The 2014 actuarial valuation has come down sharply, from £9.0m in 2011, to only £1.5m now. I can't understand that at all, since pension deficits are generally shooting up at the moment, not down.
A deficit recovery payment of £1,155k is being paid for y/e 31 Mar 2015, dropping to just £420k the following year. So it looks as if the pension scheme will then be fully funded, which is great news, if I've understood this correctly.
Checking back, I see the company said this about its pension deficit with its interim results published on 27 Nov 2014, which confirms that this issue has been largely resolved. That's great for shareholders, as it opens the door to potentially good increases in future divis.
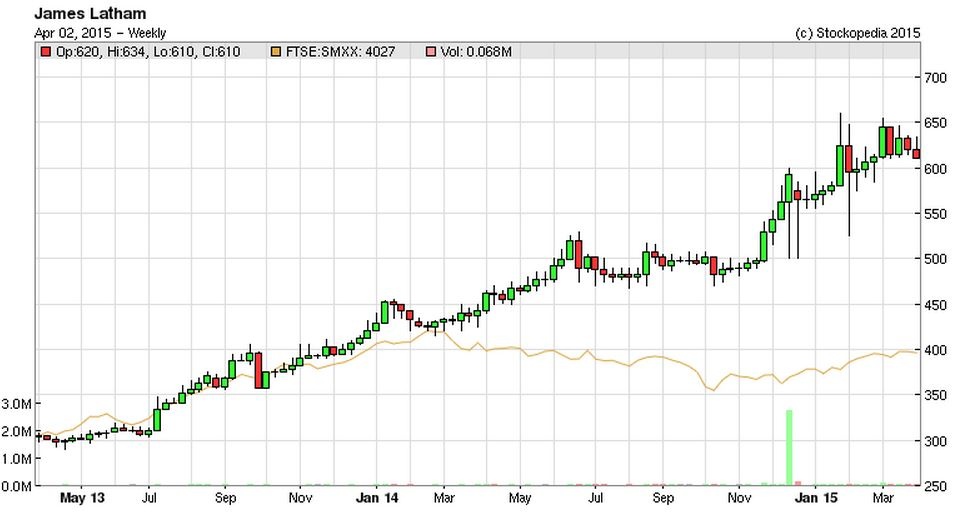
My opinion - whilst the PER may now look up with events at 15.4, personally I am not inclined to sell my shares, because the macro backdrop (esp. housebuilding) is very positive for a wood supplier like Latham. So I am hoping for decent increases in future earnings.
Also, bear in mind that this company has a terrific balance sheet, so there are surplus assets thrown in for free, which always gives me a warm glow. The current ratio is 2.90 for example, and I reckon surplus working capital is probably worth around 25% of the market cap, giving management scope to do acquisitions or make a capital return to shareholders at some point. So hidden upside potential in for free basically.
Stockopedia's algorithms like it too, as the StockRank is 99.
All done for today.
Regards, Paul.
(as mentioned above, Paul has long positions in QPP, AXS, LTHM, and has no short positions in the companies mentioned today. A fund management company with which Paul is associated may also hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

16 comments
Hi Ed
" I would though stress that most people are thinking about the StockRanks in the wrong way - they are fixating on the StockRanks of individual stocks rather than thinking about them across baskets of stocks "
If that is the case, I would suggest that you are simply making this misconception worse by showing the StockRank at the top right hand corner of every stock's Stock Report page. It is natural for a reader to make this 1:1 connection.
There was a debate about this a few weeks ago but I don't think anything changed as a result. FWIW, I wholeheartedly agree with dasv's comments:
Dear Ed, Please change value rank to mark down co's with negative books at least. It would be nice if it factored in zero divis too.
WIN - dasv's comments on the methodology of calculating the Value Rank are absolutely logical.
I, for one, will view the Value Ranks with suspicion until his comments are taken on board.
Unfortunately,this suspiscion will obviously flow over into the combined Stock Rank, which hitherto
has benn a key metric to me
We've had a lot of debates over the Value Rank and I appreciate everyone's input and feedback on its composition. We take an academic line here, but I do appreciate this may not be to everyone's taste - it has though been highly effective.
We've done the calculations mentioned on Wincanton, and including the -ve BV in the P/B factor would only drop the overall StockRank down to about 95 rather than 98. I'm sure that plenty would still be rubbed raw by that ranking - but that's the nature of statistical methods. Wincanton did return about 150% from the date it first entered the 90+ StockRank bucket, so I don't think this point case is a reason to apologise for our methodologies.
There's certainly an argument to calculate all our inputs (P/E, P/B etc) as yields as we do for the earnings yield so that -ve values are (perhaps) better accounted for - and this is something we are assessing. I would though stress that most people are thinking about the StockRanks in the wrong way - they are fixating on the StockRanks of individual stocks rather than thinking about them across baskets of stocks. I've written extensively on this key point and I stress for everyone to read up again in this article. The StockRanks are not about individual point-cases... they are about portfolios - these are not stock specific ratings
The ValueRank has worked extremely well to date, is based on very robust literature, and if history holds (and the value anomaly persists) baskets of 'cheap' stocks can be expected to continue to outperform over the long term. Here's the annual performance of the ValueRank for £10m market cap companies across deciles since launch in the UK.
Here's the ValueRank performance across the entire EU with the same criteria:
Cheap, by our methodology, has beaten expensive hands down. We can tweak the formula, but I don't necessarily expect a better output.
(In fact - there's plenty of academic evidence that -ve book value stocks actually outperform... so I do want empirical proof of upside before we tweak what is clearly a working model ! )
Have you thought about trying alternative presentations to nudge people into understanding the ranking nature of the stock rank? It's very natural to interpret the current system as an absolute metric.
For instance, just inverting the scale and showing it as a percentile (1=first percentile/best stock, 100=last percentile/worst stock) may already help...
Or maybe a ratio of worse:better -- e.g. 1:1 is the median, with an equal number of better and worse stocks, 10:1 the one on the first decile boundary, etc.
Someone posted an April fool about QPP's suspension being extended to the 17th. Made me laugh anyway.
Hi Paul
I think you mentioned on twitter that you were going to review INL's latest results.Is that still the case?
Hi cojode,
I had a quick look at results from Inland Homes (LON:INL) but didn't feel I could add any value, as it's a tricky one to evaluate - you can't really value housebuilders on a PER basis, because they are making artificially high profits at the moment, arguably. So valuing on a build-out basis is probably the best way (discounting future net earnings on to existing NAV).
Also, INL has some off balance sheet assets.
So I reckon it's probably best to just get hold of the latest broker note and let them do the work for me! I took my profits on Inland a few weeks ago, and no current plans to revisit.
Regards, Paul.
it seems there was some mistake in the circular. I would guess a big one if they just cant issue a correction.
http://www.telegraph.co.uk/finance/markets/11508613/Quindell-shares-suspended-after-error-found-in-deal-announcement.html
Maybe this soap opera has been commisioned for another series!
Hi,
A fresh statement has just out from Quindell (LON:QPP) - correcting some relatively unimportant errors in the earlier circular.
Points to note;
- £500m distribution will be done in a tax efficient way (good),
- the businesses being retained made an £8.5m profit in H1 of 2014 (good).
So overall, I think this is fine, panic over! I'll read it again, just to be sure.
Shares will resume trading at 3:45pm today.
Regards, Paul.
Paul
Thanks for adding the comments yesterday about Christie (LON:CTG). Very interesting and gives me food for thought. It has done very well for me over the past 3 years and I have taken some profits but maybe it is time to take some more.
Regards
Michael
WIN - I mentioned this on Twitter to Ed Croft but it seems bizarre to me that WIN should still command a 97 for its value stockrank with a negative book value per share of -220p (negative).
Value rank is calculated by averaging the following but ignores negatives, and nulls/zeros:-
•Price to Book Value
•Price to Earnings
•Price to Free Cash Flow
•Dividend Yield %
•Price to Sales
•Earnings Yield %
So WIN's Negative Book value is ignored as is its non existent dividend yield.
Dear Ed, Please change value rank to mark down co's with negative books at least. It would be nice if it factored in zero divis too.
Hi Paul,
I think we are all dying to know your thoughts on the other suspension today. Any chance you have closed your short and can comment?
Appreciated as always
P.S Anyone know why is the Company name is shown as AIM (anything other than a typo)
Hi Thegrimester,
I wasn't intending on commenting on Quindell (LON:QPP) but you gave me a nudge, and I thought why not? I'm no longer short, so am free to comment on it. See the new section above.
Regards, Paul.
Just wow.. thanks Paul.
but what about todays suspension. Do you think the deal is still going ahead?
Hi Thegrimester,
but what about todays suspension. Do you think the deal is still going ahead?
I assume the deal at Quindell (LON:QPP) is still going ahead, SGH seem committed to it.
The suspension announcement today says the shares have been "temporarily suspended on AIM pending an announcement and publication of a document", and QPP has published the circular on its website, so I just assumed that was what it is referring to.
Seems odd that the shares are still suspended though, I would have expected them to have come back by now.
Regards, Paul.