Small Cap Value Report (1 Dec 2014) - PRV, ACSO, BON

Good evening. I'm back from Vegas now, but the overnight flight meant that I was too jet-lagged to be able to write a coherent report earlier today. We don't want any gaps in the series, so I'm catching up this evening having had a long afternoon nap!
Oil
I'm always looking for bargains, and it strikes me that the extraordinary collapse in the price of oil might be starting to throw up some buying opportunities? So I'll be suspending my usual rule of not looking at any resource stocks, and might consider the odd one - but only if the investing case is compelling, and low risk - so producers, with cash on the Balance Sheet, will be my starting point. One has to assume that most of the cash-strapped junior explorers are not worth even glancing at.
Lower energy costs will certainly help in particular the US consumer, as they are heavy users of oil for heating & in vehicles, which is taxed lightly compared with Europe - so the benefit of the big drop in oil price is already putting more disposable income into consumer pockets in the US. I might start looking at some US stocks when time permits. Amongst all those thousands of stocks, there must be some undiscovered bargain small caps!
Historically the US economy has always boomed on the back of cheap energy, so it probably will do again. Maybe the apparently expensive US stock market isn't so wildly priced, given the upside on economic growth, on what is still the world's biggest & most entrepreneurial economy?
I did some reading on holiday, and one phrase which stuck in my mind from some investing guru (can't remember which) is that when a share, or a market as a whole, breaks into new highs, then you have to stop and consider that something significant has changed - and that betting against such a move could prove a mistake. On the other hand this is something like the 3rd longest bull market in history, so it must be nearer the end than the beginning?
So lots to ponder. I'm mainly a bottom up stock picker, but it also makes sense to monitor big macroeconomic themes & trends, and at least have a rough idea of where we are in the business cycle, and invest accordingly.
Porvair (LON:PRV)
Share price: 267p
No. shares: 44.2m
Market Cap: £118.0m
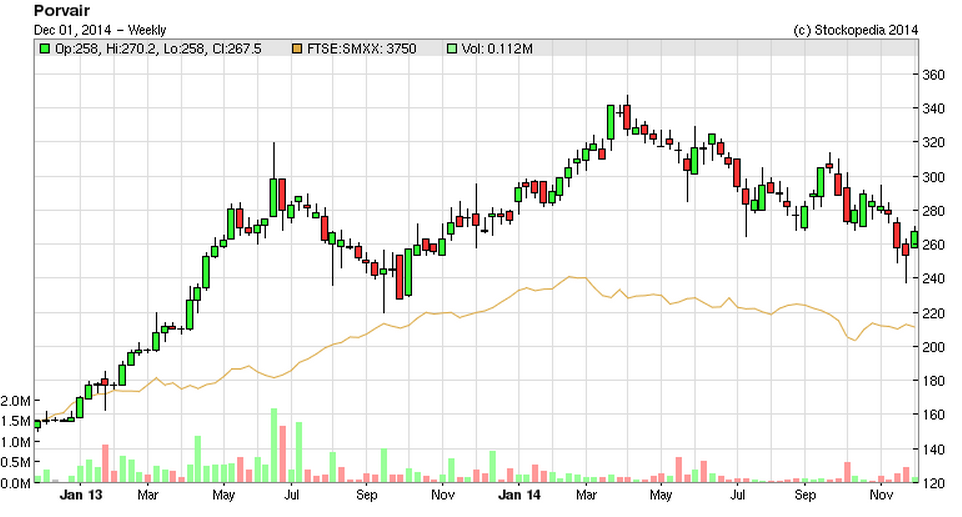
This company is a maker of specialist filters. I've had my eye on it for a couple of years, but the price has looked toppy for some time now.
Trading update - for the year ending 30 Nov 2014 looks good to me;
Porvair has continued to trade strongly throughout the year. Both divisions are expected to deliver record results, with revenue for the full year up 24% (28% at constant exchange rates) and earnings marginally ahead of current market expectations.
Strong operating cash flow has increased net cash at the year end to around £5m, achieved after capital investments of £5m, mostly spent on expanding manufacturing capacity to meet demand.
Valuation - broker consensus is for 13.7p EPS for y/e 30 Nov 2014. Therefore the PER is 19.5 times. That would be justified if big increases in EPS were likely to continue, but the 2014/15 EPS forecasts are for only a modest increase in EPS to 14.6p, which would become a PER of 18.3.
Outlook - the order book is described as "healthy", and the company sees a "promising pipeline".
My opinion - the fly in the ointment for me is that the company reiterates that 2014 has benefited from some large one-off orders. That's been mentioned before, but it's material, at £20m turnover (out of around £104.5m total). So if those large orders are not repeated, then maybe turnover & profit could fall in 2015? That seems a considerable headwind to be up against, and hence increases risk from an investor point of view.
accesso Technology (LON:ACSO)
Share price: 625p
No. shares: 20.4m
Market Cap: £127.5m
Trading update - looks good. The key part of this statement says that the group expects to deliver adjusted profit and cashflow ahead of market expectations, on turnover in line with market expectations.
Valuation - Stockopedia shows broker consensus of $115.4m turnover (note the change in reporting currency to dollars) and $5.66m profit, or $0.47 EPS. That translates to a PER of 21.3, which is starting to look more sensible again, after a long period of being considerable higher, and looking stretched.
Note how broker forecasts have risen considerably in the last few months, which is clearly very positive;
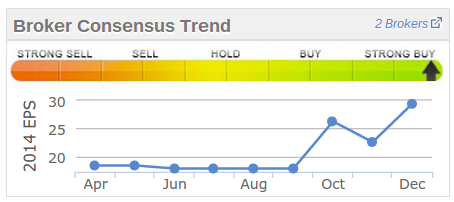
My opinion - this statement from the company saying that forecasts will now be exceeded, puts the shares on a much firmer footing.
I'll be interested to see what the adjustments to profit are though.
A cynic might also point out that a lot of the growth has been bought in through acquisitions. So the split of organic vs acquired growth will be key.
I don't see value here, but it's not looking crazily expensive any more either.
Bonmarche Holdings (LON:BON)
Share price: 264p
No. shares: 50.0m
Market Cap: £132.0m
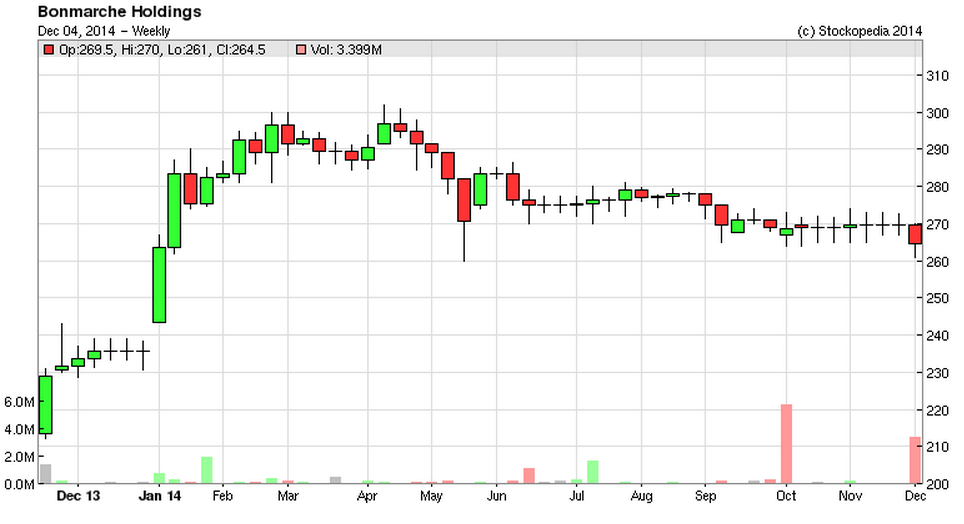
Interim results for the 26 weeks to 27 Sep 2014 look excellent at first glance. However, the headline figures are heavily flattered by one-off costs last year. So the adjusted figures show a reasonable, but much less impressive performance.
Underlying profit before tax rose 15% to £6.4m. Underlying EPS was up 1.2p to 9.9p.
The company has been hurt by unseasonal weather in Sep 2014 (as reported by other clothing retailers too), but expects to meet full year forecasts. That's not bad going, and suggests to me that if the autumn weather had been normal, then the company would have beaten forecast.
Valuation - broker consensus is 19.3p for this year, so at 264p that puts the shares on a PER of 13.7, falling to 12.4 times next year's forecast.
Divis are alright, at 2.6% yield for this year, rising to 2.9% next year.
Balance Sheet - this looks OK to me. Retailers sell for cash, so don't have much in the way of debtors, therefore a lower current ratio is perfectly acceptable - anything over 1.0 is fine for a retailer, in my experience. The current ratio here is 1.22, and the company has negligible long term creditors, so that's fine.
Note that the company is spending a fair bit on capex, well in excess of the depreciation charge. This makes me wonder if it was starved of capex when under previous ownership? Store refits are underway, and of course that will act as a drag on cashflow and profits, as the depreciation charge increases. It's not a deal-breaker, but it's worth considering. The stores I've seen have looked a bit run-down, and are often located in rather down at heel areas - maybe not a bad thing, as the rents will be low.
My opinion - I quite like this retailer. Rather than chasing the over-supplied younger female fashion market, Bon Marche targets over 50s females, with a value range. That should be a resilient market in all economic conditions, so it has good recession protection. Also the business seems to be firing on all cylinders, delivering strong LFL sales growth. Online sales are small, but growing nicely.
I am worried about the introduction of a new EPoS system, because I've seen at first hand how badly wrong such changes can go. You can very easily lose control of the business when a new system comes in, if you lose key management information for even a short while. So personally I will sit on the sidelines until the new EPoS system is fully bedded in, and all problems ironed out. Although it is good to see that the new system is being piloted in a few stores first, to see how it works.
Overall this strikes me as quite a good company, priced about right at the moment. It would need to become a bargain at c.200p to interest me though. So it might be one I'd pick up after a profit warning, if something goes wrong in future.
Regards, Paul.
(of the companies mentioned today, Paul has no long or short positions.
A fund management firm with which Paul is associated may have positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

6 comments
Camtab, I agree, I think the Virunga issue does hang over soco somewhat, but I'm afraid I don't buy into the oh aren't soco such a terrible company. It's not soco's decision to look for oil it's the democratically elected governments decision. People having a go at soco for looking for oil is akin to people protesting against the builders who put up my extension because they object to where I'm building it. If they pulled out (as if ), I would get another contractor. There is no reason on earth that exploration cannot go hand in hand with development of the park in the way the wwf want. Infact some could share the infrastructure (communications, hospitals, roads). It might even be that there is oil there that is better extracted from the other side of the boarder in Uganda, and that by just proving it crosses over the government may be entitled to some revenues. There is a lot of nonsense talked about the whole virunga thing, and while I have my doubts about it, I'm not happy to see blatant misinformation spread about mountain gorillas and the like.
The rare mountain gorillas are 50 miles away, outside the block, in an area soco have said they'd never explore, (not least because it's a mountain I imagine).
But if you have real concerns about how it could effect the price, consider this, there are 4 outcomes
1) siesmic shows nothing worth the hassle, soco walks away,
2) siesmic shows potential soco tries to do a deal with the government and unesco,
a) no deal possible , soco walks away,
b) deal possible, explore it comes to nothing, walk away,
c) deal possible, explore , find oil,
only 2b/c have the virunga thing going on for any length of time, I don't know how long a campaign might take to organise and do, but if that came to nothing, it could well be over in the next 18 months, add 6 months trying to agree a deal with unesco re expo plans suggests in 2 years, it'd be over. the only long term virunga issue is if they find oil, now if they do, they'll have done it by doing a deal with unesco to redraw the boundaries of the park, as has been done in the past in other parks. Probably with a deal to put things back in 10 years time when they've finished, and perhaps returning the area back to national park then. Probably in the meantime a few $ per barrel extracted will be put in a fund to develop the park. Will this be such a bad thing for the park long term ? I suspect not.
option 1 or 2 a seem the most likely to me, so it's probably all over in 6 months to a year, if we get into the other options we've done it with agreement with unesco, so they will have approved the plans. It'll be harder to object then surely ??
And anna fiel, can make videos from a leafy uganda talking about this place as if she were in virunga, but the truth is that while some of virunga is while, it has a population of over a million people , mostly very poor , and isn't all the virgin forest that we see in the videos.
The congo is just virgin acreage, like other areas they've given up having found nothing.
Personally I am more worried about the medium/long term price of oil than virunga.
K
Paul,
As you know I have previously posted on your view to the macro economy and its impact on beta. Thanks for your comment above as it helps me treaty with understanding how you approach your investment.
With regards to SIA or SOCO Kenobi, I am a holder although I have been reducing. In the old sense I think it is a real opportunity, I won't go through the Stockopedia info, you can do that yourself. However and this is a big BUT, I really do think there is a change going on with regard to capitalism (I am a capitalist and I love making money), people are expecting to see a more social capitalism at the top level. If reports are to be believed SOCO has shown scant regard for the environment in Virunga, (see Leonardo Di Caprios film) and Hollywood can make heart rending films!! So my concern is that SOCO could start to take on an environmental discount (I know lobbyists are talking to pension schemes). My problem is I don't know how to estimate that discount and therefore valuation becomes more difficult. Also there is no clarity on whether they will be able to get the oil out of the Congo given the headwind. I hope this is helpful.
what about SOCO international ? (oil co )cash producer, divi payer, possible reserves update coming up over the next few months, and senior management looking to sell the assets at the correct point,
yearly high over 450, obviously price of oil will hit the income, other assets in africa have shown some potential, (eni's discovery in Congo seems to overlap onto soco's block , awaiting confirmation ).
have done some exploration in the virunga park which is bad pr, but if they find anything and can do a deal with unesco to redraw the boundaries of the park, could turn into something.
cheers K
K
And, how about Iomart for starters ? Not an oily but well run company with previous 2 bidders rejected. Possibly room for a third attempt before EOY results.
Paul - agree not many small oil companies fitting your bill - however Amerisur is one:
(ref.SharesMagazine)
Amerisur is active in Colombia and Paraguay where it has substantial proven reserves and also a large amount of exploration upside with varying degrees of risk and reward. In Colombia it has 1P reserves of 19.8mmbo and 2P of 32.8mmbo, with net mean resources of 235mmbo from unrisked management estimates. It would not be wrong to say that the Platanillo field is the gift that keeps on giving as the company has drilled and completed 14 new wells and 3 sidetracks in the last 27 months, all being successful. In addition to that there is an ongoing drilling campaign on Platanillo with success in the U and T sands possibly to be followed by the B and N sands where oil has already been tested and I expect the latter, a proven stratigraphic trap to add to the reserves this year. With the PUT-12 block directly to the east of Platanillo being of the same geology but five times the size of it, the company are suggesting that mapping currently indicates 200-480 mmbo of potential resource, again net unrisked management estimates. Amerisur also has a 100% WI in the Fenix block in the Middle Magdalena Basin to the North of Colombia. In Paraguay there is massive, possibly transformational potential with an extensive acreage position comprising two E&P and three Prospecting permits. You will know that I am very excited about Paraguay with my work on President , this is equally as game-changing as that may be for them.
First half of 2014 production was 6,561 bopd which is growing but limited by ‘transportation options’, effectively the company trucks crude to market through Orito,Colombia which incurs a very significant cost per barrel, now the opportunity has arisen to connect directly to the Ecuadorian pipeline system. The company can put 4,000 b/d though the link at Victor Hugo Ruales, a number that will increase significantly after a facility upgrade to over 50,000 b/d. The effect that this will have on costs for Amerisur are significant, for over 85% of the 2015 production the cost per barrel will fall from $23 to $6, a massive opportunity and the company expect to have the interconnector operating on schedule by the end of 2014.
Amerisur is in a strong position financially, first half revenues this year were $114m ($64m ‘1H 13) with cash of $96m at the moment. By international oil company standards it has a fairly modest G&A and all exploration and development is funded from cash flow and resources. The company appears to have the full hand of exploration and development with low risk reserve extensions, significant short term upside in producing acreage plus prospects in Put-12, Put-30 and in Paraguay any of which could be game changers. The forward programme is packed with a mixture of development and exploration wells, including the San Pedro well in Paraguay and of course the pipeline into Ecuador which transforms already exciting economics.
With a first class management, supportive shareholders and a portfolio that contains low, medium and high risk prospects, when the pipeline comes onstream it will be like having another discovery. For all these reasons Amerisur should be at the top of the list of stocks to own, it has always been reassuringly expensive so the recent market shake out may prove to be an opportunity not to be missed.
What do you make of the C21 statement this morning Paul?