Small Cap Value Report (1 Dec 2016) - MOS, CCT, ITQ

Good morning!
To get you started, here is yesterday's late report - where due to reader demand, I looked at interims from data company D4T4 - I think it looks worthy of a closer look. Also solid results & an upbeat outlook statement from equipment hire group VP (LON:VP.)
Turning to today - well I've had better starts to the day. Two companies in my portfolio have crapped out today - another profit warning from Interquest (LON:ITQ) (which I'll cover in more detail below), and a fundraising at a 50% discount from Mobile Streams (LON:MOS) - very much a speculative punt - through Primary Bid. This is very interesting, so I'll do a little section on it now.
Primary Bid
Some of you may have heard of this already. It's a new initiative to raise money directly from private investors for listed companies. So rather than being frozen out of the fundraising process, we can now participate.
Looking at the quality of the companies which have used this platform, we're talking about the real dregs here. However, if there's an appetite from private investors to put fresh money into highly speculative (i.e. mostly complete rubbish) companies, then arguably a platform which levels the playing field between PIs and the City, is a positive thing.
I'd much rather have the option of putting my own money into a discounted placing through Primary Bid, rather than be diluted by city insiders getting the cheap shares, and me only finding out after it's a fait accompli.
I think there's also a gap in the market for very small fundraisings, where the fees would be too small to interest any of the main brokers.
Mobile Streams (LON:MOS) - this is a tiny company (in which I hold a long position) which has previously been decently profitable (doing games on mobile phones, ad funded). However, it fell foul of the collapsing currency in Argentina, where its main operations were (still are, I think). For me, this has always been a total punt, not part of my proper portfolio as such. The main attractions were that the company had been entirely self-funding for years, and had not raised money from the market.
Sod's Law then kicked in, and the company has decided that it does want to raise cash after all, and is doing it via Primary Bid today. Anyone can just register, apply for shares at the placing price of 4p, and then pay by debit card. That's fine if you keep plenty of spare cash in your bank account, but personally I don't, so it's no good for me. I've asked my broker to apply instead though.
Setting aside the merits of MOS as an investment, which most people will (probably correctly) dismiss, what really interests me here is whether the Primary Bid platform will gain traction. If it does, and deals get bigger, and hopefully move up the value chain to more sensible companies, then I can imagine this being a very useful service for private investors. I've long thought it was unfair that PIs get blocked out of placings, and instead an elite group comprising fund managers & wealthy individuals, and mates of the broker, got discounted shares that they could flip for an instant profit.
So I like the idea of Primary Bid, and hope it works. NB. For the avoidance of doubt, I have no connection whatsoever with Primary Bid.
EDIT: I should emphasise that the £1.6m fundraising for MOS is being done in the conventional way, with N+1 Singers doing a placing, but with the Primary Bid option to allow private investors to participate as well. I really like this structure, and hope that other companies follow suit.
In the end I didn't have any spare cash to apply via Primary Bid, so I got my broker to apply for some placing shares direct with Singers. This in itself is also a positive development - i.e. announcing the accelerated book build, plus the Primary Bid option, so that everyone has fair access to the Placing. They should all be done like this, when there's a deep discount, rather than cosy backroom deals which are announced as a fait accompli.
Character (LON:CCT)
Share price: 461p (up 6.1% today)
No. shares: 21.1m
Market cap: £97.3m
Results for year ended 31 Aug 2016 - a sluggish reporting cycle - 3 months to produce the preliminary figures is not good at all, that's at least a month longer than it should take. They're not even audited yet.
The figures look really good though;
- Revenues up 22.1% to £121.0m
- Underlying PBT up 22.5% to £12.5m
- Underlying diluted EPS up 23.5% to 45.16p (PER of just over 10)
- Net cash of £6.9m
- Divis up 36.4% to 15.0p (yield of 3.3%)
Outlook - comments are a bit scattered about throughout the narrative, but sound positive. I like the comments about continued international sales expansion too.
"Strong organic growth underpins Character's continued position as the UK's leading independent toy company. Underlying pre-tax profit for the year is £12.5m up 22.5% on the previous year and current trading is commensurate with the Company achieving the Board's profit expectations for the current financial year."
Balance sheet - looks fine to me overall.
It seems a bit strange to have cash of £28.6m, whilst simultaneously running bank debt of £21.6m, so that would be a key question to ask the CFO. Surely this is inefficient re interest costs?
My opinion - shares in this toys company have generally been cheap in the past, so it's best to not get too excited about the lowish PER.
Issues have arisen from products going out of fashion. Although I'm reassured to hear that Peppa Pig (it's top seller) is still going well. Also, it's gratifying to hear that Scooby Doo is still popular - 40 years ago I rated that as top quality entertainment - especially the prosthetic face removal as the climax of nearly every episode.
It's difficult not to like this share, at the current very reasonable valuation, and with an increasingly impressive track record building up.
Interquest (LON:ITQ)
Share price: 29.5p (down 14% today)
No. shares: 37.5m
Market cap: £11.1m
(at the time of writing, I hold a long position in this share)
Trading update (profit warning) - this is an interesting one. It was blindingly obvious that the company wasn't going to meet current forecasts, because the forward PER had fallen to just 3.5. That's the market telling you that the forecasts are pie-in-the-sky.
Also, the 14% drop today is telling us that the market had already factored in further downside in forecasts. Moreover, I've been struggling to buy - so there don't seem to be any sellers in size in the market.
Why on earth would I want to buy, straight after another profit warning, and after a dismal share price fall this year? Well, because I think the valuation is now quite compellingly cheap. Also, despite poor short term performance, ITQ looks to be well-positioned, supplying labour for fast-growth markets like IT.
Specific problems - seem to be in its ECOM division. Although it has already been restructured, and is now showing some improvement in performance.
Also some contract delays;
In addition to the underperformance by ECOM, there have been lower levels of demand in the public sector compared to 2015 and a small number of large value placements have been delayed into 2017.
As a consequence the Company now expects that net fee income and EBITDA for the current financial year will be below market expectations.
Revised forecasts - the latest numbers coming through this morning suggest that adjusted profit will be £3.6m this year (down from £4.2m), and EPS 6.9p instead of 8.5p.
The market cap of just £11.1m looks ridiculous for a company that should make £3.6m, in a bad year.
Balance sheet - has a huge debtor book, partly funded by debt. The latest broker note suggests that cash generation is good at the moment - debt tends to unwind at companies like this, as business contracts. So they're saying £7.0m net debt at year end. Overall the last balance sheet looked OK to me.
My opinion - fishing for bargains at bombed out companies which have warned on profits, can often be a depressing, and unprofitable activity.
However, at this level, I think ITQ is probably at or near the lows. It's finances look alright, and the PER is now dirt cheap. Plus it's paying a divi, and even if that is reduced, is still a nice bonus.
Recruitment in the IT sector seems an activity that's not going away. Personally I think this could be a nice little recovery trade from the current price, with a target of maybe 50p - which would still only be a PER of about 7-8 times the revised forecasts put out today. Yet that would be a 67% gain from today's price. I think that's quite a good punt.
Motor dealers
This is a very bombed out sector, partly because of sterling weakness - the price of imported cars is rising as a result.
However, I note that sterling has had a quite strong partial recovery in recent days. This must be taking some of the pressure off manufacturers to raise their UK prices.
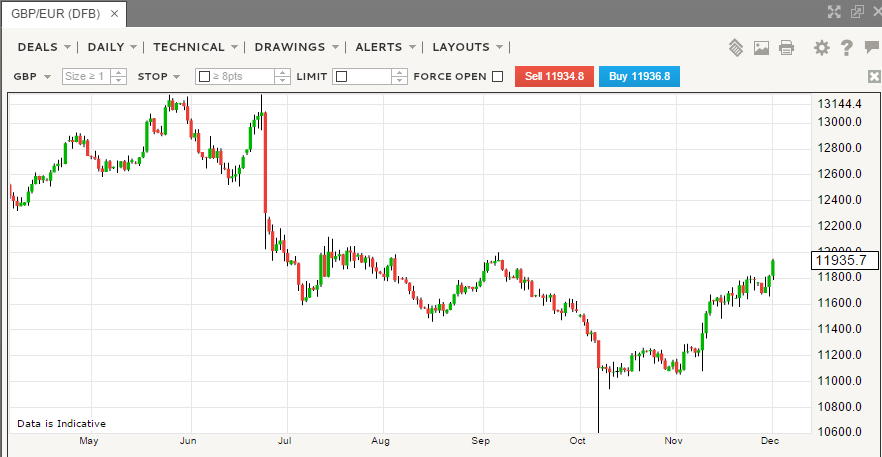
(chart courtesy of IG)
Bear in mind also that it's secondhand cars sales, and after-sales (servicing, warranty work, etc) where dealers make most of their profits.
So I'm thinking about adding to some of my positions in this sector. It looks far too cheap, even allowing for the fact that new car sales are slowing somewhat. Dealers make very little margin on new cars sales anyway.
This might also help airlines & holiday companies - those European summer holidays for 2017 aren't looking quite so expensive now.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

24 comments
RNS to the effect that Mobile Streams (LON:MOS) raised £2.2m (against a target of £1.6m) yesterday.
http://www.investegate.co.uk/mobile-streams-plc--mos-/rns/successful-fundraising-of--2-2m/201612020700087644Q/
On a generally poor day in the markets and with some adverse Bulletin Board comment, a pretty decent result. Shares in Primarybid for anyone?
Best,
Gus.
Paul, have a look at GAW, singnifantly ahead statement. I reckon they will beat the forecast eps by miles. The first half profit is up 100%, and the company always produces better results on the second half, Xmas affect.
Strong balance sheet, and 6% yield and maybe a special dividend.
Not a recommendation, just a stock that may warrant further research.
I've owned CCT for about 5 years now and whilst it raced ahead of itself for a couple of years and has flatlined since the results continue to improve as does it's dividend payout. It still a buy and hold long term for me and yes at some point I expect someone will realize what a great business it is and come in with a bid.
My two children taught me what a great market this company is in and that parents are willing to pay a premium for a character that their children like. Yes characters come and go but CCT have a good range of long terms brands.
Si - Not had the problem on this stock but it has happened to me in the past. iDealing explanation was that limit order only gets triggered when the posted ask price hits or goes lower than my limit price. If other buyers are dealing within the posted spread then the limit order never gets triggered. That doesn't happen when limit order is posted on LSE board but then you run the risk of the order getting filled with lots of small deals each of which attracts broker commission. iDealing won't allow LSE board posting unless agreeing to partial fills so haven't worked a way around that as yet.
Hi Laughton,
Thanks for the explanation which sounds more plausible than the one I got from my broker :-). There certainly were some strange trades going through at the open including one just before 8am at 440p - something else I've not noticed before but tbh I don't normally look at trades in much detail. I was just peaved that the limit order didn't execute and by the time I noticed what was happening I had to pay 471p.
All the best, Si
"This might also help airlines & holiday companies - those European summer holidays for 2017 aren't looking quite so expensive now."
It might - but currency bounce possibly/probably outweighed by oil price increase which is a big cost for airlines in particular.
Could get even cheaper in the next few weeks if Italy votes No. Flights to Europe are quite cheap now, even to Far East it's only about £350.
Having just caught up with the CAMB results from last week (was on hols) I'm a bit nervous about investing in this sector. They say:
The SMMT is currently forecasting a 5% reduction in new car registrations for 2017.
Whilst the 2016 financial year ended well, because of the uncertainty in the economic outlook, the Board is cautious about trading in the coming year. Post the period end, September trading was in line with expectation, however October trading showed some softening in new car margins
Overall it sounds a bit worrying IMHO...
CCT
Even mentioned that they are working to bring on new management, which given the age of the top players is great news.
shares in this toys company have generally been cheap in the past, so it's best to not get too excited about the lowish PER.
All I would say is that you could say the same for Lavendon (LON:LVD) and even possibly Avesco (LON:AVS) and we know what happened in both cases. So recent evidence is that such low-rated, quality companies are very attractive to overseas buyers with sterling depressed. I think there are far worse places to park gains from those two recent successes than Character (LON:CCT).
With regard to the strange mix of debt and cash, all I would mention is that they have an ongoing buy back and it could just be that they believe this is a better use of the cash than paying off the debt? I don't know, but I agree it doesn't make sense on the face of it.
FWIW I bought some more this morning. A funny thing happened though... having read the results I placed a limit order at 460p which subsequently did not get executed by my broker. I phoned them up to ask why not when there were clearly buys going through at 460p or lower from the open. Their explanation was that there was a market maker at the front of the queue filling his boots and the price had moved above the limit by the time he was done. I've never heard of this happening before, does anyone knows if this can happen or is this just BS from my broker? Some of the trades look like PI trades, so did anyone here manage to buy at 460p or lower? I'd be very interested to know...
All the best, Si
You got to the jist of it. Debt is cheap, so buy inventory etc, and conduct share buybacks using debt. Using debt lowers the WACC in the DCF calcs, especially at the moment with the cost of debt where it is -> it's generating higher DCF outputs and creating extra shareholder value to use that debt to conduct buybacks.
If there is one thing I know about CCT, it's that their finance department is tactically very astute.
simoan - I noticed there were two buys of Character (LON:CCT) on Level2 before the open this morning so I thought there might be a feeding-frenzy. In the end there wasn't really but I also could not trade online at first (not unusual) but I finally got in at 473.5 by phone.
After a great run for 2½ years from early 2013, this share has been range-bound for the last 1½ years but hopefully the good numbers in this morning's results and the reassuring remarks on mitigating the effects of the weaker £ will help the SP to rise consistently again.
On limit and spot orders:
It is not BS.
I experience problems on a regular basis which I attribute to market makers.
On limit orders it is reasonable that the price drop below your limit to get a fill if the share price is rising on the day.
If it is falling one would rather not have had the fill! It leads to an instant loss.
However on the spot orders it is very annoying to be pushed aside.
I ask for a price, buy or sell, accept the offer or bid and then the computer tells me 'sorry your trade has not gone through, try placing a limit order'.
Invariably this leads to a more expensive buy or a less profitable sell because somebody else got there first.
There are various solutions. Asking for a level playing field is not one of them!.
Hi Si - I managed to get one of those very early 460 trades. In fact I had c.458.something on the offer a moment earlier but took a little too long double checking a detail so I missed that. A rare occasion where I was able to get in quickly. So your broker's explanation can't be wholly accurate.
Your story resonates though. I have previously supposed that unfulfilled limit orders were due to the fact that as they are processed 'in fair and due turn' and not directly entered on to the order book by my broker. So, when the price is 'right', there is some process that my broker's system follows - fulfilling limit orders equivalent to mine but ahead in the queue perhaps, or just some time lag?? - and that has taken longer to complete than the time when the price was in range... Perhaps that's too naive and simplistic an explanation though!
Hi LE4R,
Well done on getting filled first thing at 460p! I suspected some of the trades were other PI's. I will phone my broker again tomorrow to get a full explanation of how their limit orders work for future reference. Thanks for sharing your thoughts.
All the best, Si
Yes. Using TD I got 1000 at 460p and 30 sec later 500 at 460p. I went straight to the market. I once before tried the same tactic as you, with exact same results. PI's are last in the queue I'm afraid.
PS The "market maker" you got told about was almost definitely filling an order for the company itself i.e. a share buy-back. So you had know chance as they were working for the people that pays them.
You nominate your brokerage account when you register and they transfer the allocation direct. Or you can choose to hold paper shares.
I did wonder whether Paul was likely to comment on the odd upcoming offer on Primary Bid in future?
Thanks. I notice that the minimum investment amount seems to be £1000... which is quite a lot for a company like MOS that is looking decidedly ropey :-/
A question on using Primary Bid please... if one is just applying for shares and paying by debit card, then in what manner do the shares actually get registered to oneself? All my existing share holdings are in a nominee account with a broker.
Paul, just to let you know, Scooby Doo has actually made a comeback. The cartoon series has been refreshed and my daughter is an avid follower.
Hi Paul,
At these levels then, would CCT be something you would add to your portfolio? I was researching this last week and very nearly took the plunge but now looking at getting in, albeit at a price 10% higher...
Regards
PR
Morning Paul.
I raised a discussion point last week about Primarybid to see if anyone on the Stockopedia board was familiar with them but had little response. I used them for the placement for Sound Energy (LON:SOU) last week and found the service efficient and the shares seemed to move smoothly into my account with Charles Stanley (not currently one of their partners) so so far so good. Shame the shares fell after the placement (which was done at Par, no discount) but since my average price is about 20p before taking up the offer (@ 81p), I can't complain too much about this particular dreg. Having been on the wrong side of dilutive AIM placements in the past, I think PB potentially usefully fill a gap in the market.
One comment on the Mobile Streams (LON:MOS) placement. I noticed the CEO, the principal shareholder, is only taking up a fraction of his pro rata holding (something like 2m against a holding of 12m - it's in the RNS) which spooked me slightly given the size of the issue of new shares and the extent of the discount. Not a huge vote of confidence IMO.
Best,
Gus.
Just a comment on the Mobile Streams (LON:MOS) placement. I used to be invested in MOS however in 2013, the CEO sold 245k shares at 72p, 630k shares at 70p and finally 6m shares at c55p. Not wholly unreasonable in wanting to get some financial benefit from building up the company maybe but I got out then. A little while later the share price began its drop to current levels - albeit with occasional rallies. As Paul says, their major (really only significant) source of income has been Argentina, and this has been dwindling. They have been unsuccessful in replicating their model in other central and south american countries and are now trying to break into markets in Africa and India. I've no idea whether they will be successful but given my past experience my 'punts' will continue to lie elsewhere.