Small Cap Value Report (1 Nov 2016) - CVR, TUNG, SPRP

Good morning!
In case you haven't seen it, let me flag up a late update to yesterday's report. As you've probably gathered by now, I'm more a night owl than a morning person. The new sections in yesterday's report cover results from Plexus Holdings (LON:POS) and PPHE Hotel (LON:PPH). The latter in particular looks quite interesting, after refinancing its debt onto long term, low (and fixed) interest rates. Also I commented on the discovery of internal fraud at a subsidiary of T Clarke (LON:CTO).
Here's the link for yesterday's completed report.
Conviviality (LON:CVR)
Share price: 214p (up 4.4% today)
No. shares: 172.1m
Market cap: £368.3m
Trading update - this covers the 26 weeks to 30 Oct 2016, so it's H1 of FY 04/2017.
The background here is that the group embarked on a bold expansion strategy just over a year ago. It acquired a drinks wholesaler, called Matthew Clark. Incidentally, I've started noticing vans with that brand name on them, delivering to local cafe/bars. There are obvious bulk buying efficiencies with Matthew Clark bolted on to the original off licence business of Conviviality.
Two further acquisitions were made afterwards, of Peppermint in Dec 2015, and Bibendum PLB Group in May 2016. Put together, this has more than tripled the turnover of the group, which was £783m in H1, up 211% against prior year, due to the acquisitions.
Various financial details are given, which I'm not really interested in. All that matters is overall performance, and this sounds on track;
The Company is making strong progress with the integration of Matthew Clark and Bibendum PLB Group ahead of plan and the plan to deliver synergies remains on track.
Conviviality continues to perform in line with market expectations for the 52 week period ending 30 April 2017.
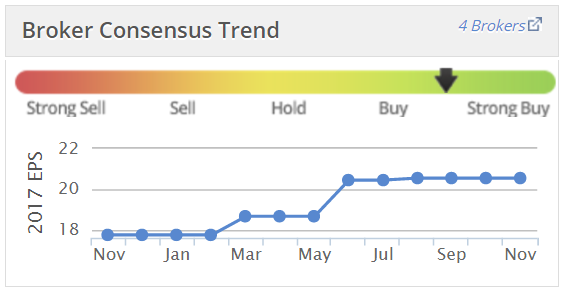
It's interesting to note from Stockopedia's graph that earnings estimates have been revised up several times in the last year. So meeting expectations is actually better than it might at first sound - because the bar has already been raised twice, as you can see below;
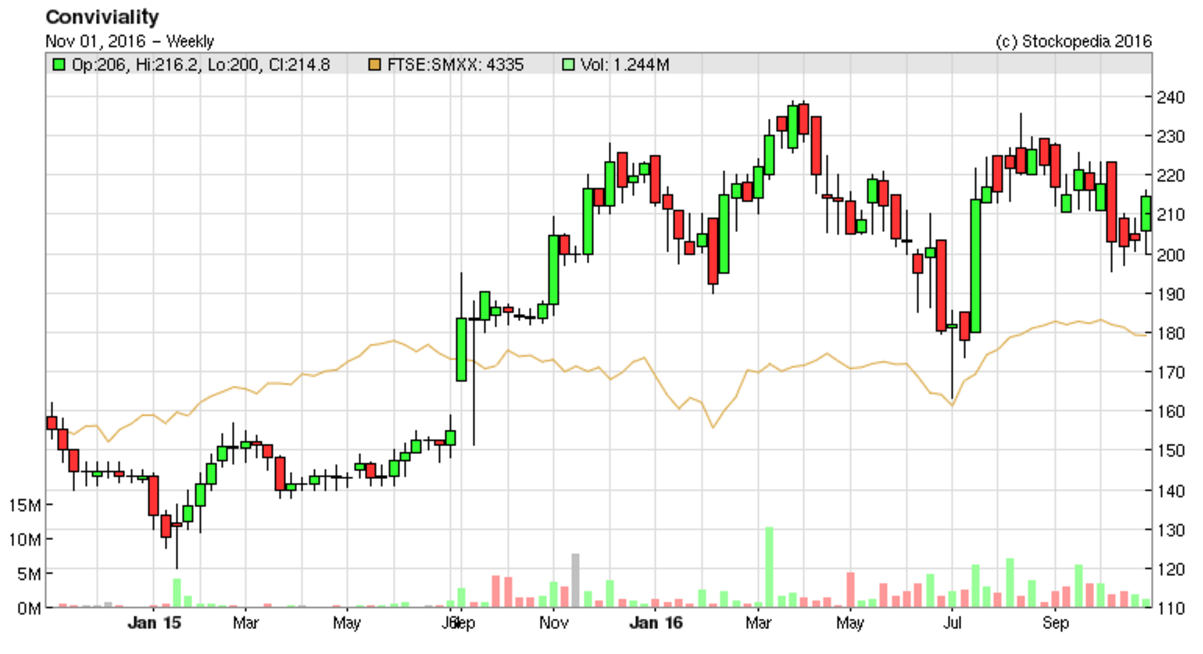
Valuation - I'm quite surprised that the shares have trended sideways (see share chart below) in the last year, despite the improving broker forecasts.
As you can see, the PER looks quite reasonable (although note that there's a fair bit of debt on the balance sheet), and the dividend yield is very high.
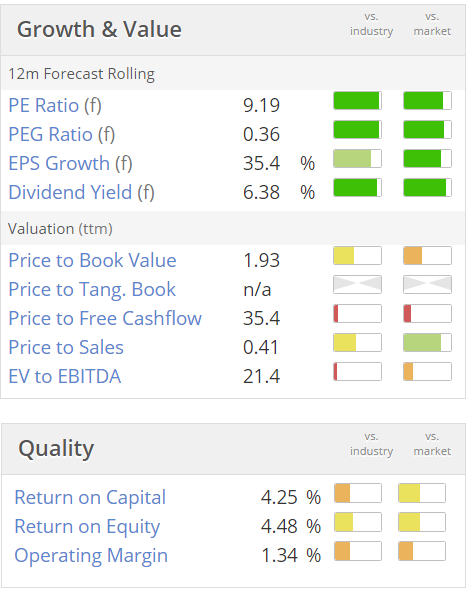
High dividend yields can be a warning sign though - a signal that the market may be concerned the divis might not be sustained at the existing level.
I sound like a stuck record on this point, but personally I very much dislike highly indebted companies paying big divis. They should not be doing this - they should be paying down debt as their main priority in my view. This is becoming increasingly important, as the risk of a UK recession next year does appear to have increased somewhat.
Balance sheet - it's a bit weaker than I would like, and the net debt a bit too high for comfort. Although I should emphasise that there's no sign of any financial distress, I just personally like to have a bigger margin of safety.
My opinion - overall, things seem to be going fairly well, with a major acquisition spree apparently handled well.
The risk of a recession, and higher interest rates are a worry, as this type of company would suffer in that environment. That said, the valuation here does look fairly modest, and I imagine there might be more synergies yet to feed through.
I'm quite tempted, so it''s going on my watch list - which is really a think about it a bit more list.
Tungsten (LON:TUNG) - was meant to have sold its bank by the end of Oct 2016. It today says this is in the final stages of regulatory approvals.
I remain of the view that this share is a dead loss. It has not yet demonstrated that it's a viable business.
Sprue Aegis (LON:SPRP) - an update today sounds more like marketing material, than a proper update. It mentions nothing about overall performance, or how the company is faring versus market expectations. Therefore I think it's neutral for the share price.
So I assume the company is just trying to reassure shareholders that they're doing good things, after all the problems in the last year or so.
Skimming the numbers on Stockopedia, it looks as if brokers are forecasting a maintained divi, which would give a lovely 5.7% yield. Also remember this company has a decent cash pile. So if you think it can recover from the massive profit warning in May, then it might be worth a look. Personally I'm a bit sceptical about this company now - as various things have gone quite badly wrong, and performance has been unpredictable.
So for me, the jury is still out on Sprue.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

29 comments
Re. Conviviality (LON:CVR) I analysed this stock this morning with a view to taking a long position and in conclusion I think that the perceived rewards do not quite justify the potential risks. Here is why, all IMO.
* an operating margin of only 1.3% (FY16) is probably par for this kind of business, but combine that with a highly leveraged balance sheet, it is not a sign of strength.
* FY16 balance sheet shows a negative Net Tangible Asset Value. Not surprising given the furious pace of recent acquisitions
* the HY update of today says gross revenues are likely to be £783m, which is on course for a full year broker forecast of £1576m. However they do not give us any clue about the likely emerging earnings or profits.
* Broker forecasts for FY17 are eps of 20.6p which is an implied eps growth rate of 66.8% . This contrasts with the previous year's eps growth rate of 9.7%. Not impossible but a steep hurdle to negotiate.
Putting aside other potential headwinds, such as cost inflation and a squeeze on disposable income, I just do not find the risk: reward ratio sufficiently attractive. It looks to me a high wire act where a single misstep could seriously damage the company's health.
All IMO and PDYOR . I have no long or short position in this stock.
CVR:
I am keen on Conviviality. Think the valuation is extremely attractive. Quite surprised at so much scepticism but I guess therein lies the opportunity.
Debt is high due to acquisitions but the acquisitions it has made make sense, with huge cost and revenue benefits.
Good cash flow conversion will bring debt down as was demonstrated with last results where net debt was less than forecast.
£ weakness will increase some import costs but much of the cost of a bottle of wine in the UK is tax, so the impact may be less than some fear.
It may also benefit from more staycations and increased visitors to the UK. Q3 saw a record number of visitors to the UK.
Lot of talk of recession, which is not impossible but this is certainly not one of the first stocks I would sell. I reckon it will prove quite resilient as unless unemployment rises substantially I think people are more likely to give up other things such as overseas holidays than going out for an evening. If they do give up going out and stay in perhaps they'll buy their booze from Bargain Booze or Wine Rack
Most importantly, I think this is a management story. Diana Hunter has assembled a top notch team to head up each of the three divisions. I think the team will create a lot of share holder value though benefits of scale as it consolidates what has traditionally been quite a fragmented industry.
I know it is not an infallible test but I gain some comfort from seeing the likes of Henderson, Miton, Artemis, Hargeave Hale, Majedie and Ruffer as major shareholders. All good investors who cannot be accused of being index huggers but stock pickers.
Think the share price will be substantially higher in a year's time.
John,
With your wider view any reasons that Diana left John Lewis? Pretty good pension and benefits for partners, perhaps limit of x20 from lowest to highest salary?
In relation to your question about booze for the poor: I live in a very poor area (in relation to rest of town which is mainly grade 2 listed) and the only supermarkets within walking distance are a small One Stop (seems to be a Tesco sneaked into the Post Office under another label), an M&S food hall and Waitrose. I shop at Lidl but it is several miles away, on the other side of both river and town and takes two bus trips each way with different companies to get there. So I do so love my geriatric bus pass! The manager of local BB sells wine and beer (overpriced perhaps but less than Waitrose) to shoppers on the way home, they walk more than a mile home and pass the BB within sight of their front doors. I agree with your thoughts about sp in a year's time.
Compelled to comment on this one
- Material strategy change
The AIM Admission document from July 2103 states the following:
“The management team, now led by Diana Hunter, an experienced retailer previously at Waitrose and Sainsbury’s, is implementing a strategy which the Directors believe will drive Franchisee engagement and growth over the next three years. The Directors expect to extend reach into new locations, penetrate further into the South of England, increase the Group’s convenience offering and further increase the focus on its wine offering.
The Directors believe that admission to trading on AIM will enable additional incentivisation of both Franchisees,..."
Section 7 , Strategy outlines the key elements of Diane Hunter’s strategy for the group. The comment on acquisitions as was follows:
“Acquisitions may be carefully considered in complementary segments of the market to assist growth in mid-affluent catchment areas.”
The acquisitions of Matthew Clark and Bibendum have absolutely nothing to do with the above and little to do with the franchise offering.
Punch Taverns had been eager to extract itself from Matthew Clark for many years and it came across an eager buyer in Conviviality.
I have reflected on the acquisitions and listened to the latest presentation and remain unconvinced
Management considered that Conviviality now has “a unique model in the UK, connecting the on-trade and off-trade that enables it to optimise revenue and profit from brands and exclusive labels by maximising their distribution potential across all drinking occasions.”
On further considering we don’t buy into this!
Management has assembled a hugely complicated beast operating across on and off trade with the real focus on buying and distribution synergies, rather than retail focus as was the original plan....only 2 years ago
- Review of acquisitions of Matthew Clark and Bibendum
Matthew Clark is the UK’s largest independent alcohol wholesaler and distributor to the on-trade drinks sector.
For the year ended 28 February 2015, Matthew Clark generated revenues of £811.2m and adjusted EBITDA of £25.3m.
Looking at Free Cash Flow (FCF) over the previous 4 year’s financial statements as a private company
FCF has averaged £10m over the past 4 years. This includes the most recent financial year 2015 when capex was only £900k less than half the norm, suggesting this was being packaged up for sale?
Realistically free cash flow has averaged c £9m per annum over the past 4 years.
Modest capex also implies significant under investment!
The purchase price of £200m looks quite full.
The Group acquired Bibendum PLB for an enterprise value of £60m
One of the grounds for the acquisition was that It would “strengthen the group's skills and capabilities, specifically in customer insights, producer relationships and old world and premium wines, as well as strengthening the group in premium trade sectors”
Surely this is hard to believe given the earlier acquisition of Matthew Clark, which already dominates its market.
FCF for Bibendum over the past few years has been negative.
£60m looks a very full price
These look 2 fairly ordinary businesses operating in a highly competitive market with little differentiation.
The acquisitions were supported by big share placings and a large amount of debt – net gearing at 1st may 2016 was approx. 47%
- CEO’s positioning in this
The strategy smacks of empire building to us for little real benefit to shareholders
Diane Hunter has an interest in 826k shares all of which appear to be option derived
She has never acquired shares in the market or participated in the fund raisings to support the acquisitions
A ‘close associate’ of Diane Hunter sold 33,333 shares at 222p in Sept 2016
CEO salary in the last year was £845k, with basic salary £450k
She can afford to participate with real cash!
I won't even expand on currency!
The rationale of cobbling together several ordinary businesses addressing different markets is starting to look highly questionable to us.
Cash generation from Matthew Clark and Bibendum over the past 4 years has been ordinary, to say the least!
Matthew Clark appears underinvested and had been up for sale for sometime before CVR swooped
The CEO has little equity interest and is vastly overpaid relative to real achievement to date
The whole enterprise has become hugely complicated to us operating across multiple end markets, albeit with a common product
There is plenty of management speak in the presentation to enjoy!
It's a trickyone!
Wonderful bit of sleuthing there.
We should be very careful of management who grow by acquisition. It means they can justify high pay and bonuses for themselves (because they're running a bigger company) even if it means shareholders see very little benefit to the bottom line.
I don't know how anyone could own Conviviality (LON:CVR). The business sounds sexy and defensive (selling booze to Brits, what could go wrong!?), but the cash flows and margins suggest otherwise. For all the hype, the acquisitions have added nothing to the bottom line. Looks to me like it's just given management an excuse to increase their salaries, bonuses and create a favourable LTIP. The LTIP itself seems especially egregious. They are already paying a high salary, a huge bonus, yet they're also going to give a chunk of the company away for free as well?
"I don't know how anyone could own Conviviality (LON:CVR) " I plead: Guilty as charged. In my defence the driver of Matthew Clark big lorry outside 'spoons is getting overtime most weeks. But I remember that Paul was equally dismissive in his previous post, something on lines "it will all fall apart" To date I have done well on basis of local and family research but keep my finger close to the sell button, As you point out: high rewards given to the BoD on the basis of rising sp. But if this is (probably) on the basis of high (not sustainable?) yield in a new company it does ring alarm bells to me too. I have a small cushion in that I am up more than 30% but will be gone on first profit warning. Seadoc
Conviviality's sales whether through off-licences or restaurants are entirely dependent on discretionary spending. I don't see the outlook for this as being likely to improve and would therefore not be attracted by this company with its operating margin of only 1.34%.
Ref CVR and broker upgrades
are these genuine upgrades to estimates or reflective of acquisitions so not really an upgrade on a true lfl basis if the extra expected EPS expected comes with debt that was not their previously (or less cash at bank). It seems the most recent increase was around the time of the Bibendum PLB finance being drawn.
Although looking at the announcement in may they advised in May trading was slightly ahead and Matthew Clarke was trading well so i could see why estimates would be increasing based on trading alone.
In summary i would like to hope EPS forecasts are increasing if debt is increasing !!
More research needed but seems a nice little business albeit could there be competition from online competitors? eating into margins.
Hey Ho.
While I'm here. I flag up Mobile Streams (LON:MOS) a mobile apps developer and vendor, one of Paul's previous fizz stocks that I hold a freebie in having top sliced on a previous rise.
Hi Gus,
I'm sorry to say this is flawed thinking. It's always dangerous to consider something as being "a freebie" because you place less value on it and these shares have real value. I don't want to come across all "preachy" but it's just that I used to tend to think the same way until I read Richard Thaler's excellent book on the founding of behavioural economics called "Misbehaving". If you haven't read it, I can highly recommend it!
All the best, Si
Hi Simoan.
Thanks for the heads up on Richard Thaler's book. I'll take a look.
I was being a little flippant with my earlier comment. I concur that a profit or loss should be respected just the same whether it's derived from hard earned cash or re-invested paper profits, In this particular case, I bought Mobile Streams (LON:MOS) speculatively on a dip and have been able to take out all of my ante stake as well as a 20% pick up and still be left with a few shares that I am happy to let run without feeling guilty. It's not really the type of speculative share that I typically buy into - perhaps I should after today's uplift.
Best,
Gus.
Hi Gus,
I was being a little flippant with my earlier comment. I concur that a profit or loss should be respected just the same whether it's derived from hard earned cash or re-invested paper profits, In this particular case, I bought Mobile Streams (LON:MOS) speculatively on a dip and have been able to take out all of my ante stake as well as a 20% pick up and still be left with a few shares that I am happy to let run without feeling guilty. It's not really the type of speculative share that I typically buy into - perhaps I should after today's uplift.
Since reading the book I know my own approach has changed - I'm trying to become an "econ" rather than a "human" when it comes to investment decisions and try to eradicate as many of my in-built biases as possible when deciding to buy, sell or hold. I've seen a number of people comment similarly to yourself about a holding being "for free" after top-slicing recently and so finally decided to pipe up! I've been in the same situation as you describe many times, including with several holdings currently, and so recognise that you need to value any holding as if you paid the market price for it ten minutes ago, not something you bought a few years ago and is now "free".
All the best, Si
...you need to value any holding as if you paid the market price for it ten minutes ago, not something you bought a few years ago and is now "free".
Or even better, forget what you paid for any holding. We almost can't help but anchor a holding to its cost but what you paid does not affect its attractiveness or current value (as opposed to market price) one jot. Say goodbye to holding a business where the story has gone wrong simply because crystallising a loss hurts.
Say goodbye to selling a great business that's got a long way to go merely because grabbing a profit is so reassuring and risk-reducing.
By all means top slice to balance your portfolio though.
Or even better, forget what you paid for any holding.
Yes, I guess, but the idea I was trying to get across is that the brain also has this mechanism for placing more importance on recent events than past events, so I find it easier to think of buying as a very recent event. How many people (if their honest!) buy or sell a share and then keep looking at the price for the rest of the day, then look a little less the next days etc? I know this is something I used to do - there is a time element to these biases which you need to recognise also!
All the best, Si
gosh Paul I didn't think you took brokers targets seriously, still chacun as they say
bobo,
gosh Paul I didn't think you took brokers targets seriously, still chacun as they say
Usually I ignore broker share price targets, as they're often not very logical, or sensible. That's why I very rarely mention broker share price targets or recommendations in my reports.
I do however look closely at broker earnings forecasts, and think carefully about whether they look sensible or not. If I'm happy that the forecasts seem sensible, then I'll refer to them in my reports.
Hope that clarifies, as your post suggests that you're confused.
Paul.
Its rather similar to T Clarke sneaking out something late yesterday perhaps hoping would notice it!
Hi Paul,
Conviviality (LON:CVR) I got in June 15, after a family event, big birthday, sadly now departed. Most of her grandchildren are or were recently students and many in NW. Bargain Booze was THE place to go. I was surprised to learn that there was one locally, spoke with the manager and took his recommendations about the wine. I will continue buying wine elsewhere but he was really helpful, he has been a convenience store owner for many years on the same site next to the chippie he also owns and is surrounded by social housing. The till is provided by Conviviality (LON:CVR), gives full details of staff sales (he had just given one a bit of career advice (along lines of Foxtrot Oscar) but also he replenishes store on basis of the sales entered into the till over the last week, gives him a breakdown of profitability etc and interestingly it identified and he had just started selling loo roll which is/was highly profitable and not sold at local garage as it takes up too much space. So happy to buy in but worried about your last report. Slightly reassured that Diana Hunter gave up a senior management position in Waitrose to float the company. I agree it could all still go pear shaped but return to date over 50% and annualized at over 35% with a yield 4.6%. Cheapest pint and breakfast in town is 'spoons and who delivers the supplies? The lorry says Matthew Clark so another reason to wait and see.
Regards, Seadoc
PS any chance for an interview? Good profile on retail week in 2013:
https://www.retail-week.com/sectors/grocery/profile-diana-hunter-chief-executive-of-bargain-booze-owner-conviviality-retail/5051197.article
Today's PPHE's trading update shows LFL "growth" to end September. But it's expressed in £. Given the ~ 25% fall in the £/€ rate between the reporting periods, this suggests the opposite to me.
Wine will become more expensive due to the exchange rate issues which will presumably have some impact on CVR
Yes that is true but perhaps some people may convert to beer in that case and this is also wholesaled by CVR. On a related matter, English wine producers will likely benefit from the exchange rate effects and this is one reason I have recently purchase a small shareholding in Chapel Down which is also cashing in on strong demand for craft beers. The shareholder's benefits are also quite generous and useful with Christmas coming up!
I wish you luck with Chapel Down. Always seemed massively overpriced to me.
Good morning Paul,
Looks quiet again for small cap results today however a micro cap called Paragon entertainment (PEL) caught my eye when reading through statements. I think its around 3.5-4M market cap so very illiquid and dangerous, says it is going to beat market forcasts and do 13.2M rev and around 1M EBITDA F/Y.
Maybe worth a look. I have been right about these things before ;)
Damien.
Hi Damien,
I've held Paragon Entertainment (PEL) shares for c2 years now and they seem to be turning the business around. The directors are invested themselves and are happy to correspond with PI's - both of which I take to be good signs. They are running a nice niche business with a strong order book and pipeline and are focussing (at last) on making the business profitable. It's probably too small for Paul to run his eye over, but I'd be interested in seeing the results if he did.
(Hopefully) Luckym
Hi,
Re Paragon Entertainment (LON:PEL) - I did look at the announcement today, but didn't mention it in the report above, as it's too small & illiquid.
Also, if you look at the company's track record, it's been going nowhere for years. They did a presentation at Mello a couple of years ago, which I remember for it being absolutely hopeless.
It's the sort of lifestyle business that will have the occasional bumper year, or maybe even two, if you're very lucky, but there's no sustainability of profits in my view. They just work on projects, and may have got some lucrative work for now.
My advice - take a cold shower. Hide your online dealing password! Then take a look at the share price graph, and the dividends over the past 6 years (hint, they're nil).
It could be a nice little speculation, on today's good news, who knows? But as a long term investment, forget it! PEL is, at best, a total punt.
Regards, Paul.
Hi Paul,
Given Conviviality (LON:CVR) business model, wouldn't it be more resilient in the event of an economic down-turn ie. people will still continue to drink?
Best wishes,
Imran.
Hi Imran,
Yes, people do still drink in recessions. So the off licences would probably do alright. But restaurants are a different matter. That's discretionary spending, and lots of them go bust in recessions, as customers rein in their spending. That could leave CVR with a lot of bad debts to absorb perhaps.
If its debt was a bit lower, I'd risk it, but I think this is the wrong time to be buying shares in quite highly indebted companies.
Regards, Paul.
Thanks Paul.
Did you or any other Stocko readers see the Bilby (LON:BILB) trading update (or profit warning) issued after the market opening this am. I don't hold, but companies shouldn't be issuing an update at 10am. Luckily I don't hold, but the company should have issued at 7am.
Bilby (LON:BILB) is quite topical for me in that I was stopped out yesterday morning and so missed today's profit warning and 16% fall - just hope the SFO don't think I'm an insider! Shame it was already down by the 20% that triggered the stop loss but hey-ho it's always nice when the dog's new trick gains an immediate reward.
While I'm here. I flag up Mobile Streams (LON:MOS) a mobile apps developer and vendor, one of Paul's previous fizz stocks that I hold a freebie in having top sliced on a previous rise. Share price is up today by 25-30% on no public news although they are due to give an update on Indian subscriber numbers in the near future. Maybe a leak or just speculation chasing the small number of freely floated shares.
Best,
Gus.