Small Cap Value Report (10 Dec 2014) - MYX, FITB, DQE, BWNG

Good morning!
I had a few technical problems yesterday morning, and then fell asleep in the afternoon, so finished off yesterday's report in the evening. So if you want to see the completed article, then click here.
MyCelx Technologies (LON:MYX)
Shareholders here must be livid, as the company has this morning announced a Placing at 150p, or a 21% discount to last night's close of 190p per the company. It looks as if existing holders will not have an opportunity to participate, as I don't see any mention of an Open Offer.
I really must get around to updating my PlacingWatch website in the new year, as the issue of giving away a big discount to placees, whilst existing holders are shut out, is outrageous. Apparently companies can do an Open Offer very easily & cheaply, if it's less than £5m, so I've been told. It only becomes onerous in terms of cost above that level, due to some EU regulation. Something along those lines anyway.
As I always say, the best way to avoid being stuffed by repeated discounted Placings is just not to buy shares in companies that need to raise any money! Also, if management hold a decent slice of the equity (over 10%-ish) then they tend to think much more like long-term owners, rather than hired hands keen on empire building. So interests aligned & all that.
Fitbug Holdings (LON:FITB)
The above observations bring me nicely onto this little speculation!
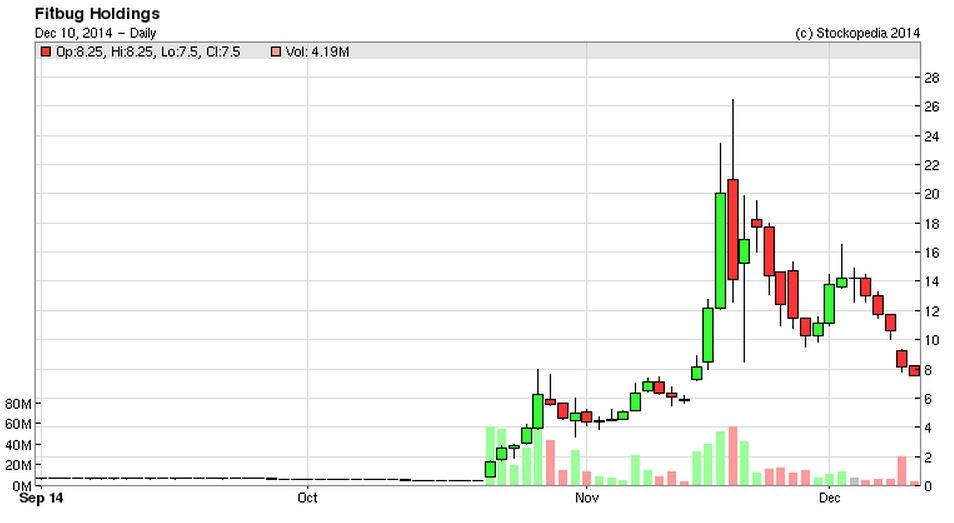
As reported here in my report of 28 Oct 2014, the Balance Sheet at Fitbug was clearly insolvent, so I called it a "racing certainty" that a Placing would be done. It has of course, as was announced yesterday, for £3.5m before expenses being raised with new shares issued at 9p.
So as you can see from the three month chart, this has been a share for crazy speculators only, not investors. It just isn't worth getting involved in this type of thing, unless you are honest with yourself and appreciate that you're just gambling.
With this type of micro cap, the share price will nearly always fall in the month or so whilst a Placing is being set up - as a good bit of insider dealing goes on from people who know about the Placing, locking in their ill-gotten gains onto unsuspecting mugs who are buying in the open market at higher prices.
It's unusual to see the share price go below the Placing price immediately, because people will obviously stop flipping the Placing stock once there is no profit to be made (i.e. at 9p). In this case though, there seem to be some convertible loan notes with a conversion price of only 1.5p, so that is providing a smashing profit for holders there. Again, at the expense of the gullible, buying the shares at 5-6 times that price in the open market!
Honestly, what a situation! We can avoid all these shenanigans by only buying companies with solid Balance Sheets, hence why I'll never tire of banging on about it.
People can make crazy money in a bull market by ignoring Balance Sheet strength, but that's not a workable long-term strategy. Especially as the banks will eventually tire of supporting zombie companies, and we could start seeing some harsh lessons being dished out to the unwary, as insolvent companies are forced by the banks to repair their Balance Sheets (i.e. the bank insisting on them doing a heavily discounted equity fundraising).
That's just an accident waiting to happen in my view, the only question is the timing.
DQ Entertainment (LON:DQE)
Continuing the theme of companies that I have avoided like the plague, is this Indian animated films company. There was a bizarre announcement yesterday, which looks incredibly convoluted (nearly always a bad sign in itself).
I read it twice, and it seemed to essentially be a de-listing announcement, combined with news of fresh funding, and a merger with another company. De-listing from AIM seems to be at the core of their plans though, hence why it was very strange that the shares actually went up yesterday, when you would have expected them to crash.
I see that that blip up in price yesterday has reversed today, and anyone left holding this bizarre company's shares probably needs to get their head around the announcement from yesterday pretty sharpish, as it looks like a de-listing to me.
The company's products are fiction, and their accounts have always looked like fiction to me too. Yet again, the overseas company listed on AIM bargepole has proved very useful. Why take the risk, when you don't have to, and when so many of them go disastrously wrong?
N Brown (LON:BWNG)
This is quite a big retailer, with a market cap above £900m, so it's outside my small caps remit. However, it is interesting to note their trading update today, because it confirms that trading has returned to normal growth rates, after the unseasonally mild weather in Sep & early Oct.
That has read-across for other clothing retailers - this cold snap now is good news, and they will recoup some sales for cold weather items like coats. It may not be enough to make up the profit shortfall for some though. Browns says that guidance is unchanged. That puts it on a reasonable PER of about 12, and a nice divi of 4.5%.
Internet retailers
The stock market has had a weird obsession with new companies selling online, valuing them at extraordinary multiples of earnings (if they are profitable!). Yet, sooner or later I think the penny will drop that internet retailers are just retailers, and have competition from all the existing retailers online too. They haven't invented some magic formula for higher profits - look at ASOS (LON:ASC) - it's operating profit margins are pathetically low. So where have all savings gone from not having a stores network? Who knows, I just reckon it's not actually a very good business.
The same goes for AO World (LON:AO.) and Ocado (LON:OCDO) - both seem ludicrously over-priced, and yet have tons of competition, and neither really makes any money. Both are capex hungry too.
It might well be worth looking at bricks & mortar retailers, and scrutinising who is doing the online bit best, in addition to their store network?
I think there will be a big shake-up in valuations of online-only retailers at some point, maybe it's a theme for 2015, when investors see the growth slowing down, and start to consider that many online retailers are not very good businesses, in terms of net profit margins, ability to pay divis, etc.
Bricks and mortar retailers in many cases are doing online very well - so the notion that internet-only retailers have a competitive advantage looks nonsense to me. Valuations may well start to reflect that after a while? Something for me to ponder more over Xmas anyway.
I noted also that when I've visited Argos, owned by Home Retail (LON:HOME) that it's been mobbed out. OK, it would be anyway at this time of year, but also their TV ads seem to have been highly prominent this year. I strongly suspect Argos might turn out to be one the winners, reporting good trading in January 2015? I love their click & collect offering, and use it as my default place to buy sundry household items, as they always seem to have a good selection of everything, at good prices.
Alternative Networks (LON:AN.)
I've had a very quick look at the accounts published this morning, but can't get my head around them - the telecoms sector is not one I'm confident about analysing, as things change so quickly, it's difficult to know how to value companies.
Divdends - are rising nicely, with Stockopedia showing a forecast yield of about 3.7%.
Balance Sheet - seems dominated by intangibles. Total equity reported today is £37.1m, but take off the £76.7m intangible assets, and the NTAV is negative by £39.6m. That rules it out for me, but there does seem to be a decently profitable business here, so for people familiar with the sector it might be worth a glance perhaps?
Got to leave it there for today, as I have a lunch meeting in London.
Regards, Paul.
(of the companies mentioned today, Paul has no long or short positions.A fund management company with which Paul is associated may hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

5 comments
Plenty of red flags on DQ Entertainment (LON:DQE), although not quite as many as on a company like Quindell (LON:QPP). Warning signs include:
* low returns on equity (circa 7%)
* AIM-listed foreign stock
* overloaded with intangibles
* bad chart
* absurdly low PE
Chris Moyles once wrote a book which he described as a good "toilet book". To paraphrase him, DQ Entertainment (LON:DQE) is what I would call a toilet stock.Guaranteed to stink up any portfolio.
Paul, I love your reports but I do despair a bit with your characterisation of ASOS. :)
The company has made stacks of money over the years, but it has all been reinvested in creating a global retailer! :-)
You talk in this report about capital raising. To that point, it is illustrative and highly relevant that ASOS has grown entirely from reinvested profits!
The company will do well over £1 billion in sales this year versus just one fifth of that five years ago… in other words it's a real business that's grown gangbusters to-date. I don't see why *not* reinvesting and instead slowing growth just to show higher margins and to return some measly dividend would make it a more real company? :-)
The time to do that is when the window for fast growth has closed.
Of course we can argue all day about what value one should place on such a business…and also about prospects for future growth. And I think there is no doubt the market has got carried away about this company before.
Perhaps even today, although I am longer the shares from lower levels. :-)
Anyway, keep up the awesome work please! :-)
Agree with Paul's comments on Home Retail. It is a high street business that seems to have adapted quickly and well to online. But also agree that ASOS and (now Ocado) have grabbed market share via online and used the profits to "get big" quick. I see more Ocado vans doing deliveries than any other supermarket round my neck of the woods. With no stores and low wage staff they must be doing well.
Ref DQE - just another object lesson in why not to invest in these more speculative companies unless its a complete "punt" type stake you are happy to lose.
I had a small punt on DQE as everything seemed pretty simple business model wise and the Jungle Book in particular look like some good IP and they also had Peter Pan etc lined up.
The reality is that foreign entity owner/managers can engineer any situation that suits them to shaft shareholders - probably doing this without breaking any laws.
With specific reference to DQE and the announcement - the poor cashflow and low market cap must make this announcement overall better news than bad, but if the consequence of the changes is that shareholders will be shafted in 2 years time this is the time we were probably told that it was going to happen. Beggars (owners of companies with no real cashflow) cant be choosers.
I guess holders can dream the extra wad of cash (if it turns up) will enable them to complete their current projects and get the future cashflow rolling in before the tap stops.
I enjoyed the little bit of speculation with Fitbug while it lasted. It is a long time ago since I bought & sold in the same day fore a profit. Once in a blue moon it adds a bit of excitement. It is certainly not worth anything like 9p. Fitbit is a similar product, but moor expensive, with a court case looming ahead. The only winners here will be the solicitors.
I do have some more stable companies like AHT which has a good write up today.