Small Cap Value Report (9 Dec 2014) - ZYT, PRES, IMO, ESR

Good morning! There's a lot of red on my screen today, what with another nasty profit warning from Tesco (LON:TSCO). Also, ASOS (LON:ASC) looks to have gone ex-growth internationally, with a weak Q3 trading update this morning, which makes its sky-high rating look all the more inappropriate.
Also, I wonder how long the even more crazy rating at AO World (LON:AO.) can continue to defy gravity and logic? It just amazes me the way the market repeatedly takes growth companies up to such silly over-priced levels, when it's so obvious that sooner or later they crash back down to earth. Who buys things at such stretched prices, and why? How come they have any money left?!!
Anyway, let's have a look at some small caps.
Zytronic (LON:ZYT)
Share price: 295p (up 11p this morning)
No. shares: 15.2m
Market Cap: £44.8m
I last did a detailed review of Zytronic, a UK maker of bespoke touch-screens, after its positive trading statement on 10 Sep 2014. My guess then was that the company might be heading for about 18p EPS for the full year to 30 Sep 2014. My conclusion was that the shares looked good value at 246p.
Preliminary results for the year ended 30 Sep 2014 are out this morning, and look excellent to me. The company has out-performed the increased market expectations, by delivering basic EPS of 19.6p, a whopping 77% increase on last year - which was admittedly a bad year, when the company ran into some problems with essentially a temporary gap opening up in the order book (if I understood it correctly).
Particularly striking is a much improved gross margin, which is up from 28.4% last year to 36.6% this time. Turnover hasn't risen that much, up 9% to £18.9m, so this is still a small business, but has strong pricing power - it made a pre-tax profit of £3.3m, and generated an even more impressive £4.2m in operating cashflow.
Balance Sheet - is terrific, and is a great pleasure to read. Current assets of £14.0m represents a remarkable 5.1 times current liabilities. There's £7.8m in net cash included within that too, or just over 51p per share in net cash. So 17.4% of the share price is the company's own bank balance, which gives a very nice buffer in valuation terms, and you can sleep very soundly owning this share - even if they have a bad year, the divis aren't under any threat, nor is the company's solvency.
Dividends - the total divis have been increased from 9.1p last year to 10.0p this year, so that's a healthy yield of about 3.4%, twice covered.
Outlook - sounds OK - the company says that both sales and order book are up on last year, at this early stage of the new financial year.
My opinion - it's great to see the company firmly back on track, after a difficult year in 2013. In my view smaller companies are much more prone to profit warnings than larger companies, as they are often heavily dependent on a few key customers and contracts. So with this type of company, every now and then a gap appears in the order book, and a profit warning is issued. That doesn't suddenly make it a bad company, yet that is how the market often reacts. Such situations can be good buying opportunities in my view, providing nothing is fundamentally broken at the company in terms of its market position, etc.
It doesn't always work, but in this case it has done. I can't see any reason to sell the shares now that things are back on track. Strip out the cash, and the valuation is still actually quite reasonable. It pays nice divis too, so I shall continue to hold this one for the foreseeable future.
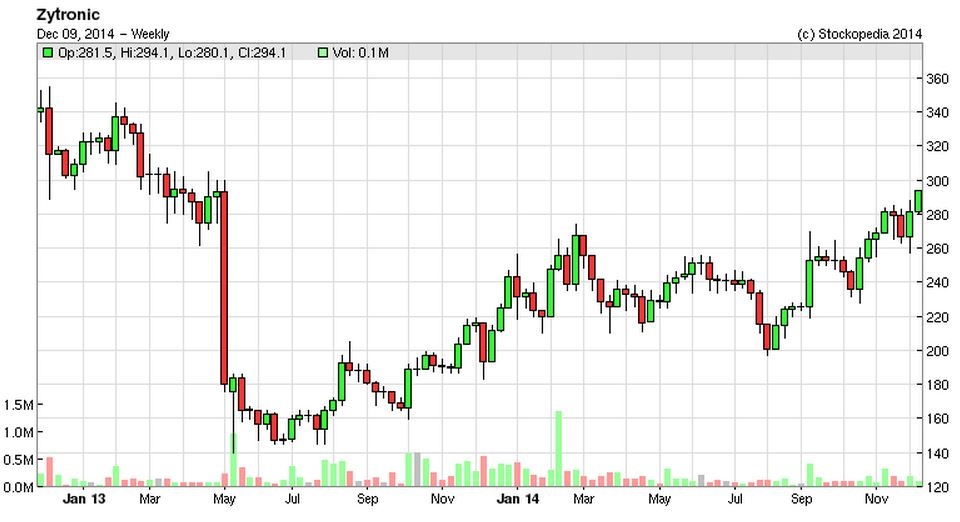
As you can see from the two year chart, it's now fully recovered from the profit warning in May 2013;
Pressure Technologies (LON:PRES)
Share price: 500p (down 62p today)
No. shares: 14.4m
Market Cap: £72.0m
Preliminary results for the year ended 27 Sep 2014 are published this morning. The figures look terrific - revenue up 57% to £54.0m, and underlying operating profit up 138% to £7.8m. Wow!
So with results that good, why are the shares down? That seems to be down to the wobbly-sounding outlook. Although the order book was up 14% at year end, the company indicates that a reduction in sales is expected for their cylinders supplied to the deep water oil & gas market. Nor suprising, considering the rapid & huge fall in the price of oil recently.
I don't know this business well enough to gauge how important that particular activity is to the group results as a whole. Ah, I've just found a section in the results that gives a breakdown - and 73% of group turnover for 2014 was from the oil & gas sector. Oh dear, that's not good - the company says today;
The general air of uncertainty in the oil & gas sector has resulted in major development projects being postponed, or re-engineered to reduce costs.
My opinion - I can't see any way to value this company, as its markets are too uncertain for me (not being a sector that I know anything about). I would imagine that the risk of a profit warning is probably now very high, given the collapse in the price of oil recently, which is the main sector that PRES serves. I'll watch from the sidelines.
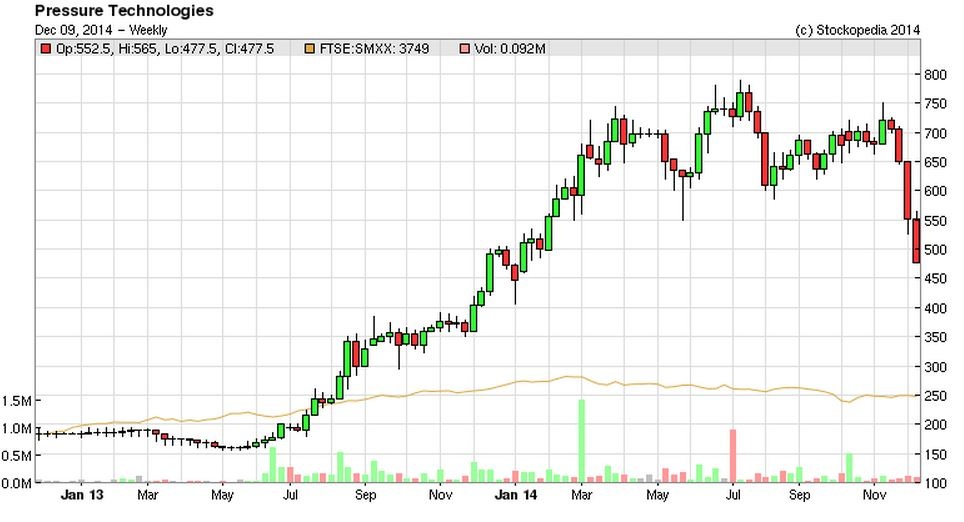
As you can see from the chart below, the share price now seems to be in freefall, so catching the bottom would be difficult.
IMImobile (LON:IMO)
Interim results for the six months to 30 Sep 2014 are out today, and look fairly solid to me. Adjusted profit is up 29% to £2.3m. The balance sheet is strong, although bear in mind that cash is flattered since £10m was spent on an acquisition just after the period end.
I like this company - I met the CEO in the summer, and was very impressed with both him, and the company, so it's been on my watchlist since. It's a software company in the telecoms sector, providing software for major companies which optimises their emails & texts to customers, and various other things connected with mobile phone operators. The client list is very impressive - blue chips.
I can't see any accounting funnies, which is good. I particularly like that this company expenses all development spending, which is the most conservative accounting treatment.
I spoke to the CEO again today, and it seems to me that this could be an interesting growth company - although it's not a sector I understand particularly, and my slight concern is that things move fast in this sector, with products/services having a fairly short shelf-life, until something new is developed by the competition.
The company today says it is trading in line with expectations, so that makes the valuation look about right probably, in my view. The shares have held up well since the IPO in Jun 2014. This looks an interesting company, and worthy of further research.
Ensor Holdings (LON:ESR)
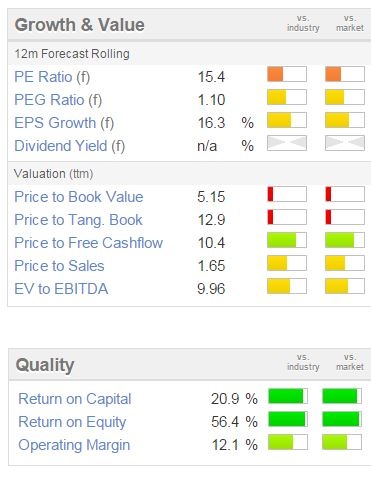
Interim results to 30 Sep 2014 look impressive - with operating profit up 98% to £1.3m. The company seems to be on a roll - it makes building products.
Its balance sheet looks fine, although there is a small pension deficit.
The shares look reasonably good value, if the strong trading in H1 continues.
So this seems another share that is worthy of some further research.
Regards, Paul.
(of the companies mentioned today, Paul has long position(s) in ZYT, and no short positions.
A fund management company with which Paul is associated may hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

20 comments
Pressure Technologies seems to me to be a quality company. In the short term I think their profits will be hit though it'll be interesting to see if their diversification strategy works well. Long term though the share price seems to me heading towards "steal" territory. oil/gas will recover at some point in the longer term so those who bought recently if they hold long enough should do well. I'm going to see if it hits 200 or below before I buy a slot.
cig, dangersimpson - Re. AO. -
I have done some back of a fag packet calcs on the latest HY results, and you guys are right.
* Total revenues £217m
* Operating Profit £0.9m
* Profit before tax £0.8m
* assume 6.5% of total sales are warranties = £14m
* Operating margins on warranty policies can be as high as 50% - 70%. So operating profit from warranty sales = £7m - £ 10m, say £8m
So without the warranty business, the co. would be heavily loss making, and it is this business that is keeping its head above water. Which makes their PE of 96 look more ridiculous and perhaps should be rated as an insurance company, say a PE of 13.
Definitely one to short. As usual E &OE, DYOR, etc.
You are right I can't directly source this assertion since the AR doesn't break this out.
However for the whole business their gross margin was 19.3% and their net margin 2.2%. Given the much higher margins of semi-captive insurance sales combined with very thin margins on white good sales even 6.5% of revenue could see the majority of the ebit due to insurance sales not white goods. If they don't break this out in the AR then I doubt they will reveal their individual margins on enquiry.
I don't think they are a bad company. Just that like all companies without a sustainable competitive advantage the benefits will accue to consumers not to the providers of capital (or by extension speculators in secondary capital.) ie. The washing machines are a much better deal than the shares.
VCT have their results today too, with Ex-Dividend on 5/2/15 giving a special Dividend of 50p together with final Dividend of 33.76p. They say "It re enforces our continued confidence in the company". Profits up @ 102.7M.
With the share price at almost £20.00, I make that a healthy 4.4% Dividend to come. Margins are a tad down & the company appears to be to be a bit overvalued.
VCT got a mention at Mellow in November and is up 7.3% today on the news.
Yes, Treatt (LON:TET). The figures and balance sheet look OK to me but I'd welcome your view, Paul. The warning about relocation costs puts a damper on the future, though.
So refreshing to see the accounts of an AIM company like Zytronic (LON:ZYT) ! Last year's figure have not been redesigned, adjusted EPS is the same as basic EPS, potential dilution is virtually none. Free cash flow after all investing spend is higher than reported profit, and capex is significantly lower than depreciation. And it's growing on the top of that. What else could you ask for?
Any opinion on Treatt when you get back from your meetings?
Hi Paul
Many thanks for your breath of sanity in the crazy turmoil of investment thinking.
I'm still thinking about your comments on Friday. Small caps are doing really badly. But so are growth stocks and (more surprisingly) quality stocks. I the last6 months all the Stockopedia quality screens have underperformance the FTSE100. And the screen of screens is down more than 10% vs lee than 3% for the FTSE. Can this make sense? Is it just a correction after such a good run last year? And how do you handle it? Do you try to be tactical, pull out of small caps and quality stocks until they are rising again? Or do you simply trust the soundness of your analysis and wait for the market to catch up with you when the quality business turn I good results?
Greetings to you
Julian
What I find most surprising about the recent rise in AO World (LON:AO.) is that it's accompanied by a big drop off in broker forecast EPS (incl. house broker.) Usually for these 'growth' companies the brokers are always optimistic as they are after the Investment Banking business, they won't reduce their forecasts for fear of annoying the company and then at some point there's a big miss and the shares take a bath. In this case the brokers are reducing their EPS in advance yet the shares keep rising. Could be momentum buys but while the 1-3m momentum is strong the 1 year is weak. Based on this info the smart-beta funds would typically be short not long. Sometimes when there is a universal agreement that a stock is a terrible investment it actually rises since their is no one left to sell and shorts have to buy however in this case the FCA disclosures show at most modest shorts c3%.
So it's a mystery to me. Can't last forever though - they will need to either deliver high growth at good margins at some point in the future (i.e. after 2016 where the house broker has just downgraded) or the company will trade at a more reasonable market cap.
Also given that they are really an insurance company with a sideline in selling white goods their 2014 AR lists insurance mis-selling as a risk. The auditor reviewed their sales process and signed this off but I'm wondering if anyone has got any first-hand experience of their sales process? Does it feel like they are providing a genuinely desired insurance service to customers or are they a team pushy sales people on commission who care only about closing a deal? With businesses in risky areas the culture of the business matters a lot in managing those risks.
As you've asked, I recently had a new kitchen installed including new oven, hob, dishwasher and fridge. Can't fault AO - best prices I could find and excellent delivery service. As I'd ordered so much they even took away extra old items free of charge which saved me recycling costs/hassle.
They did call a week or so later to offer extended warranty but I can't say they were overly pushy and they accepted that I was happy to rely on the extended 2 year warranty that the goods came with anyway. As a result of registering all the units online I was also offered extended warranties by Domestic & General, which were cheaper than those later offered by AO.
If they are relying on sales of extended warranties to meet profit targets then I'd be worried.
"If they are relying on sales of extended warranties to meet profit targets then I'd be worried."
I find it irritating too, but then it's pretty much universal in online retail (and some offline as well). In the age of comparison engines, lots of consumer businesses have to make their profit on high margin non-competitive add-ons. It's true of low-cost airlines (in-flight sales, luggage fees or seat choice fees, cross sales), hotels (£20 breakfast), electronics (extended guarantees), cars (poor value in-house credit deals), phones (roaming fees), etc. All of these would barely break even, if that, if consumers stopped buying the add-ons....
Hi dangersimpson -
"Also given that they are really an insurance company with a sideline in selling white goods..."
I was surprised by this statement so decided to check. The admission document apparently states FY2013 revenues of £17.9m from the sale of warranties out of £275m in total revenues. I say apparently because I picked this up from press reports and cannot find it directly in the document. Neither is it given in the latest interims, So that's only 6.5%. Granted that warranty sales are growing faster than the sales of white goods, they would still take some years before they reach double figures as % of total revenues. Happy to be corrected.
Percentage of profit may be more relevant here. The percentage of revenue will always be relatively small, but it may be where all the profit comes from. E.g. a company in such a sector with a 5% gross margin may make it by having a 50% margin on add-ons representing 10% of revenue, and doing the core business that is 90% of revenue at cost (zero margin). So a weakness in add-on sales can have an impact disproportionate with the percentage of revenue they represent.
The profit margins are higher than core, because that's the very point of the add-on: you attack the customer at a moment of weakness, when it's hard for them to make a market-based decision, unlike the core product who is often hyper-competitive. Indeed in a market where the major players make their money from add-ons the equilibrium price of the core product is cost or below.
Hi Paul
Welcome back. You haven't reported back on the poker in LV. Was it profitable?
Thanks for a great article. I am a rank amateur (compared to you anyway) but I am continually perplexed as to why people would invest in the likes of ASOS (LON:ASC) £AO Naibu Global International Co (LON:NBU) etc. After all all the do is sell underwear, washing machines and trainers (and in the laters case they may not even do that) If we had never had the tech boom (and bust) of 1999 one might understand it but for history to repeat itself so quickly is extraordinary. Even the likes of Standard Life has a 4,1m shares. All right small beer for SL but still £112m is £112m.
Paul any chance you could look at ESR and/or OMG and new listing IMI Mobile?
What did people make of the HY results by iomart (LON:IOM) this morning? I thought the headlines looked good at an initial glance, although they have been massaged somewhat. Fall in share price looks overdone to me (down by around 20% this morning).
I think the outlook statement was pretty vague, and the disparity between statutory EPS (4.25p) and adjusted EPS 6.15 has contributed to the fall. Broker consensus forecasts projected EPS of 13.1 for 2015, so if you take the adjusted EPS figure they are on course to deliver. However, based on statutory EPS for the full year, the current PER looks stretched.
Also whilst the overall headlines look good, it appears the majority of growth in revenues has come from Redstation Limited and BTL which were both acquisitions in 2013. Organic growth equated to an increase of 8% in revenues, which isn't as impressive and probably the reason why the SP has taken a hit.
I have no position in the stock, but am just trying to understand what caused the fall this morning, as it's been on my watchlist for some time. Would be interested to get the views of any holders of the stock.
Incadea (LON:INCA) notified the market that Dealertrak of the US is interested in taking them over. There is no certainty and no potential share purchase price but the stock has rocketed up.
I have taken the opportunity to bank half my holding at a good profit, but I would be interested to know Paul if you have any guidelines for yourself when this kind risk/opportunity arises.
Hi Paul
I know this is way outside your remit here, but do you fancy commenting on the continued turmoil in the retail sector, and the assault on the oilers? You have mentioned both before, and I am sure I am not alone in valuing anything you have to say on those topics. { I understand Santa has been gored to death by one of his reindeer, hence the lack of the relevant rally to date! Darn you Blitzen!).
Paul, It lifts my day to read that you get great pleasure from a balance sheet!!! Very best and a happy Xmas (bit early for me but everyone else is saying it at the moment.
RE. ZYT. Yes, impressive figures. Worth noting that FCF, Free Cash Flow, has increased significantly from £2.7m to £3.7m , a growth rate of 37%. Plenty of firepower for acquisitions.