Small Cap Value Report (10 Mar 2015) -MNZS, SNX, ITQ, BEG, GOAL, SIV

APOLOGIES - I'VE MESSED UP THE FORMATTING.
It took ages to get it back, so I daren't tinker with it any more & lose everything again.
Good
morning! Apologies for my outage yesterday - I wrote up a report
yesterday evening, so here
is the link for
that, where I reported on news
from: Tungsten (LON:TUNG), Maintel
Holdings (LON:MAI), Transense
Technologies (LON:TRT), Escher
Group (LON:ESCH), Clarkson (LON:CKN)
Lots
of results today, so this report will probably take me most of today,
therefore please refresh the page every now & then.
John
Menzies (LON:MNZS)
Share
price: 388p
No. shares: 61.3m
Market
Cap: £237.8m
Final
results -
for calendar 2014 are out today. They're not very good, although that
was expected since the company issued a profit warning on 5 Nov 2014,
which I
reported on here,
when problems arose at its aviation division.
Then
on 16 Jan 2015 the company put out an in line with (reduced)
expectations trading statement.
Here
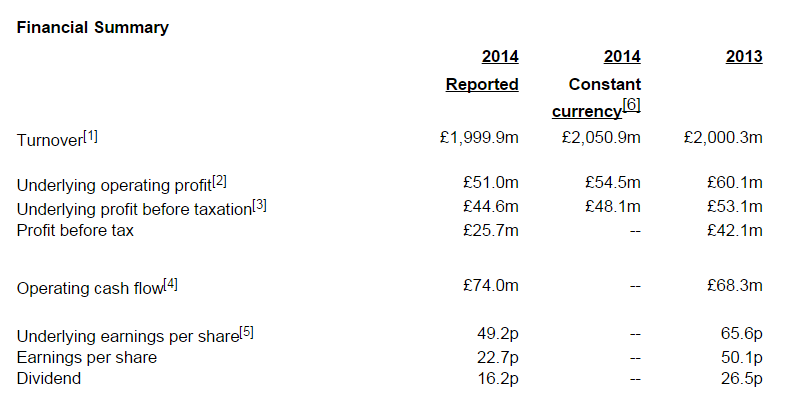
are the financial highlights for the 2014 results;
Points
to note;
It's
a high turnover, low margin business (operating margin only 2.6%),
so should be cheap.
Underlying
EPS of 49.2p is a whisker below forecast of 49.9p, so that's OK.
Dividend
cut - as I predicted in my last two reports, the dividends looked
unsustainable, and have (sensibly) been cut by 39% to 16.2p for the
year - a yield of 4.2% now.
Balance
Sheet -
there are a number of issues, and overall I describe the balance
sheet as weak. The company claims to have a strong financial
position, which just isn't true, so it's really annoying to see them
repeating that claim today. If the financial position was strong,
they wouldn't have cut the dividend, would they?!
Net
assets of £69.7m become -£46.4m when you write off the £116.1m
intangible assets. Anything below zero NTAV is a red flag for me.
Current
ratio is 1.0, which is low (I look for at least 1.2, and preferably
1.5+)
Debt
is a little higher than I am comfortable with, at £143.6m, although
this is partially offset by cash of £32.8m, giving net debt of
£110.8m.
Capex
- the business looks fairly capital-intensive, with £28.1m being
spent on capex in 2014, and total property, plant & equipment
having a NBV of £120.1m.
Pension
deficit - as you would expect, this has got worse, with £59.0m
showing on the balance sheet, although the imminent triennial
actuarial valuation for 31 Mar 2015 will no doubt be considerably
worse. The overpayments are considerable, at c.£13-14m p.a.
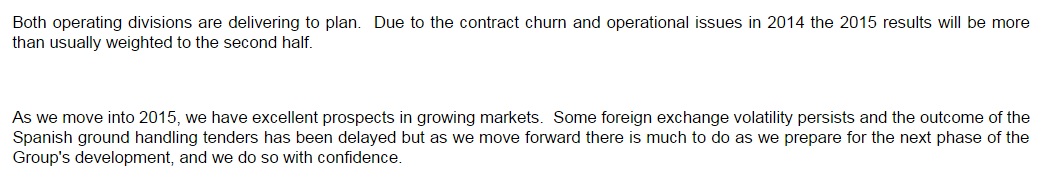
Outlook -
the H2-weighted year comments for 2015 worry me - that's usually a
deferred profit warning;
My
opinion -
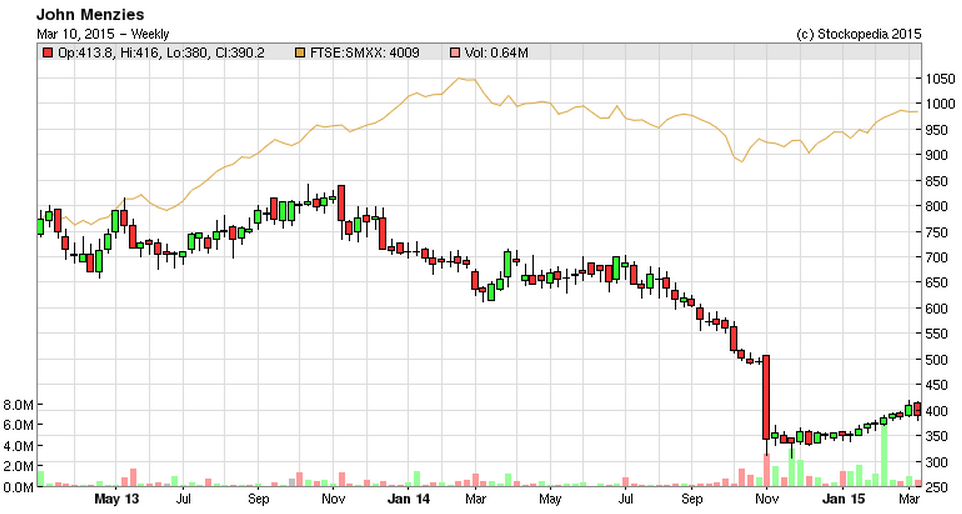
at 388p per share, with 2015 EPS forecast at 50.8p, the current year
estimated PER is 7.6. Whilst that might look cheap at first sight,
once you factor in the pension deficit payments, and consider net
debt, together with lacklustre performance in low margin and
ex-growth activities, it's difficult to see much appeal here.
The
dividend was yielding about 7%, but that was clearly unsustainable
(anything over 6% usually is), and with the divis now cut to an
unremarkable yield of 4.2%, it has less appeal for income seekers
too.
Overall,
I can't see anything appealing here.
Synectics (LON:SNX)
Share
price: 138p
No. shares: 17.8m
Market
Cap: £24.6m
Final
results -
for the year ended 30 Nov 2014. As expected, these are bad - the
company warned on profits last year, due to its biggest sector being
selling CCTV systems to the oil & gas sector, which has obviously
seen big cutbacks when the price of oil plunged.
The
company put out a profit warning on 27 Oct 2014, which I
reported on here.
Although without wishing to sound too smug, I also warned readers
earlier than that, on 29 Jul 2014 that the interim figures didn't
look right - in particular the very large debtor balance was a
big red flag. So it went on my bargepole
list on
that day at 335p per share. It's down 59% since then, which just
shows that checking the balance sheet for reasonableness is
worthwhile.
Here
are the highlights from today's results;
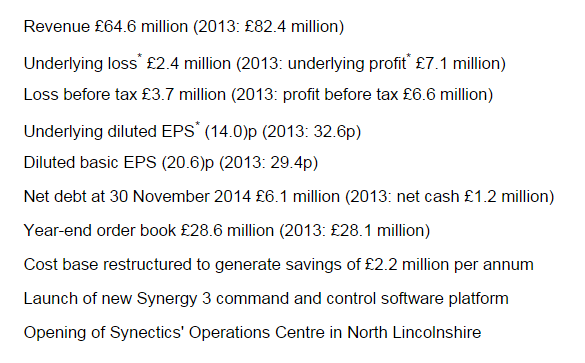
The
swing from net cash to net debt particularly worries me. Banks don't
like funding losses, so things could get sticky there if the company
cannot fairly quickly demonstrate an improvement in trading.
It
looks like they are roughly at breakeven on an underlying basis,
after reducing the cost base by £2.2m p.a.
Balance
Sheet -
this is still a big area of concern to me, and I'm seeing red flags
within current assets. In particular, whilst turnover has fallen from
£82.4m in 2013 to £64.6m in 2014, the debtors figure on the balance
sheet has only dropped a little, from £27.7m to £25.6m. That looks
way too high to me. To my mind, an acceptable level of debtors would
be about two months turnover, maybe three months at a push (to allow
for VAT). So three months turnover is £16.2m. The actual debtors
figure is £25.6m, so £9.4m more than what I consider to be
reasonable. Therefore getting a breakdown of what is in debtors, and
what the aging of those debtors is, would be imperative.
Similarly,
inventories should have gone down, but has actually gone up from
£9.7m last year, to £12.6m this year. Again, that doesn't make
sense, when turnover has fallen considerably, to be holding more
inventories.
It
all suggests to me that there could possibly be lots of junk on
the balance sheet, which might need to be written off, giving rise to
a further (and large) potential loss. These seem to be
preliminary, rather than audited results, so I hope the auditors have
spotted the red flags of high inventories & debtors, and will be
looking closely at those areas.
My
opinion -
if the figures don't look right, then I don't invest. These figures
don't look right, so it's staying on my bargepole list. It's high
risk, with bank debt having shot up, and the company being
loss-making. On the other hand, if they can recover to previous
levels of sales & profits, then all would be well. Shareholders
should probably be prepared for being asked to stump up more cash, as
the bank may not be prepared to continue funding any further losses.
Interquest (LON:ITQ)
Share
price: 96.5p
No. shares: 35.2m
Market
Cap: £34.0m
Audited
results -
for calendar 2014 are out today. They look strikingly good, with
adjusted PBT up 96% to £4.5m. However, checking back to my
notes here from 8 Jan 2015,
that is in line with the trading statement released on that day. So
no surprises here, just in line results.
The
big jump in profitability seems to have come from an acquisition made
in late 2013.
My
opinion -
overall it looks OK. The PER is just under 11, which is about
right for a staffing company, there are lots on AIM at valuations
typically of a PER between 8 and 12.
The
balance sheet isn't great, relying on bank debt to part-finance the
debtor book, but again that's normal in this sector.
Net
tangible assets work out at only £2.6m, rather weak.
If
you recall, this is the group that put itself up for sale last year,
but nothing came of it. It's probably priced about right for the time
being.
Begbies
Traynor (LON:BEG)
Q3
trading update -
profitability, and net debt, are said to be in line with
expectations.
Goals
Soccer Centres (LON:GOAL)
Final
results -
for calendar 2014, show flat operating profit, but an improvement in
profit before tax due to a lower financing charge. It's a nice enough
business, but where's the growth? A 1% increase in underlying EPS to
14.5p is hardly worth writing home about. At 226p, the shares don't
look good value on a PER of 15.6, given the lack of growth, and the
still significant level of debt (although that looks under control
now, having been excessive in the past).
Overall,
I'd say the price is a tad on the high side. Current trading so far
in 2015 has been flat against last year.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

10 comments
re SIV, think Paul would have probably given it a miss due to its weak balance sheet as follows,
current ratio = 0.64, test failed for current ratio, negative ntav of £41M, coupled with a small rise in net debt would prob mean Paul not wanting to commit to it as an investment.
As a side, hope you are OK Paul, and that your breakfast Demon hasn't returned, if it has get well soon!
regards
mrwhits.
no position in SIV.
Think you have posted yesterdays write up instead of todays Paul.
Hi, sorry I had absolutely massive technical issues, when adding a section on ST Ives (LON:SIV) - it disappeared 3 times, then totally screwed up the whole report. I couldn't retrieve it, so just fixed things as best I could.
St Ives - yes it was the balance sheet that put me off, from memory.
Regards, Paul.
Hi Paul,
Just wondered if you had time to review the Stadium (LON:SDM) results? I know there's a pension deficit but this looks to be a company that is following the likes of Tracsys and Judges Scientific and making sensible add-on acquisitions which add value and increase margins.
Hi Paul
Did you cover the ST Ives (LON:SIV) interims? The header contains the ticker but I can't see this covered in the actual report (I may have missed it due to the formatting issues). The only mention of SIV I can see is from fellow Stocko subscribers.
Best wishes,
Imran.
Hello Paul,
I hope you make it through to Airea (AIEA) H1 results. The format is straightforward and the results are quite promising. I guess that the pension deficit and the microcap size cause the current sp to be so far below TNAV. cheers, Mark ( disclosure I am long and looking on iii appear to be the only to buy any shares this morning which is something of a novelty for me!)
Lots to dislike in SIV's restatements, non-recurring items, pension debts, but I did just check their net debt as at the last reporting date and it was £42.7mn, so no naughtiness there. Their pension scheme has liabilities and assets of around £300mn, and has been closed to new members since 2002 (note 29 of last year's annual report). The continuing 'exceptional' payments and non-cash revaluation into it are frustrating, but not the real problem with St Ives, I think. What I really have been shocked with is the amount of non-underlying costs excluded from their presentation of their results, including redundancies, empty building costs, amortisation of acquired intangibles, impairment of goodwill, contingent consideration required to be treated as remuneration, etc. You get the picture. Let's book all the good stuff as revenues, and anything we got wrong let's stuff into non-underlying. What is frustrating is that 'underlying' all of this there may be an interesting company trying to get out, as it reduces its old book printing business to 20% of sales, and focuses on higher growth areas of digital marketing.
As I read the half-year results the net debt at 31st January 2014 was £42.7m and the net debt at 2nd August 2014 was £43m. My concern is why the net debt is not stated on a comparable basis i.e. at 31st January 2015. There may or may not be naughtiness, but it seems very odd.
Paul, if you do have time to report on SIV, I would appreciate your views on the fact that net debt is reported as at 2nd August 2014 and not at the half-year end. The ballooning pension liability probably rules it out anyway for me, and the amount of net debt compared with profit/earnings doesn't encourge me either - yet they go on paying an increasing and above-average dividend.
Any views on the half-year report from ST Ives (LON:SIV) ?