Small Cap Value Report (11 Jan 2016) - BRY, PHD, BOTB, GVC, ALY

Good morning!
China fell again overnight, but the US futures seem to be firming up, at least for now anyway. Doing a lot of reading over the weekend, it seems to me that the US markets are pricing-in a soft patch in the US economy, and possible spillover from the Chinese economy also slowing. Therefore, unless the forward-looking economic data improves, then this time "buying the dip" would possibly be the wrong thing to do.
Combine that with main US Index charts which look very much like they have topped out, and are now in a bear market. So my conclusion is that this is probably a time to be relatively cautious - it's not a good time to be using gearing, and probably sensible to get rid of low conviction positions, to raise cash for better bargains that might appear if people start throwing out the babies with the bathwater.
Although as most of my positions are reasonably priced things that I have confidence in, my long term portfolio remains unchanged.
CEO Interviews
I've just published the transcript of my interview with the CEO of Brady (LON:BRY) (I hold a long position in this share) on my website here. Reading it again, I think the CEO gave reasonable answers to my questions, and took the criticism (of the profit warning) on the chin. It's good to find a CEO who is prepared to face the music after a disappointment, and doesn't just want to talk to investors in the good times. That particular interview was done because the company approached me, and asked for a "right to reply", following my sharply critical comments in these reports.
People seem to like these interviews, so I'm doing more. Later this week there are 2 new interviews lined up, so please submit your questions using the links below (as that collates the questions into one place). Please don't put questions in the comments section below this article, as they just get lost.
Proactis Holdings (LON:PHD) interview, morning of 14 Jan 2016 - an interesting & growing group, specialising in cost control software. Your questions here please.
Best Of Best (LON:BOTB) interview, afternoon of 15 Jan 2016 - long-established supercar competition company - originally in airports, but now increasingly via internet - questions here please.
(I hold long positions in both these companies)
Home Retail (LON:HOME)
(at the time of writing, I hold a long position in this share)
Sainsburys deal? - I've been amazed/dismayed at the generally short-sighted, and ill-researched commentary on this company in the blogosphere, mainstream press, and from city analysts, re the potential takeover from J Sainsbury (LON:SBRY) . Unlike most, I immediately saw the logic of such a business combination, and it's clear from the SBRY announcement that they are committed to doing a deal if they can.
Retailing is changing rapidly, and it's now all about combining conventional stores with efficient internet selling & logistics - in particular (see John Lewis's last update) the crucial importance of click & collect, and Argos is also trying to establish a ground-breaking national same-day delivery service. Customers are tired of poor delivery, with those annoying cards put through the letterbox, with all the associated hassle. Things are moving on, and Argos is up there in the right place with click & collect, and same-day delivery.
Argos is turning into a hybrid retailer & logistics company - e.g. Ebay sellers can use Argos stores (at no extra charge) as a collection point. The idea is to focus consumers on using Argos stores as their main local hub to collect items from. Combining that with Sainsburys stores, which already have high footfall, is a brilliant idea - using surplus space, and there will be numerous cost and efficiency gains. I seem to be one of very few commentators/analysts who actually "gets it".
An article in the Sunday Mail yesterday suggested that a deal is likely to go ahead, at 155p+.
Personally I've banked most of my gains, as risk:reward is now looking finely balanced. I'd rather reassess after the trading update this Thursday. If that means missing out on some of the gains, so be it. The downside risk is that the TU is a stinker, and potential bidders walk away. Downside risk in that scenario is a share price of probably about half the current level - not a risk worth taking, in my view, for relatively modest upside.
Balance sheet - the other absolutely key point about Home Retail (LON:HOME) which almost all commentators have completely overlooked, is its enormous balance sheet strength. This was core to my bullish view of the company, indeed I saw takeover approaches coming, and flagged the likelihood of bid(s) for HOME late last year.
HOME has net cash, and a huge (over £500m) storecard debtor book, with no associated debt. These are forecast (combined) to be c.£800m. So a bid at say £1.2bn for the group, would actually only have a cash outlay for the bidder of £400m! It's an absolute steal at that price, for the UK's 2nd or 3rd largest internet retailer, and with Homebase thrown in for free, which could be sold on to PE.
Sure, Argos has problems, but nothing that can't be fixed. It's digitally focussed, and doing all the right things, in terms of where retailing is going in the future. In my view a combination of Sainsburys and Argos is a very good proposition, and would, given time, enhance the value of both businesses.
In particular, Argos stores have relatively short leases remaining - apparently half of its stores have leases up for expiry (or break clauses) in the next 5 years. So there is a big opportunity to relocate some Argos branches into the largest SBRY stores, thus cutting costs. Also SBRY could do all its non-food buying through Argos's existing buying department.
Although it's Argos's logistics and IT capabilities that SBRY wants the most. I've heard that from a senior former employee at SBRY's HQ.
Shorters - HOME was one of the most heavily shorted shares in the UK market, with about 8.5% of the company having been shorted. This made me salivate, when going long of the share, because I knew my analysis was correct, so having a large group of forced buyers would catapult the share price higher once bidding interest in the company emerged. That's exactly what happened.
It's been glorious to see shorters, who got it completely wrong, running for cover - in particular after Crispin Odey's haughty & snobbish comments last year about Argos being no good, because it was too working-class! How ridiculous. So karma has taught him a lesson hopefully, with a multi-million loss.
Most of the time shorters do better research, and are very often right about bad companies, but they also sometimes get it wrong. When they are wrong, shorters are the investor's best friend, as they become forced buyers to cover their shorts once the newsflow has turned positive. So you can just sit back, relax, and watch the money roll in to you, as they drive the share price back up again. They have to keep buying even if they don't want to. Very enjoyable.
Let's turn to today's company news next.
SkyePharma (LON:SKP)
Share price: 408p (up 4% today)
No. shares: 104.8m
Market cap: £427.6m
(at the time of writing, I hold a long position in this share)
Trading update - relating to the year ended 31 Dec 2015. This reads positively;
Full year revenues for 2015 are anticipated to be ahead of the Board's previous expectations announced on 26 November 2015, primarily because the Group's license partner, Mundipharma, has agreed that the first flutiform® sales milestone of €10 million (£7.4 million) will now be recorded in 2015. This will be through the release of deferred income and no cash will be received as it will be used to meet a large part of the balance of Mundipharma's right to recover up to €25 million (£17.6 million) of previous development costs, as already disclosed.
The Group's cash and cash equivalents as at 31 December 2015 was approximately £41 million and net cash was approximately £35 million. Cash generation in the second half of the year benefited from both a robust operating performance and the later timing of payments for capex projects, which remain on track.
The above only mentions sales being ahead of expectations, but no mention of profits.
FinnCap have said this morning that their forecasts are likely to be on the low side, and are being reviewed. So it looks as if earnings estimates are more likely to go up than down.
Valuation - with a strong balance sheet, and good growth, the valuation doesn't look particularly demanding to me, despite the strong share price rises recently. Note the excellent quality scores below too. I wonder if my friend Leon Boros would see this as a QARP.
Note also that Stockopedia's black boxes like it too, with a StockRank of 85.
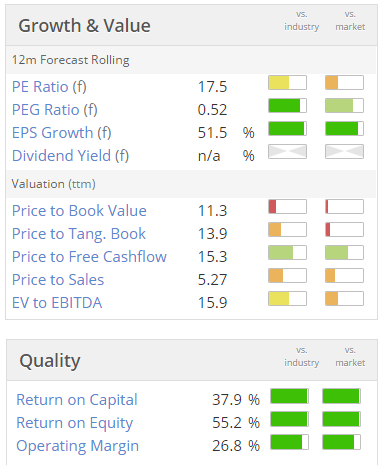
My opinion - obviously I like it, having a long position in the share. I wonder if a takeover bid might be the eventual outcome here, as tends to be the case with successful drug companies. It's not a sector I know or understand, but SKP is relatively easy to research, since you can value it on a conventional basis, on an earnings multiple.
So it gets a thumbs up from me.
GVC Holdings (LON:GVC)
Share price: 470p (up 0.1% today)
No. shares: 61.3m
Market cap: £288.1m
Trading update - this gambling company reports what look like strong figures for Q4. Of particular note is that the 10% rise in Net Gaming Revenue ("NGR") was despite a big currency headwind - the figure in constant currency was up 21.3%.
I am assuming these increases are organic, because no mention is made of acquisitions, but that is worth double-checking.
The Directorspeak sounds upbeat;
"I am delighted to report yet another set of strong numbers as 2015 year ended very positively for GVC. The Board and I would like to thank all our staff for their hard work and continued focus. With the shareholders of both GVC and bwin.party digital entertainment plc ("bwin.party") having voted overwhelmingly for the acquisition of bwin.party on 15 December 2015 and with completion expected on 1 February 2016, and the enlarged GVC Group expected to be admitted to the Main Market on 2 February 2016, we are enthusiastic to commence the integration of the businesses and to continue to drive shareholder value for investors in the enlarged Group."
Annoyingly though, no mention is made of profits versus market expectations - which is a glaring omission, as that's the most important aspect of trading updates. So we can only assume that the results will be in line, or perhaps a bit ahead?
My opinion - I don't really have one, as am not up to speed on the numbers for this company. Any meaningful analysis would need to look into the acquisition of bwin.party in detail, as this is a highly material acquisition, which will make the group much larger.
So far, so good though - the shares have 4-5 bagged in the last 5 years, and paid juicy dividends on top. There used to be a huge dividend yield here, but this is now showing as down to 3.1%.
Also, just to flag that you have to be very careful about regulatory and tax issues, with this type of company, which is why these days I tend to steer clear of the online gaming sector. Why complicate life?
Laura Ashley Holdings (LON:ALY)
Share price: 26.25p (down 1.9% today)
No. shares: 727.8m
Market cap: £191.0m
(at the time of writing, I hold a long position in this share)
Laura Ashley Australia - I'm surprised the listed company has been so slow to announce this news to the market, even though it's not material to results overall, and will probably be presented as an exceptional item.
The Australian franchisee has gone bust;
The Company has been made aware that its license partner in Australia has been placed into voluntary administration. Laura Ashley has an exposure of circa. £1.2 million and is continuing its discussions with the administrator regarding the future of the Australian operations.
There is no effect on the rest of the Laura Ashley business.
What is surprising is that it has taken several days for the company to announce this, as it was in the press in the middle of last week. Indeed, 4 days ago the following Twitter exchange began, where I correctly estimated the likely range of the bad debt, after several of us had picked up from the Australian press that Laura Ashley Australia had gone bust;
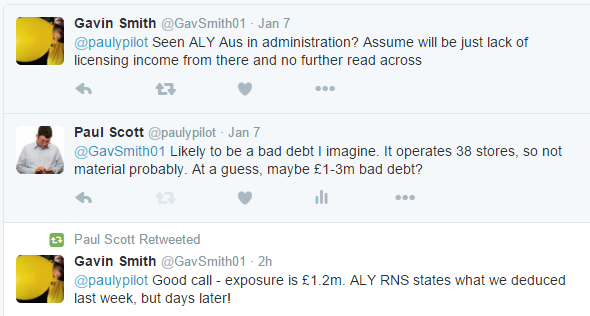
This is an interesting point - that as investors, we can get ahead of market announcements simply by monitoring the press, and the internet generally. Automatic Google searches are useful for this - I have several set up for companies which are my biggest holdings, and I get an email every morning showing anything relating to that company that Google has found.
If it's publicly available information, out there on the internet, then you're not insider trading, you've just got hold of useful information from an alternative public source than the company itself.
In this case, this information really shouldn't affect the overall valuation of the company very much at all, indeed any move should have happened last week. When you're sharing a profit margin with a licensing or franchisee partner, unfortunately there will be the occasional bad debt.
Generally speaking, I try to widen my sources of information, and not just rely on company announcements. Third party information is often more useful than what the company itself tells us (which will nearly always be skewed to the positive).
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

20 comments
I know nothing about the management that's not in the public domain; although they are clearly good at looking after themselves, shareholders have always done well too. The info in the Standard article is already well known, he's been attempting to undermine the bwin deal from the start, presumably because it brought his discussions to an end.I'd be more impressed with his legal case if there were less badmouthing to the press. I can't imagine it being easy to get the better of Alexander in negotiations and I certainly wouldn't be doing anything major for him without a watertight contract.
My knowledge of GVC Holdings (LON:GVC) management (and to a very much lesser extent the industry) makes them uninvestable to me and they are on my bargepole list.
Wow! Pretty strong stuff Purpleski
- By 'my knowledge' is that knowledge known only to you, or knowledge already in the public domain?
Re. Sainsbury bid for Argos. I must say I am skeptical of the strategic rationale put forward by Sainsbury for their proposed bid. More so after listening to Lex of FT.com in the following video clip.
http://www.ft.com/cms/s/0/1181aab0-b3b3-11e5-8358-9a82b43f6b2f.html#axzz3wxXgVQh4
Paul, I would like to agree with you re Sainsbury and Home Retail, but then we would both be wrong. As a Sainsbury shareholder (of short standing), the last thiing I would want them to do is to take on a business that is of poor quality and will require very substantial restructuring at this point in time. It could be a massive management diversion and the fact that it looks cheap on a balance sheet basis does not convince me. The best quote I saw on this topic was this: "Its list of deal benefits appears to have flowed from the pen of an investment banker who has not been in Argos for a while or ever”….Tony Shiret of Haitong Research. As regards the benefit of their loan book, well financing that has been a drain on their cash flow of late. Are they a retailer or a finance company? They should have made their mind up on that. Retailers don't need to run finance businesses.
There are alternatives to "click and collect" to those who can't stay in for deliveries (and I don't mean Amazon drones). It has always seemed to me that click and collect was an intermediate stop-gap offering to try and counter on-line only retailers, but it could be a dying mode. The integration of Sainsbury and Argos looks a real nightmare even if they got shot of Homebase et al - different customer profiles, different stores, etc, etc. Now if this was an "asset stripping" job (come back from the dead please Jim Slater), then it might make sense, but....
Ignoring my initial witticism, I will remain open minded until I see the full justification from Sainsbury's management, but just getting Home Retail on the cheap will not be sufficient. I think a lot of Sainsbury's shareholders will take a lot of convincing.
"...as am not up to speed on the numbers for this company. ( GVC Holdings (LON:GVC) ) Any meaningful analysis would need to look into the acquisition of bwin.party in detail....and paid juicy dividends on top. There used to be a huge dividend yield here, but this is now showing as down to 3.1%. "
Fair enough Paul, but the 3.1% divi yield you refer to I assume must be referring to Bwin - as GVC's divi yield has generally been circa 7%/ 8%/ 9% for years. (Indeed GVC's PE and yield% have been virtually interchangeable in that time with both being high single digits.
(GVC's divi is suspended for 2016 in order to digest the Bwin acquisition).
Comment out on GVC earlier today...
"Jim Armitage: GVC’s full market listing should also mean full disclosure"
A few under hand tactics if true it has to be said.
http://www.standard.co.uk/business/jim-armitage-gvc-s-full-market-listing-should-also-mean-full-disclosure-a3153581.html?
What a truly brilliant post and analysis of Home Retail (LON:HOME) (I dont't/didn't hold). Thank you. If Home Retail (LON:HOME) shareholders read your posts they may hold out a for higher price!!
Laura Ash Ownership and management good reasons to avoid it.
Interesting comments on HOME and SBRY Paul, and congratulations on the gains! One of my concerns is that macro conditions persist in food retail, as the price gap to discounters is still c20% or so I believe. And while Sainsbury's is fighting that battle, Amazon could use its scale to erode margins in HOME's market (AMZN is also increasingly in the food retail market with its nascent Pantry service).
That said, now the dust is settling the move looks to make much more sense. While the Amazon threat will never go away, Argos stores these days are clearly changing for the better (having been in one at the weekend and seeing the improvements over a period of months). The acquisition would be immediately balance sheet-enhancing for SBRY (which is becoming more and more of a concern for the group these days). Also 40% of Argos' leases expire in the next four years, so it stands to improve property prospects, balance sheet, and logistics.
Sainsbury's is also set to open another ten sites in its JV with Netto, so a few years down the line the group could have a discount JV, an expanded non-food offer, greater logistics and delivery systems, a strengthened balance sheet, and greater store flexibility. The group said it is optimistic that 2016 could be the turnaround year, but Asda and Waitrose are less optimistic and anticipate further margin erosion. At present, I'm minded to believe the latter but food retail is nothing if not surprising these days.
We'll all know a lot more by the end of this week, what with SBRY, MRW, TSCO, and BOK all releasing updates and Kantar and Nielsen releasing grocery market data.
One concern is that Sainsbury's has a job on its hands convincing its own shareholders, as much as Home Retail's (in fact possibly more so, as HOME's biggest shareholders, Old Mutual, Toscafund, and Schroders, are keen to restart talks). QIA is a 25.1% shareholder in SBRY and has reservations.
Cheers
Hi Paul, agree with your analysis re HOME, but other sunday newspapers were keen to point out that a deal would have to be at at least 200 p per share. There are people at SBRY who know HOME and Argos in particular inside out, so they know if it will work or not. I can't see them calling it a day at the first strike.
If you are a food retailer and you want to grow, how else do you do it? You need to move with the times as well, so click and collect and good distrubution is what you need. But you are then up against Amazon, so it has got to be good.
I think there are two concerns, firstly do both sets of customers fit ie Argos and Sainsburys? I shop at Sainsbury's and Argos, so for me it works but then again I will go into Aldi and Lidl from time to time.
Second, any takeover and integration will take management time and so may divert them from the core business of food sales.
I would prefer Argos as a bolt on as opposed to a clothes retailer, like M and S has.
Herbie -think you need to look at your post again. Take it you mean disposal? Do you mean the disposal is low ball on price and therefore not good for Cambria or t'other way round? They seem to have a good track record on buying/selling these various dealerships.
Yes sorry I typing as rushing out, yes I meant the disposal looks cheap, £1.3m for £0.5m profit pa and £20m revenue.
The Telit Communications (LON:TCM) update seems positive and detailed, though they quote "adjusted EBITDA" which is a useless number. They are in a strong sector at present, providing telecoms products to connected vehicles, machine-to-machine communications and the "internet of things". They forecast double digit growth in 2016. I have just bought 10K.
Paul, if you have a chance Telit Communications (LON:TCM) trading update was out today. Also Cambria Automobiles (LON:CAMB) have been buying and selling dealerships, market seems to like it but the disposable looks cheap to me.
News reports suggest that Laura Ashley Australia (LAA) will continue to trade; that it is possible that some individual stores will close whilst the others may remain open as a going concern. It would also appear that the sole director of LAA got into severe difficulties with another business that was somehow linked with LAA.
The exposure that Laura Ashley Holdings (LON:ALY) plc has stated would therefore seem to be an unlikely worse case scenario... Will just have to wait and see on that.
http://www.stuff.co.nz/business/industries/75709665/home-and-fashion-brand-laura-ashley-australia-in-administration
Hi Paul -
my formula for a good night's sleep when it comes to investing, is as follows:
- I have around 70% of my portfolio in solid FTSE100 shares which are really long term holdings, a la Warren Buffett. They provide steady growth with steady dividends. For these I really couldn't care less about market corrections. The only thing I watch out for is a potential market crash, which to me means a potential 40%+ drop.
- the other 30% is for trading/ investing from a few days to a few months. Relatively quick turns in short cycles is fine by me. Again I react to market gyrations/ corrections purely by way of lengthening or shortening my (time & money) exposure within this short timeframe.
So with respect to long term, in my view 2016 presents very low probability of a major crash (not dismissing it entirely...). And for the short term trading or investing, I don't worry too much about Euro/ China/ oil/ US/ emerging markets/ debt bubble, etc.
Regards, Ram
Paul
Laura Ashley Holdings (LON:ALY) has just rushed out an RNS about its Australia partner entering administration. Exposure of £1.2m, "no effect on the rest of the business".
Hi Paul, I agree with you analysis on Home, everyone has focused on the retail side of the business and forgotten about the logistics, including UK same day delivery. I believe Homebase will be sold and a suitor is already lined up, making the deal easier as it's cash in the bank for the new owner.
I agree with that and would also emphasise the strength of the Argos buying team. As customers we focus on our buying experience, but the sourcing of the products in the first place is vital, especially when it comes to own label.
No-one mentions Habitat which Home Retail also own - I assume they would also be sold off?