Small Cap Value Report (11 Jan 2017 - Part 2) - FOXT, MCB, SGM

Hi everyone,
I'm back after a busy few days in London.
This report will cover Foxtons (LON:FOXT), McBride (LON:MCB) and Sigma Capital (LON:SGM).
Today's Part 1 by Paul is here, where he is covering Shoe Zone (LON:SHOE) and Joules (LON:JOUL).
Foxtons (LON:FOXT)
Share price: 95p (-4%)
No. shares: 275.1m
Market cap: £261m
Trading Update (for the year ended 31 December 2016)
Remarkably weak against comparatives:
Total group revenue for the year was
circa £133m (2015: £150m), with revenue for the quarter ended 31
December 2016 totalling circa £26m (2015: £35m).
As might be expected, the more cyclical, sales-driven revenue stream is responsible for the weakness, not lettings:
The reduction in Group revenue for the year reflects
the significant fall in sales volumes immediately following the first
quarter of 2016. In the final quarter of 2016, sales revenues were circa
£12m (2015: £20m) as volumes remained subdued. Lettings revenues in Q4
were circa £13m (2015: £13m) and have remained more resilient,
benefitting from our high levels of renewals despite lower levels of new
tenant activity and some downward pressure on rents arising from
increased stock availability.
The outlook statement for 2017 is quite bland, saying that at the current rate of sales activity, "it is likely that 2017 volumes will be below those in 2016". Indeed!
From the previous trading update, I note that Q3 sales revenues were down 34% on the previous year, whereas Q4 sales revenues are down 40%. So perhaps full-year 2017 sales revenues might end up c. 40% down on 2015, unless something changes?
The previous update remarked that the company remained "highly cash generative with no debt". Today's update changes the focus a little bit, mentioning EBITDA margin instead of cash generation. Although it again emphasises that the company remains debt-free.
My opinion: This is a great stock for a pub debate, if you're interested in the London property market (which quite a few people are, unsurprisingly!).
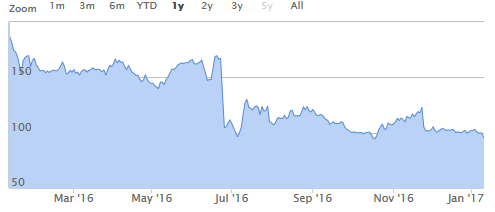
Something which I still find rather unsettling is how the company spent over £28 million on dividends and buybacks in H1 (more than 10% of the current market cap), just as conditions were deteriorating.
It's of course very difficult to predict the property market, but that was a rather significant mistiming from a company which should have an excellent vantage point from which to detect trends.
Worse still, the share buybacks were executed at an average price of 169p. My rule of thumb is that if the share price ever halves after a buyback, it was definitely a mistake. Let's see if we get there!
Sales were responsible for £23.5 million (about half) of Foxtons' profitability (adjusted EBITDA) last year. Assuming very tough conditions in that segment for the short-term (or the foreseeable future), which the company was not expecting, I would remain uncomfortable with the current market cap, as I was at the interims in July. Flexible costs will cushion the blow, at least.
McBride (LON:MCB)
No. shares: 182m
Market cap: £327m
Trading Update (for the six months ended 31 December 2016)
I will try to keep this brief, as the trading update is in-line:
The Group's first half year financial performance has been encouraging, with quality of earnings continuing to improve from further positive progress on margins and costs. As a result the Board remains comfortable that the business is on track to deliver its full year expectations for adjusted operating profit.
The company has sought to reduce complexity, and therefore deliberately reduce customers, to enable an increase in margins. In other words, it is behaving rationally!
So the 7% constant-currency revenue decline in this latest period has not spooked the market too much, since 2.5% of this is deliberate.
My opinion:
I always want to take a second look when I see a company acting responsibly and in the interests of shareholders - turning down business to improve margins and efficiency is often one of those actions. Too many management teams prioritise sales (vanity) instead of more important objectives.
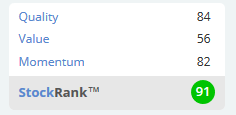
So when I read the management discussing a much-improved adjusted ROCE in their executive review of last year's results (to June 2016), I tend to think that it's probably an above-average management team. And with that measure rising to 24%, I tend to think that it's probably a better-than-average company, too.
The StockRank tends to agree with my suspicions:
I will stay reticent on the question of valuation, since net debt of £91 million, as of last year, looks rather on the high side.
Still, this could fit nicely within a portfolio of high-Stockrank shares (although please always remember to do your own research - as this is just my opinion, not investment advice).
Sigma Capital (LON:SGM)
Share price: 84.5p (+0.6%)No. shares: 88.7m
Market cap: £75m
Trading Update (for the year ended 31 December 2016)
A first look from the SCVR at this property and regeneration specialist, with focus on rental properties for families.
"Broadly in line" results are expected (this is sometimes interpreted as a slight miss, but the shares are up today regardless):
The Company continues to make encouraging progress
and results for the year are expected to be broadly in line with current
market expectations. This has been achieved without the benefit of the
launch of an additional phase of managed PRS before the year end and
reflects a better than expected performance from both Sigma's own
self-funded activities and its regeneration projects with local
authorities.
Outlook is good:
Prospects for the new financial year remain positive, with a substantial pipeline of qualified development opportunities and strong rental demand across the portfolios.
I see there was a sharp correction on September 30th, when the H1 report was released (on the last day permissible). This was due to the delays hinted at in the first paragraph above, leading to the company "materially rebasing management expectations
in the near term".
My opinion:
I'm not sure yet what the investment case is here. Net assets at June were reported to be £33.1 million, or 37.3p per share, though investors were willing to pay 75p per share in 2015 for the launch of the company's own PRS (private rental sector) portfolio.
PBT is forecast at £3.9 million this year. A few regeneration/development projects could see this figure multiply in 2017.
As I said with Watkin Jones (LON:WJG), there is a lot of variance when there are just a few projects - and the valuation needs to reflect this.
Therefore, adjusting for risk, the current share price might be annoyingly accurate.
On the subject of sectors, Paul and I may become more clearly-defined in terms of which ones we are each covering (although there will continue to be a strong element of overlap).
Paul is obviously very strong on retailers, while I am quite happy covering financials, insurers and property. So we might divide our coverage along broad lines such as this in future.
If you feel there are sectors or stocks which lack coverage, or if you have any other ideas, please don't hesitate to leave a message or send a comment!
Regards
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

29 comments
I've noticed that reports now seem to be formatted Date - Part I or II.
I'd find it simpler if it were Date - Paul or Date - Graham.
I don't mind what is included in them, or if you both write about the same company.
My main issue is that you would both write about what interests you.
Completeness is good, but not at the expense of obscuring the difference between writing what you are thinking from the thoughts that come to you when you force yourself to think about something that doesn't seem very interesting to you. Writing about what is interesting him has been one of the great strengths of Paul's column in the past. You don't want to get like an Investors Chronicle for small companies.
Thanks very much for the suggestions, all have been read and I will pass them on to Paul.
Hello Graham,
Thanks for the analysis.
I'm new here but I noticed one small thing that would be useful is if you and Paul could set the analysis hyperlinks to open in a new browser tab by default. Would make it easier to flick back and forth between the stockopedia analysis and your blogs.
Mike
Hello Graham,
Thanks for the article.
I don't think you need a formal division of responsibility by sector.
The SCVR has worked well on the basis that Paul wrote a lot when he had a lot to say, wrote little when he had little to say & ignored the companies he was not interested in.
Generally, if there is more freedom to comment when you both have something to say, it will be more interesting for us & we will continue to see high quality analysis from both of you, as we do currently.
I would even be happy to read 2 separate commentaries on the same company.
Jeff
Hello Graham,
I agree with Jeff. There is no need for responsibility by sector. The analysis is working very well at the moment with Paul and Graham guided by their own knowledge and enthusiasm. Of course if in future more commentators come on board coverage can be extended to financial and resource stocks if the demand is there. One of the pleasures of this site is its high quality and the freedom of the commentators to roam a bit without making any claims to be comprehensive.
Fair enough JDW72. Obviously they are a successful organisation with a strong sales approach. I avoided them when looking in the market for their 'overvaluation' tendencies.
Whilst we are making suggestions ;-) is it possible to have one report with individual's bits added? You only get one email regarding the reports and I will sometimes miss the other if not looking on Twitter for example. It saves all your preamble pointers also and keeps discussions in 1 place also. Just a thought. Ta
I'd love to see someone with good knowledge of the sector covering resource small-caps in this format / style. It seems like that's a big segment of the market with little meaningful discussion coverage on this site.
Malcolm Graham Wood used to be a Stockopedia Author and post on the oil sector. He now has his own blog.
The Government announced that they will outlaw the extra fees that Letting Agents charge tenants. Although the proposals don't have much meat on their bones yet, they'll almost certainly reduce profits from lettings. At present tenants don't have much choice but to pay the fees if they want to rent the house. If agents try and make up those missing fees by charging landlords more, then landlords are perfectly able to take their business elsewhere.
No position on Foxtons (LON:FOXT) , however I'd feel safer being short than long.
Thanks for another useful report Graham. I think it makes perfect sense for you and Paul to break your coverage down into sectors, it's natural that you each have your specialisms.
I see that one of your sectors will be financials. Just a thought about a future topic for a blog post. There are lots of 'mid-cap' listed banks and insurers on the London market. However I always find it really difficult to value financials because the way they report means many of the conventional P&L valuation metrics are unhelpful, and it's difficult to understand what the true net position on the balance sheet means for future earnings. I realise this might be a bit broad for an SCVR post, but any pointers you could give to other sources of info would be welcomed!
Hi Daniel, good point. It's a common difficulty for private investors (and some institutions too, perhaps!), who end up buying banks or other financials because of their "feel" for how the company is doing, rather than because the numbers add up.
Of course, it doesn't help that even the people who work in banks, in divisions such as risk, are sometimes similarly unable to tell whether the numbers add up and what is really "under the hood"!
Graham
Hi Graham,
Would you, Paul and Stockopedia consider expanding the breadth of your and Paul's reports to also include larger caps? i.e., perhaps Paul continues with small caps while you look at larger caps. Apologies if this idea has already been discussed and I missed it.
Regards,
Clive
Hi Clive, nice suggestion which I will raise as an idea. I think a sector division probably makes a bit more sense from the point of view of enabling deeper research via industry comparisons, but I personally would be in favour of straying into the mid-caps a bit more frequently.
Cheers
Foxtons (LON:FOXT) isn't the only one in its sector that has struggled over last 6 months. Countrywide and Winkworth also weak. What most of these companies learnt from last time was to build up the lettings side, which helps to cushion the cyclicality. Although Foxtons (LON:FOXT) should worry about its reputation, if it pops onto one of my new high screens in 6-12 months I'd buy and probably do ok once the tide turns.
McBride (LON:MCB) way too much gearing supported by too thin margins, but I guess it is heading in the right direction.
Foxtons always had a 'reputation'. Overvaluing to get a property on their books was certainly one sales strategy that seemed to apply. This applied arguably to both the rental and selling side in my time in London (some time back now).
They had the strongest sales ethic, which sometimes means the service side of things was slightly spivvy. They introduced some useful online techniques such as panoramic views of properties, but in the end I generally avoided them when looking for something. Sellers were most often beguiled by the high valuations, but unless you had a premium property or were in a bull market, the gilt soon went off the valuation.
Two friends of mine have had the same experience with Foxtons when selling their flats (750 - 900k flats) in the last 18 months. They got three separate agent valuations including Foxtons and in both cases the Foxtons valuation was at least 15% higher than the other two.
So they both decided to give the "inflated" Foxtons price a go and gave them 8 weeks to market and get an exchange and in both cases Foxtons comfortably managed it at the asking price within a few hundred quid. So, in my sample of two, they did rather well.
I have no position, no relationship and no insight into the underlying business model or investment case. Just thought I'd chuck in that information.
JDW72
I have heard the same sort of stories anecdotally. Amazing that some people are blinded to this extent by their investment in fancy coffee machines for their offices and nice cars for their salespeople!
It's a decent business model when prices are rising fast, and people can "afford" to overpay slightly in the knowledge that the fair value of their flat will catch up in only a few months. I think the real question is how well this sort of business model holds up when prices stagnate (as they already are in super-prime central London) or, heaven forbid, start to decline slightly. It seems a risky end of the market to be in if the property market takes a turn for the worse.
What's your take on TCM,Graham ?
I think people are being too harsh on Foxtons (LON:FOXT) London property is probably due a correction, and for 1-2 years, this would undoubtedly have an impact on Foxtons. However, when you look at the business in a non-emotional way, it's actually outstanding. It's not capital intensive, it scales down ok, generates huge free cash flow and carries no debt. I think if you were to buy now at depressed earnings and held for a reasonable length of time, you could do very well here.
Hi Tabhair,
Yes I agree with you. Foxtons (LON:FOXT) has a lot going for it when you look at the numbers in the cold light of day and I think it's quite likely to trade a lot higher at some point over the next five years. No debt is the really critical thing when there's such volatile earnings.
I'm not brave enough to have a position though!
Rgds
Phil
Letting fees are being banned
#1. http://www.bbc.co.uk/news/business-38065249
#2. https://www.foxtons.co.uk/help/fees/
Foxtons ought to pray for an affordable housing market, as there is no way it is going to survive at its' current size without a big increase in sales volumes.
Yes McBride (LON:MCB) debt does look quite high, do they have a pension problem as well?
Nice report Graham. I actually worked at Foxtons for a year straight out of University. I was a Sales Negotiator in their Wimbledon office but luckily it was back in 2007 when the property market was beginning to show signs of weakness, so I made the wise decision to move on.
Anyway I keep a keen interest in the firm and although it's definitely not one I would go long on at the moment, it is worth noting the 'Flexible Costs' you refer to really are very flexible indeed. Their agents start on a £22k basic but at that level they earn no commission. To earn commission they have to drop to £17.5k at which point they earn 5% commission. A further drop to a £10k basic results in 10% commission and it only goes up from there if you do spectacularly well. Anyone who stays longer than 6-12 months will inevitably drop down to what they call "10 & 10" and so when the market is tough their staff costs are exceptionally low as most of their staff only take home more than £833 a month if they make a sale an thus bring in revenue.
As a reference point I now work in recruitment which is comparable industry. The norm in recruitment is for front office staff to be paid anywhere from £20k (entry level) to £60k (top 10% performer) basic salaries as well as commission of between 10% and 50%, usually 20-40%. Fundamentally there isn't a great deal of difference between the two industries (They are both essentially sales), so the fact Foxtons control their costs so well should offer some downside protection although not enough to make them investible at today's prices. That said if they get down to a PE of 6/7 and you have a reasonable long term view on the London property market, they might be worth a closer look. Although I am a holder of Purplebricks (LON:PURP) I personally don't think they will find it that easy to dislodge Foxtons entirely, especially in prime central London.
Thanks a lot for the insight, Ben!
Not surprised Foxtons is doing badly. I belong to a London local facebook group (15000 members) in which members buy and sell and ask for advice and help on local services. There was a thread in the last 6 months on estate agents asking for who to use. Several agents were recommended and it developed into a long informative thread with a lot of contributions but the main feature of the thread I noticed was the number of people who said dont use Foxtons and I will never ever use them again. No other agents featured with such bad feedback.
Foxtons (LON:FOXT), figures indeed do not look good. I wonder if it's all to do with the property market, is someone else eating their pie? I don't hold either way, if I did it would be short rather than long. Surprised the shares have not fallen more.
You need to change the year to 2017!
Thanks JMAR!