Small Cap Value Report (11 Jan 2017 - Part 1) - SHOE, JOUL

Good morning,
There are two reports today, this one from me, and an additional report from Graham - here - he's running a bit late today, due to a late flight last night. So his report won't be finished until later this afternoon.
Today I shall be reporting on;
- Joules - Xmas trading update
- ShoeZone - preliminary results
Graham will be reporting on;
- McBride
- Sigma Capital
- Foxtons
Yesterday's report - I had a late surge, and added loads more companies to it, in the evening. So I reported on a total of 11 companies. Here is the link to review that report.
Thanks for all the reader comments - these are an increasingly valuable part of the whole thing. I very much welcome intelligent, interesting reader comments. Feel free to disagree with me too - well-argued bear points are particularly welcome.
"Market expectations" clarity in RNSs
Before I get started on the companies, a quick hat tip (see Tweets below) to Reg Hoare of MHP Communications. Reg is one of my favourite PR people, as he's very responsive to private investors, and recognises our importance in creating liquidity & setting share prices.
Why do I talk to PR people at all, you may ask? Well, despite being much maligned, they're actually very helpful, I find. They give me access to companies that I wish to speak to & meet. They often email me broker notes on results day, and presentation slides which the Instis are given. Also they are sometimes receptive to grumbles I have about the wording of RNSs, etc. So my aim is to improve things for everyone, where possible, by giving useful feedback to the PR companies. Lots of them read my reports too!
For these reasons I'm happy to have a co-operative relationship with quite a few PR firms. I resist their charms when they try to change my views on companies, unless they present reliable facts & figures to support their argument. In those cases, I try to keep an open-mind & am willing to change my mind if the facts suggest that is the correct thing to do.
Also they all now know that it's a waste of time to try to get me interested in blue sky, or jam tomorrow shares!
Going back to Reg, he responded positively to my suggestion yesterday that all companies should clearly state in their trading updates the specific figure for market expectations.
Majestic Wine (LON:WINE) did that in their RNS yesterday, and it's so helpful, top marks to them & their advisers.
I'm pushing to ask all companies to follow suit. Anyway, this was my Tweet, and Reg's response;
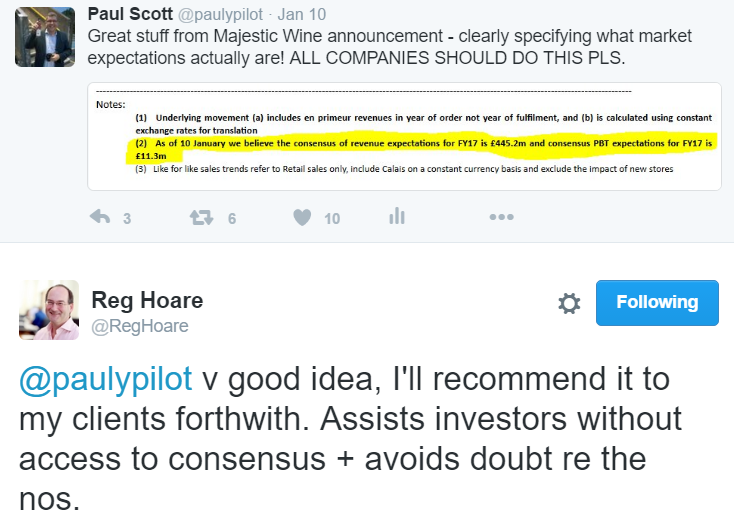
Isn't that great?! Well done Reg. On this issue, I will be bending the ears of other PR people, and brokers, and in fact anyone who will listen! It's such a quick & easy fix, to make life easier for investors. There is no downside, or risk. If we have clarity, we're more likely to buy a share too, so it makes sense to improve trading updates for the end users.
Shoe Zone (LON:SHOE)
Share price: 182.5p (unchanged today)
No. shares: 50.0m
Market cap: £91.3m
(at the time of writing, I hold a long position in this share)
Results 52 wks ended 1 Oct 2016 - the figures for this discount shoe retailer were pre-announced in a trading update, which I reported on here, on 25 Oct 2016. So I'll now compare that trading update with the actual figures today.
(NB. the table below is my personal notes, created by me, it's not from the RNS)
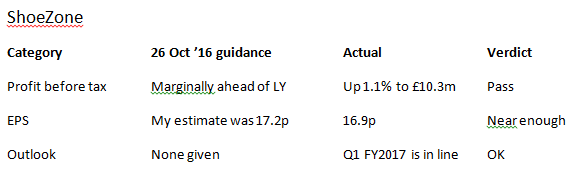
Please bear in mind that my estimate of 17.2p EPS above was not from the company, it's just what I deduced from the trading update in Oct 2016, and broker notes.
So this looks OK. A bit more detail;
- Gross margin - excellent, at 62.0% (LY 61.5%) - can this be maintained though, as forex cost pressures mount? In narrative, company reassures that GM can "broadly" be maintained.
- Online sales up 11% (should be more). I can't find a figure for total, or what proportion of grand total, so assume it's not particularly high.
- Growth in international sales online - encouraging, but need figures on this to assess important.
- Short leases - this is a key competitive advantage, which I like very much. Average length is only 2.6 years. This means company has flexibility to relocate, and take advantage of "trend of falling rents".
- Business rates - company says it will be a net beneficiary from the recent revaluation - good news.
- Balance sheet - very solid, with plenty of cash. Although note pension deficit has risen significantly and £0.6m annual cost is going to rise.
- Family-controlled, so a takeover bid is very unlikely, unless they want to sell out. If they do, then it would have to be at a decent premium.
- Dividends - very generous - 6.8p final, plus 8.0p special divis are in the pipeline.
- Cash generation - very good, and anything above £11m is paid out to shareholders, a terrific discipline (similar to Somero Enterprises Inc (LON:SOM) yesterday)
- Current trading - in line with expectations. They're up against soft comps though, as last year's H1 was poor.
My opinion - I like it a lot. However, it's a mature business, so where's the growth going to come from? In current market conditions, I doubt there is much upside on this share price - the market isn't interested in mature retailing businesses right now - it wants fast growing ones.
That said, the income from divis here is smashing.
I've dipped my toe in, with a small purchase this morning. My intention is to research it in more depth, and think about it more, before deciding whether to buy any more. I doubt this will become a significant holding for me, it's more a dabble, and to generate a bit of dividend income.
Based on the bullet points above, I think Shoe Zone should be able to cope with more depressed retail conditions in 2017 far better than many others. That's mainly due to its variable (and reducing) costs on shop leases, and an apparent ability to maintain margins. I like that it's a really entrepreneurial business, run by a family who clearly know what they're doing, and are experienced.
That said, I don't see much excitement being likely with this share, and it could even drift down, in current market conditions. I would buy more if it dropped significantly.
EDIT: I forgot to mention, FinnCap has put out a rather downbeat note today, saying it's going to reduce its forecasts. Another broker has put out forecasts which show negligible profit growth over the next 2 years.
Therefore I think we should work on the basis that profit is likely to be flat, or maybe down a little in the short to medium term. I think they're perhaps being a little too negative. Sure, SHOE is subject to the same wage cost pressures as everyone else. However, it has mitigated cost increases from the forex issue, so it says, and is also able to manage down its rent+rates costs, unlike most other retailers.
So to my mind, this company is more likely to weather any storm in weaker consumer confidence, than most other retailers.
Joules (LON:JOUL)
Share price: 226p (up 3.2% today)
No. shares: 87.5m
Market cap: £197.8m
Christmas trading update - what a useless update this is! It doesn't give us the two key bits of information that we need - namely LFL sales growth, and profit versus market expectations.
So we now have to guess whether they are deliberately withholding inconvenient figures, whether the office junior was left in charge of writing & publishing the RNS, or even that they may not actually have accurate data to report?
Instead the company says this;
Joules delivered a strong performance over the Christmas period with total retail sales* up 22.8% against the comparable period last year.
Retail gross margin rate, over the same period, is expected to be marginally ahead of the prior year. This outcome reflects continued strong growth across both the Store and E-commerce channels.
Also, they don't tell us the split between how retail & ecommerce sales performed.
So all we have to go on, is that management tell us everything went well over Xmas.
My opinion - this looks quite a nice growth stock. Although the net margin isn't quite as high as I would expect. Also, it has a very established "preppy" design for its products. Being so niche increases the risk that this look could go out of fashion.
The shares look a bit pricey to me, but so is everything that is growing organically, and with an online element.
If you like growth stocks though, this one is worth a look, in my view.
Right, got to dash - I'm off to IG's office, to record my quarterly "Small cap wrap" with Jeremy Naylor. All good fun, and it makes me really focus on which are my best stocks - a useful exercise.
Best wishes, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

38 comments
See? Knew 8 pairs a day wouldn't do it - But 8 pairs an hour . . . . :)
I walk past a Churches shoe shop (top end) every morning and at various times of the day. Yet to see anyone in there!. Think the prices are so high that buyers wait for the sales.
If Shoe Zone (LON:SHOE) generates annual revenue of £160million from 500 shops then the average revenue per shop is £320,000.
Assuming each shop was open 9 hours/day and 6 days/week then each shop would be selling just EIGHT pairs of shoes per hour (assuming average retail price £15).
A shop selling eight pairs of shoes per hour will rarely look busy!
I think the problem is they have many smaller stores in small towns or even in cities they are not always in the main shopping areas. So yes a lot of these stores will look quiet, you say 8 pairs an hour but in the smaller ones that is probably 2-3. They said last year they were closing some smaller stores and opening larger ones, so that should help with growth. For me they have too many stores, many probably are not that profitable, with wages rising that will also affect costs, if you have 2 staff and only selling 4 pairs an hour you can see that's not going to be profitable. Looking at their stores in East Anglia, they have 1 in each major town but then there will have 1 in most towns within 15 miles of them, why not just concentrate on bigger stores in the main shopping centres, people will travel into their nearest large town for shopping, shoes are not something you buy every week, people do make the trip to buy clothes and shoes.
Howard, seeing as you've gone to so much effort to break the sales down into daily sales per individual shop (although traditionally weekend retail shop days are stronger than general week days) let's agree that your ballpark figures are close to accurate as is possible.
I have one question based on the assumption that Shoe Zone (LON:SHOE) shops only sell 8 pairs of footwear per day on average.
And it's this:
- How can 8 pairs of footwear sold per day, cover that day's staffing costs (baring in mind the minimum wage and that the shop manager will be paid above minimum wage) let alone after that, contribute towards regional and head office managerial staffing costs - and then some left over to cover the remaining running costs, not to mention expensdive shop leases etc., AND after all that still leave enough over to call it a decent profit? All from just 8 pairs of footwear sold per day?
- I've seen market stall traders admit to selling more than that per day. And they're still struggling to get by.
I'll let a shareholder of Shoe Zone (LON:SHOE) answer that question Velo.. they are likely more qualified than me in this company.
I suspect the answer lies in the 62% gross margin i.e. each pair of shoes sold at £15 generates nearly £10 of gross profit.
Velo, I think you've had a senior moment. The estimated store turnover for Shoe Zone (LON:SHOE) above arrived at 8 pairs per store per HOUR and not per DAY, so that's an average of 72 pairs per store per DAY.
As regards the costs of running each store, bear in mind that landlords now pay rates on empty shops so it is better to have a tenant paying no rent at all than have the shop empty. I expect the management of Shoe Zone (LON:SHOE) take advantage of this and take short term deals at no or low rents. On staffing you don't need to be well qualified to sell a pair of shoes in their sector. Those over 25 would get at least the National Living Wage, currently £7.20 per hour. But those aged 21 to 24 could get paid less, those aged 18 to 20 even less, those aged under 18 even less and an apprentice even less again (£3.40 per hour). So that opens lots of opportunities for cost savings!
Also, I expect many of the shops, such as those in small towns probably only cover their operating costs and a 1/500th share of central costs and make no surplus. That's not a problem as (1) they help build brand recognition which helps the chain nationally (2) it spreads central costs over a larger number of stores so, for example, one international buyer can just as well buy for 500 stores as he can for 250 stores so his/her pro rata cost per store is only half what it would be and (3) the larger volumes from a bigger estate generate bigger volume buying discounts which benefit every store.
It is probably only the sites in busy city locations that really make the profits but that's partly due to the lower overheads they bear individually from having a large estate of stores and from the buying economies that flow from this also.
"...Given the experiences of readers of this blog it seems the Directors of Shoe Zone (LON:SHOE) need a standing ovation for having generated £160m of sales from an estate of just over 500 shops that appear to be devoid of any customers!.."
- LOL! Hee hee! That's what I'm thinking.
&
"...The average share buyer obviously would not go anywhere near such a bottom-end store as this and is probably walking past at the wrong time of day! .."
- Yep! I certainly am walking past AFTER paying customers have left.. Have calculated that they must be packed out to the rafters with customers between 9:00am and 11:30am. It's the only explanation left!
Given the experiences of readers of this blog it seems the Directors of Shoe Zone (LON:SHOE) need a standing ovation for having generated £160m of sales from an estate of just over 500 shops that appear to be devoid of any customers!
I am reminded though of a quote from the most successful British shoe retailer ever, Sir Charles Clore, who established the British Shoe Corporation after the Second World War. He once said the easiest way to make money was selling shoes and the best place for a shoe shop was right next door to another one.
Sir Charles Clare was not only quoted as saying this but carried it through by standing outside his Lilley and Skinner shops and counting the customers into it as well as the customers going into the rival Saxone stores which were often next door.
He later bought Saxone and seemed to get satisfaction from firing all their headquarters staff in Kilmarnock.
Apologies, I should have said Dolcis stores not Lilley and Skinner ( which was part of Saxone).
Lots of adverse comment, but they are a highly profitable and extremely well outfit. The average share buyer obviously would not go anywhere near such a bottom-end store as this and is probably walking past at the wrong time of day!
Shoezone have a VERY low quality product offering. As far as I can see, there are plenty of other supermarkets and discount retailers with marginally more attractive product at a similar price. No moat at all.
My nearest store has a prime location in central Milton Keynes. The rent cannot be cheap. Although I suppose a small empty town centre shop might cost less to run than a large empty Brantano shed on a retail park.
I too pass a Shoe Zone (LON:SHOE) shop on my travels and must be passing at the wrong time, as I too, never seem to see any customers in there either. Tried them as a customer too, in the past. Left disappointed. Didn't care about style - just wanted a comfortable fit - of anything that goes on feet. Couldn't achieve it.
Am I the only one with feet a Hobbit would be proud of? Surely not.
Buy footwear online?!?
- If you wagered a million pounds that ordering the correct size of footwear for my personal use by any form of mail order would result in a comfortable fit - I would long have become a multi billionaire. It's an impossibility with my Ronnie Barker like jibe of: "what with these feet?"
Is there any one item of human attire more calculated to cause anxiety and irritability due to ill fitting by buying blind, online? No wonder they decline to elaborate on how much an 11% increase in online sales is in £'s & pence.
EDIT: Just noticed someone posted of buying ALL their footwear online. (They must have detachable, interchangeable feet, is all I can conclude).
PS. When I tried their footwear I was the only one in there. On another occasion some months later, I wasn't - there were two other customers as well.
I also have a Shoezone in my nearest town, never seems to have anyone in it. I did actually buy some shoes from them, not impressed with the quality after a few weeks they are already falling apart, at least Karimores lasted about 2 years.
Buying online I have tried that, most I had to send back, today sizes don't seem standard at all and I find most shoes these days to be quite narrow. I used to take 7.5-8 but now it's always 8 or 9 or sometimes even 9.5 or 10.
Yes, but be fair Herbie, Are you surprised they didn't last? You probably bought the ultra cheapest footwear in Britain. It's their USP. Cheaper than Aldi et al.
It's why I visited them with serious intent.
I wanted cheap, cheap, footwear - but my feet aren't having any of that.
Rule No:1 for shopping at Shoe Zone (LON:SHOE) - is that you have to have the right feet. I've got the wrong feet.
To be fair they were similar prices, so comparing like with like. They fit ok it just the wear is not. They were not that cheap either. I only have one right foot.
US Biotech taking a battering due to Trump's press conference!
Re SHOE
Thanks Paul, I have bought in to SHOE, both on the strength of what you say, their report and also the special dividend of 8p a share which will be added to the final dividend of 6.8p (subject to agreement at the AGM) - giving 14.8p per share which at the current share price of 180p is 8% - bit of a cushion there for things going wrong I would have thought - though obviously the share price will dip on dividend payment.
I was drawn specially to this as Paul likened it to Somero, which I want to but can't buy through my SIPP.
clarification of dividend timetable here..
Wouldn't buy shoes online myself...
http://www.shoezone.com/Investors/Investors/Financial-Information/Results-and-Presentations
On the subject of SHOE surely shoes are less likely to be bought on-line than other clothing items - as such I think there is an element of having a natural moat - get the site right and the price lower than your competitors and its job done - cost inflation or no cost inflation.
Ditto Food
Ditto wallpaper/paint say.
Shoe Zone do sell online at shoezone.com as well as in the stores.
The last shoes and the last wallpaper bought in this house were bought online. I agree on paint as it's helpful to look at the whole range in store but we have bought online before when the store didn't stock the colour we wanted.
Some people will buy shoes online, others not - if they can sell profitably to both groups they will be fine.
The point is - where is the vast, vast majority bought?
Of course you aim to sell through all available channels but ultimately these items are bought in person not by mice
I am surprised at the assumption that food will not be bought online - when it already is, and in substantial and fast growing amounts. I use Ocado for probably 80% of all food purchases and with Amazon joining the offerings by all the main supermarkets it will only increase.
I am happy to buy basic shoes online - as long as the return process is slick. SHOE concentrates on basic rather than fashion offerings so I would expect its sales to go online even faster than, say, Russell and Bromley
I am talking about the percentage share of the whole market of course - not that NO food is bought online.
Ditto the other markets quoted.
Ultimately the majority shop for these items in physical shops - and will imo continue to do so - hence the growth in the local Tesco's/Sainsbury's/Marks etc
Before we get too excited about MHP Communications let's not forget they were responsible for Fairpoint Plc's investor communications. Yes it's ultimately the client that signs statements off and perhaps they went against MHP's better advice, but ultimately an agency is tarnished by its clients' reputations and shares responsibility for what they put out.
My main concern re. Shoe Zone (LON:SHOE) is whenever i go past their stores, I am amazed at how empty the stores are and also how bad the quality of their stock is. Albeit from the quality of the decor, it must be very cheap to fit out!
Their competitive advantage is having short leases - hardly a moat given the growth of online competition with no high-street leases!
Also I note the continual downgrade of broker forecasts over the last year - I foresee this to continue, as online competition continues to take market share.
Interesting to see Gervais Williams has recently been selling down the holding in the Multi-cap Income Fund.
Only consolation is that the Stockopedia algorithm clearly rates the stock (albeit, it has for the past year), and the company has under-promised and over-delivered for 3 years now (a common trait with family-owned companies), and the lack of debt.
My main concern re. Shoe Zone (LON:SHOE) is whenever i go past their stores, I am amazed at how empty the stores are and also how bad the quality of their stock is.
It is a sad fact that in the UK in 2017 there are many poor people who can't afford to buy shoes from Russell & Bromley, and everyone needs shoes. To judge a company as an investment based on the activity of one or two shops (out of over 500) on a walk past doesn't strike me as evidence of anything, but I'm sure you realise that. Like Paul, I quite like Shoe Zone (LON:SHOE) as an investment and have bought a few, but mostly because I believe the management are extremely innovative and very good at what they do - to sell something so cheap at such extraordinary gross margins and generate impressive cashflow shows great understanding of their business and that they must be extremely well connected with their suppliers, not unlike Boohoo.Com (LON:BOO) in a way.
As Paul surmised recently, I also believe it is the retailers in the middle that are struggling e.g. Next and that the top-end and bottom-end will do OK, even in a recession.
Interesting to see Gervais Williams has recently been selling down the holding in the Multi-cap Income Fund.
Has he? Last time there was an RNS Miton held 14.25% of the company. If he sold more than 125,000 shares ( approx. £225K's worth) there would have to be an RNS saying they had gone below 14%. I can see no sign of this RNS. Perhaps he's just flipped them into another Miton fund?
All in all, I quite like it as a contrarian play and the dividends it is throwing off in a low interest rate environment are worth having for income.
All the best, Si
I recognise that not all are fortunate enough to purchase Russell & Bromley shoes. However, that does beg the question as to why the Shoe Zone (LON:SHOE) stores remain so empty?
Actually the shops I've gone past recently are in London, Chesterfield, Sheffield, and Bangor - a fairly good diverse spread, whilst appreciating it remains a small sample of their estate.
According to Bloomberg, Miton's holding is 19.37% split across various funds and the Diverse Income Trust. In December, the Miton Multi-cap Income Fund sold down 250,000 shares, leaving the asset management arm with a 14.13% holding. The Diverse Income Trust, when it last declared its holding in July, had also been selling.
I purchase most of my shoes online now, whilst my younger family members and friends do so even more so. I believe this trend will continue (the broker earning downgrades seem tovsuggest so), and would be concerned by the relatively low growth from online sales, given the low base it is coming from at Shoe Zone (LON:SHOE).
Anyhow, you're a fan, whilst I believe there are better opportunities out there. That's what makes a market. Just highlighting my concerns, as Paul asked readers to do so.
According to Bloomberg, Miton's holding is 19.37% split across various funds and the Diverse Income Trust. In December, the Miton Multi-cap Income Fund sold down 250,000 shares, leaving the asset management arm with a 14.13% holding. The Diverse Income Trust, when it last declared its holding in July, had also been selling.
I'm never sure how reliable and how frequently updated news sources like this are and so was only referring to the latest holding RNS from April 1st - probably quite an apt date for anyone long of Shoe Zone (LON:SHOE) it would seem :-): http://www.investegate.co.uk/shoe-zone-plc/rns/hol...
There has been nothing since and so do not see how this qualifies as Miton selling down their holding recently though clearly they have at some point to get from 19 to 14% as of last April. Anyway, it's nice to know I am in good company! However, it does beggar the question why a respected small cap investor has such a large holding in a very illiquid company that sells crappy shoes from empty shops?
I must say I am greatly encouraged by the negativity towards the company here, it confirms the contrarian nature of my very small holding which is part of a small pot I have for out of favour high QV rank shares paying good dividends which also currently includes Braemar Shipping Services (LON:BMS) and Gattaca (LON:GATC).
All the best, Si
Speaking from experience, more pertinent imo than that is that 'market expectations' is often used to AVOID stating a number which the MHP chap must surely know.
After all they help draft these statements - he must have come across this issue many many times !!!!
To put the JOUL 22.8% increase in sales in some context - this was from 11.4% more stores (107 trading in 2016 compared to 96 last year)/
Obviously in principle I applaud the Paul Scott / Reg Hoare initiative for companies to spell out exactly what "Market Expectations" are. At the risk of talking my own book, one potential problem is that quite a number of smaller companies have no broker research coverage at all, (or if they do it is several months "out of date"), so there are no "Market Expectations" out there to be measured against.
They could report against "management expectations" in those situations.
They would probably use 'management expectations' for that, but thats like trying to hold down a slippery fish
Paul,
From Final results last year: Online revenues (excluding store orders) have grown by 44.7% (2014: 20.6%) during the year and online sales represented 3.3% of total sales (2014: 2.3%).
Product gross margin strengthened to 61.5% (2014: 61.3%) reflecting further increases in direct sourcing and a reduction in stock mark down.
Share always seems muted but paid c10% in divis last year with more of the same this year - I hold and like this "boring" share
Hi Paul
In haste as flying back to Meribel in an hour but re
"....broker notes on results day, and presentation slides which the Instis are given...."
Surely these should be available on the investor section of a company's web site at the same time they are sent to institutions. It seams wrong that there is one rule for PI's and one for institutions.
That said as most managers underperform the index maybe we don't this surfeit of infornation?!!!
Thanks as ever.
"Surely these should be available on the investor section of a company's web site at the same time they are sent to institutions. It seams wrong that there is one rule for PI's and one for institutions"
Rest assured Purpleski, all information handed out at institutional investor results meetings has (to avoid inside information infringement) already been made public either via the company website or broader internet disclosure.
The one advantage that the institutions do have is in corporate access i.e. meeting companies 'one-on-one' in the periods in between results presentations.
Companies at these meetings clearly cannot (by law) disclose inside information. However, given that 'body language' supposedly represents 90% of communication, access to such meetings is clearly an advantage.
Great Work Paul on helping the Individual Investors!
(and good call on Foxtons btw)