Small Cap Value Report (11 May 2015) - CVR, AHCG, NGR

Good morning!
Now that all the excitement of the Election is out of the way, the stock market has breathed a sigh of relief, and rallied a bit. Although history suggests that the Tories will find it very difficult to manage with a wafer thin majority, and possibly no majority at all after a few by-elections.
Although we've certainly avoided a variety of scenarios which could have badly unsettled the markets, which is reassuring.
Conviviality Retail (LON:CVR)
Share price: 145p
No. shares: 66.9m
Market Cap: £97.0m
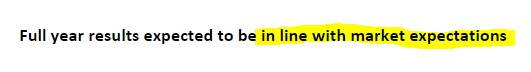
Trading update - I like the sub-heading (copied below), which makes it crystal clear what the key message is, and would like all companies to do this, to make it easier for us to quickly assimilate the core message of trading updates, without having to ponder & interpret lots of text;
More detail is given;
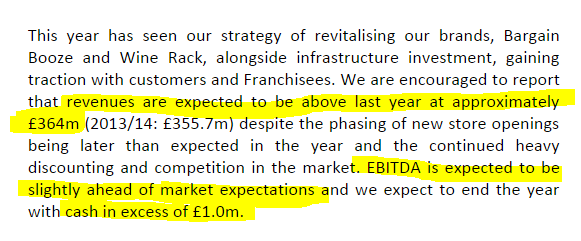
That all sounds fairly encouraging.
Valuation - the usual Stockopedia graphics look reasonably positive here, especially the generous dividend yield;
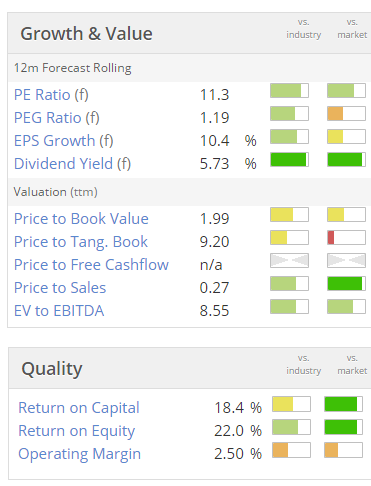
My opinion - I'm generally positive on this share - it ticks some value investing boxes - a reasonable PER, and good dividend yield, although the balance sheet is not particularly strong (but not a particular concern either).
I like the franchised business model - so franchisees bear the inventory risk (of theft by staff & customers), and it therefore requires little capex. Therefore the ROE and ROCE scores in the quality section shown above are quite high. Although the operating margin is tiny, at 2.5%, which puts me off.
Competition from the supermarkets is obviously intense, and likely to become even more so. Although the Bargain Booze and Wine Rack fascias run by this company are probably more used for impulse purchases by locals, I imagine.
Growth of about 12% in turnover & profit are forecast this year, due to additional stores acquired recently. Although note that there is no organic growth, with LFL sales down 1.7% for the main Bargain Booze stores. Lack of organic growth is a concern, and suggests they are only just holding their own against stiff competition.
Overall I think it's probably safest for me to avoid these shares, although the divis are appealing. There is also the worry of potential bad debt risk, if a major franchisee were to go bust at some point. Therefore on balance I think it's probably priced about right at 145p per share, based on information we currently have.
As with all recent floats, I think it's worth pondering why the previous owner wanted to sell? So many recent floats have warned on profits, that I think it's best to be extremely sceptical of all recent floats, as there's usually something wrong with them which motivated the previous owner to sell.
Note that the StockRank is very good, at 92.
Action Hotels (LON:AHCG)
Share price: 60.7p (up 3% today)
No. shares: 147.6m
Market Cap: £89.6m
Audited results - for calendar 2014 are out today. This is a growing hotels group, focussed on the budget and mid range sectors, in the Middle East. The company floated on AIM in Dec 2013.
The P&L shows a useful performance improvement on last year. However, note how the debt interest charge (highlighted below) consumes the bulk of operating profit;
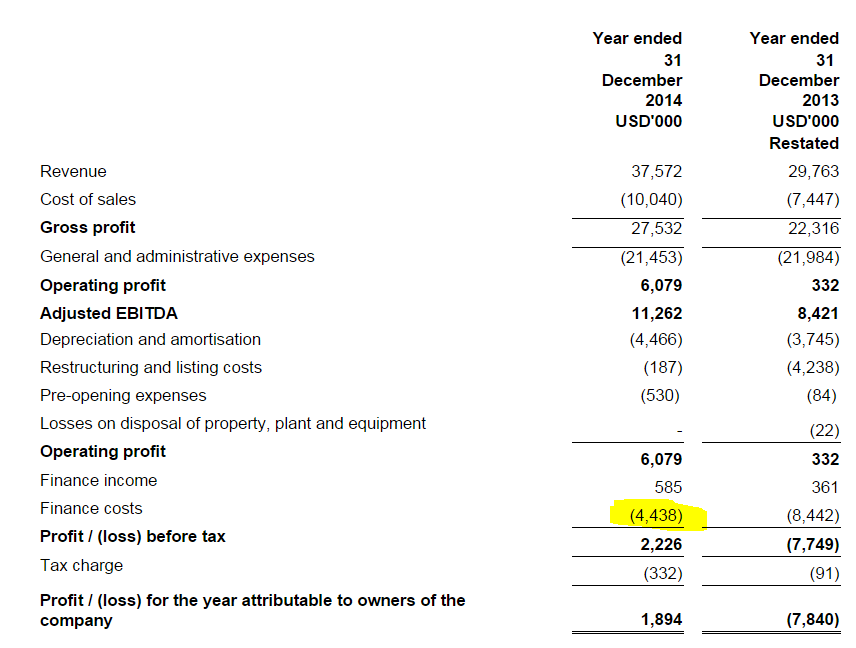
Therefore, as things stand at the moment, it doesn't seem to be generating anywhere near a satisfactory return on the substantial asset base of $286.2m (investment properties + property plant & equipment).
With net debt of $103.2m, the pedestrian return on the assets could potentially become a problem - so I'd want to find out what the bank covenants are, and the other terms of the bank borrowings.
Expansion seems rapid, with 8 hotels operating, and a pipeline of another 8 coming. So the fixed assets probably contain some amounts relating to properties under construction, and therefore not generating a return yet. So that might partially explain why performance so far has not been very good compared with the large gross assets.
Net asset value - the company includes a table in the results, showing how it has adjusted NAV of $1.32. However, in narrative below they refer to NAV being GBP 1.32 pence per share, so there seems some confusion over the currency. As the Balance Sheet numbers are in dollars, then by my calculation the NAV is indeed $1.32, which is 85 pence in sterling.
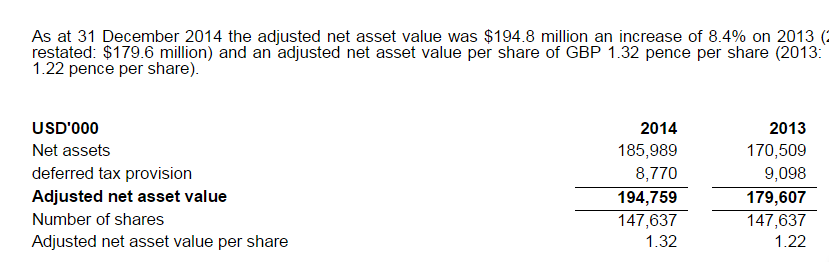
Note that the hotel freehold assets are revalued annually, so any upside versus historic cost is already baked into the balance sheet numbers.
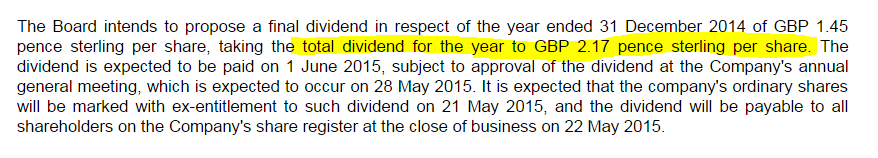
Dividends - the company seems to be declaring a divi that is far more than broker forecast. This seems an odd decision, considering the company is growing rapidly, is cash hungry, and has considerable bank debt.
My opinion - it looks potentially interesting, but you can't value the company at all accurately based on these historic numbers. The crux is what profits & cashflow the company will generate once it has built all the current hotels in the pipeline.
So more research is needed here, but it's one to possibly go on the watch list perhaps?
The track record of management is also vital, for growth companies like this. Have they managed big roll-outs before, and do they have the necessary skills? The CEO seems to be a former Hilton Hotels man. The Chairman is a Sheikh, whose name seems to possibly link him with the Saudi royal family? That's what a Google search is telling me anyway.
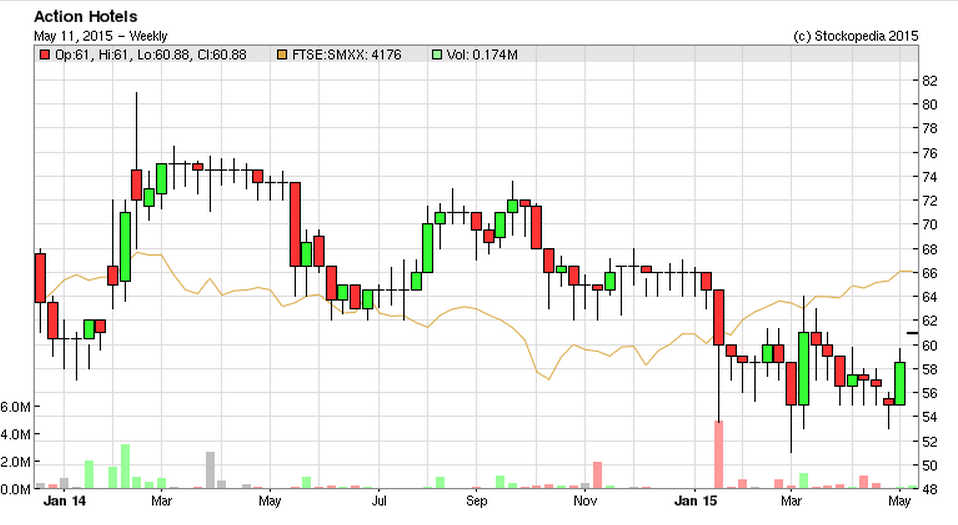
So far the shares have not impressed the market;
Have any readers looked at this company? If so please feel welcome to air your thoughts in the comments section below.
NATURE (LON:NGR)
Share price: 13.7p (down 5% today)
No. shares: 79.3m
Market Cap: £10.9m
Final results - for calendar 2014 are out today - far too late in my opinion - the figures should have been published in March, not May. That indicates to me a lack of financial control, something that is confirmed by a series of profit warnings from the company in the last year or two.
The P&L shows a loss before tax of £3.0m, although the highlights section of the narrative doesn't report this, instead highlighting the "adjusted" loss before tax of £1.3m. The difference seems to relate to fixed asset write-offs & other costs relating to the explosion at their Gibraltar facility a while back.
Balance sheet - cash is starting to look a bit tight, having reduced from £3.6m to £1.1m in the year, and the company also had £2.3m in bank debt, so I make that a net debt position of about £1.2m at end 2014.
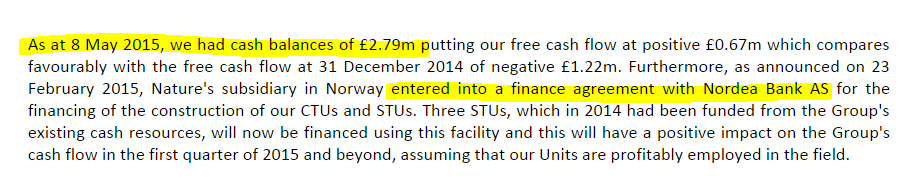
The company reassures that action has been taken to improve cashflow since the year end, and they look to be in a better position now;
Outlook - the Directorspeak is generally positive, with the outgoing CEO commenting as follows;
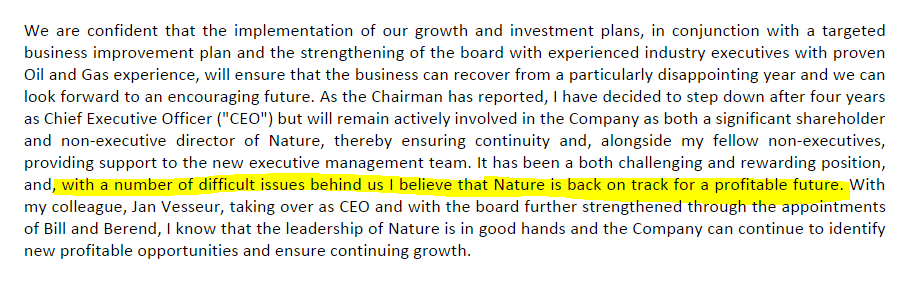
My opinion - so many things have gone wrong in the past, and the company's activities seem difficult to forecast, therefore I don't think these shares can sensibly be seen as anything other than a complete punt.
That said, the company made profits of c.£1.5m p.a. between 2009 and 2011 inclusive. Note that management proved very shrewd sellers of a substantial number of shares in the spike up to the 50-85p range in 2011. Although they have been buyers (on a small scale) more recently.
With a poor recent track record, and nothing more than reassuring words from management for upside, I can't get anything like the level of comfort needed to consider buying shares here. It will be interesting to see if the new CEO (former COO, so not completely new) can turn it around or not.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

10 comments
Paul,
I'm also in AHCG but a small sum only. Bought a few months back as I'm aware of the lack of mid priced hotels in the Region. Not just for holiday makers and locals but business travellers who are regular visitors to that neck of the woods whose companies have tight travel expense policies.
so far has been a bit flat but thought i'd give it a little longer. Today's announcement encourages me to stay in and see how they deliver.
Re ACTION HOTELS, have been in and and out, and am now back in. There is a strong middle class in the Middle east and they need somewhere to stay! I see this as the Premier Inns of the area. The new FD looks solid .
Re: AHCG
I doubt it matters but an Al-Sabah is far more likely to be a member of the Kuwait ruling family.
Hi Paul,
Thanks for your report, as useful as always.
I wondered if you had heard of Pittards (LON:PTD) ' share issue revealed on Friday. For a start, let's note that the open offer for shareholders will surely be well received by you and your readers!
But beside this positive point, I don't know what to think about the objective of the placing: of the 5.6m after expenses, two thirds seem to be to provide working capital, despite the narrative saying it is for investment purposes (the acquisition of freehold, minority interests...).
I guess it's what I get from investing in companies with a track record of three years of negative free cash flow!
The company also speaks of "a number of opportunities for expansion" so I am wondering whether there could be an aquisition in the pipeline?
Would be glad to read your thoughts on this, if you have 5 minute to spare.
Thanks again for the daily reports!
Thomas
Hi Aiminvesting,
I overlooked the news of the Placing/Open Offer from Pittards (LON:PTD), but spotted it today when catching up on a backlog of emails.
I think it's a good thing - the company has looked a little stretched for working capital for some time, and the Placing price seems sensible to me - a bit of a discount to reflect the lack of liquidity, and I'm very pleased they have tacked on a small Open Offer too, so at least small investors such as myself do not feel aggrieved at the dilution.
Buying back their HQ freehold also sounds a very sensible move, and will have long term benefits.
So overall, it looks a sensible deal in my view. The way I look at Pittards, is that it is an obscure little company which might, just might, hit a sweet spot for branded high end luxury goods, which is what happened with spectacular success at Mulberry (LON:MUL) a few years ago. Pittards has a Non Exec who was formerly the head honcho at Mulberry.
It might be a long shot, but Pittards looks an OK business, reasonably priced, now. But if it has potential 10-bagger upside at some point, which may or may not happen, thrown in for free, then I think that is potentially quite interesting. I'm intending to hold this one very long term, so 5-10 years, maybe more.
Regards, Paul.
NATURE (LON:NGR) has around 25% exposure to the oil & gas sector. Although they took a knock in this division in 2014, the company seems to be bullish about 2015 prospects. I can only think that they will have to compete more keenly for contracts as the oil & gas services sector will suffer generally. Margins will be eroded.
Re the Action Hotels dividend, it's just a net cost of £1m (discounting the 2/3 they pay to themselves as majority shareholder). I'm guessing the point of the game might be to establish a solid London listing, maybe regardless of short term economics, in which case that sort of amount as a marketing expense seems fine (some people spend that on their IPO advisers...). The owner is probably not cash poor and can feed in some more external cash to the business should that be needed.
Paul
Interims today from Jelf (LON:JLF) look encouraging at first glance. What's your view?
FREng
Hi FREng,
I don't report on companies in the financials/insurance sector normally.
I recall seeing Jelf (LON:JLF) management present at Mello a year or two ago, and the CEO struck me as down-to-earth & a safe pair of hands. I see the shares have done very well since then.
Looking at their results today, briefly, the headline figures look good. Although I'm not keen on the balance sheet (negative NTAV, as intangibles are substantial). Also lots of adjustments on the P&L, whereas I prefer clean figures with no adjustments. The divi yield is very low too.
Maybe the valuation might be getting a bit toppy now?
Regards, Paul.
Thanks. You have commented on Jelf (LON:JLF) a couple of times before and one of those comments led me to investigate them further and to buy at 90p. Keep up the excellent work!
FREng