Small Cap Value Report (11 Sept 2024) - TRST, GMR, RCDO, GYM. Movers: RTO, SMWH, PEB

Good morning from Paul & Graham!
A huge thank you to Roland who did a brilliant job holding the fort yesterday. Unfortunately I lost my flat keys over the weekend in London, came home late on Monday unable to get into my own home due to lack of available locksmiths. So I had to book into a local budget hotel, and got caught up in a coach party of pensioners, on a 1950-60s rock 'n roll themed seaside break, singing along to Eddie Cochran and the like in the hotel bar, performed by a one-man tribute act who could sing, play the guitar, and do an occasional flourish on the keyboard too. Not bad, but also not how I had planned my evening. Anyway, I eventually got into my flat late morning yesterday, having been relieved of nearly £300 by the locksmith, which was fair enough as he was here a while. At least the hotel did a good full english, the only highlight in an otherwise stressful & unproductive day for me.
Roland very much rescued things, with summary coverage of a large list of companies reporting, and some main sections too. Great work Roland!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
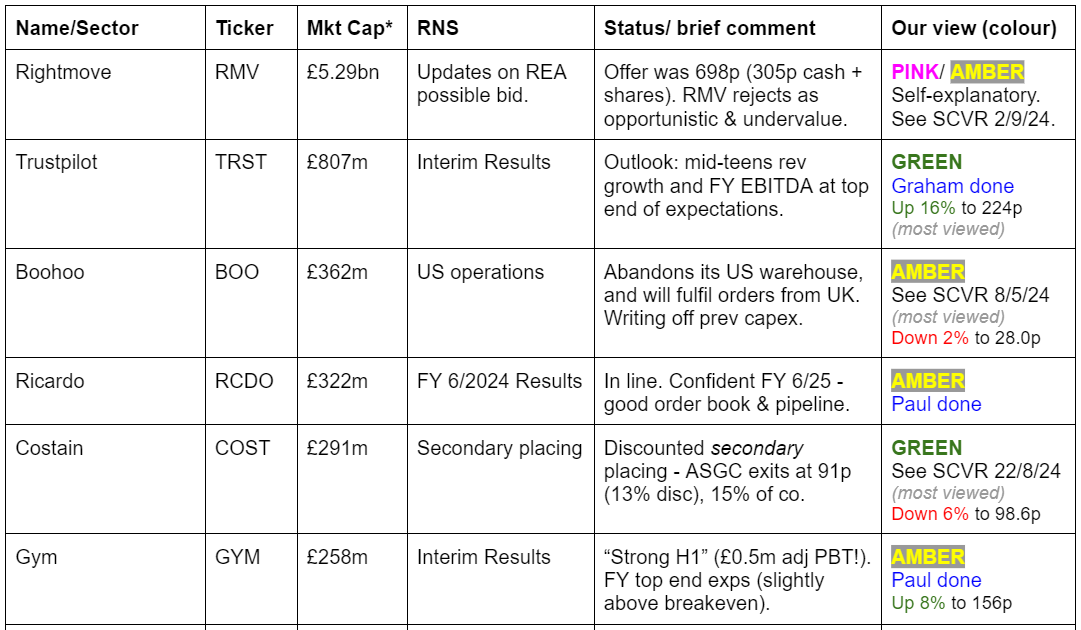
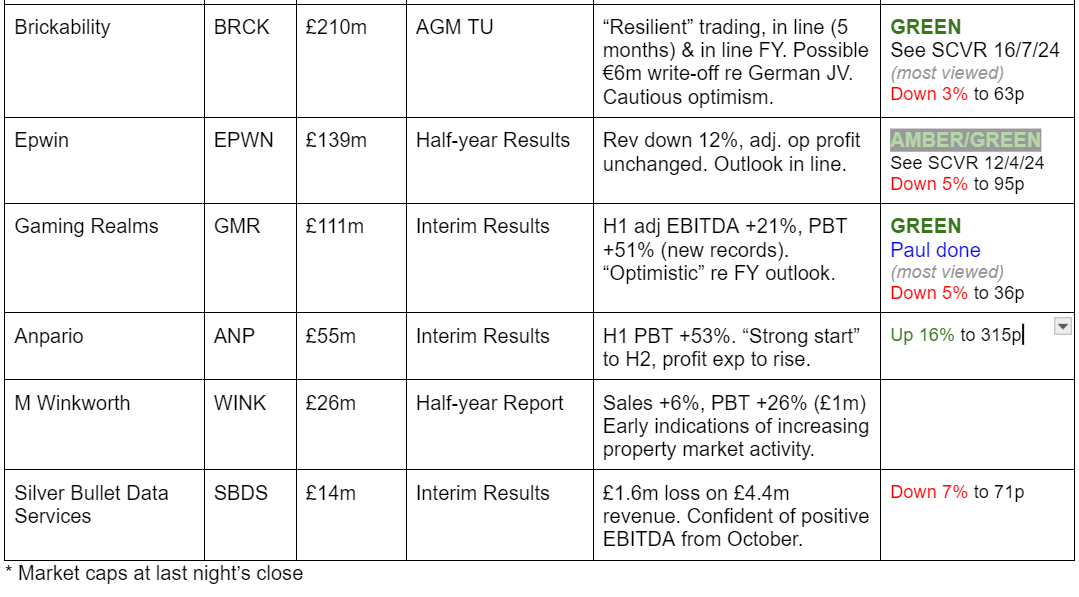
Other mid-morning movers (with news)
Rentokil Initial (LON:RTO) - down 17% to 394p (£9.95bn) - Trading Update [Profit warning] - Paul - BLACK
Softer revenues (£20m profit impact) & cost over-runs (£50m profit impact) in key USA market. Forex headwind c. £10m profit impact. Revised guidance FY 12/2024: £700m adj PBT. FY 12/2023 actual was £766m adj PBT.
Paul’s view - I checked it out here on 7/3/2024, and was surprised at how weak the balance sheet is, with c.£(3)bn negative NTAV. Add a profit warning today, and a high PER, and it’s difficult to see any attraction to this share. Just a quick look, hence no colour coding from me.
WH Smith (LON:SMWH) - up 11% to 1,366p (£1.79bn) - Trading Update [in line] - Paul - NO COLOUR
Strong peak Q4 trading (to 31/8/2024), but FY 8/2024 only in line with expectations. £50m share buyback. Received £85m from pension scheme buyout, with no future liabilities.
Paul’s view - looks fully priced after today’s rise, I’m not sure that in line justifies an 11% rise. Good to know pension scheme now gone. I dislike the geared balance sheet, with NTAV negative £(173)m.
Pebble Beach Systems (LON:PEB) - up 18% to 13.0p (£16m) - Mentions NVIDIA! - Paul - AMBER
“Pebble announces support for NVIDIA Holoscan for Media to drive flexible, cost-effective and sustainable media architectures.”
No indication of any financial effect from the two companies presenting jointly at a exhibition in Amsterdam shortly.
“The PRIMA platform works seamlessly with Holoscan for Media, and teams from both companies will be on hand at IBC to discuss the potential of the integrated technologies.”
Paul’s view - I don’t understand this announcement. But it sounds good, mentioning NVIDIA, which seems to have triggered some buying interest in PEB shares.
Summaries
Trustpilot (LON:TRST) - up 9% to 210.5p (£881m / $1153m) - Half Year Report - Graham - GREEN
Pleasant news for shareholders as we learn that adj. EBITDA is trending towards the top end of market expectations for the full year, thanks to the beneficial effects of operating leverage (costs becoming smaller as a percentage of revenues). A new £20m/$26m buyback is announced and I remain happy with my positive stance.
Gaming Realms (LON:GMR) - down 4% to 36.2p (£107m) - Interim Results - Paul - GREEN
Strong H1 results, but a vague outlook comment introduces a little doubt. They need to improve how these statements are drafted. It's an impressive growth company, on a remarkably modest rating, so it has to be GREEN again. I hope we haven't missed anything, with my only slight question mark being re cashflow, as explained below.
Ricardo (LON:RCDO) - down 2% to 508p (£316m) - Preliminary Results [FY 6/2024] - Paul - AMBER
FY 6/2024 results are in line with expectations. Most of the underlying profit comes from another year of heavy restructuring adjustments. Declines to say whether outlook is in line or not. Balance sheet just about OK, I'd like to see further debt reduction. Cashflow not as good as they make out. So even though I have a perception that this is a good business, the numbers don't excite me. Could be a takeover target, as this sector has seen generous bids before.
GYM (LON:GYM) - up 8% to 156p (£279m) - Interim Results - Paul - AMBER
I try to consider the bull arguments, as well as the obvious bear points (it doesn't make any profit being the main one). Overall it's a weak business model, and over-priced in my view, so only a very grudging AMBER, reflecting that the bank situation is now sorted, and trading is improving.
Paul's Section:
GYM (LON:GYM)
Up 8% to 156p (£279m) - Interim Results - Paul - AMBER
Leading low cost gym operator, The Gym Group, announces its interim results for the six month period ended 30 June 2024.
The investment arguments here are very simple -
Bull - see comment below from BurntOnions. Price rises for customers (+9%), and increased customer numbers (+3%) gives operational gearing (gross margin almost 100%), sticky customers, savings on energy costs, strong cash generation. Shares in a nice up-trend. Improving broker forecasts (now reached breakeven EPS).
Bear - doesn’t make any profit once large depreciation costs are taken into account. Rolling out a format that isn’t profitable - why? Capital-intensive. No barriers to entry, and lots of competition. Little to no economies of scale.
As you can see from the highlights, it’s just about achieved breakeven at PBT -
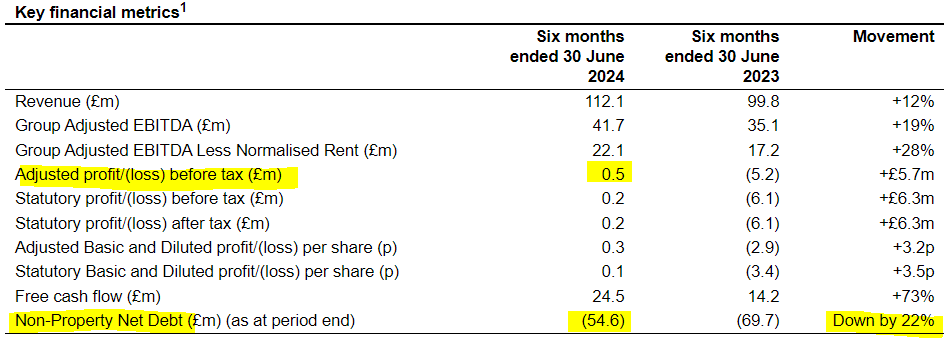
A useful reduction in net bank debt, through restricting new site openings (and the relevant heavy capex) to 4 in H1.
Bank facility is £90m, signed in June 2024.
Outlook - sounds upbeat -
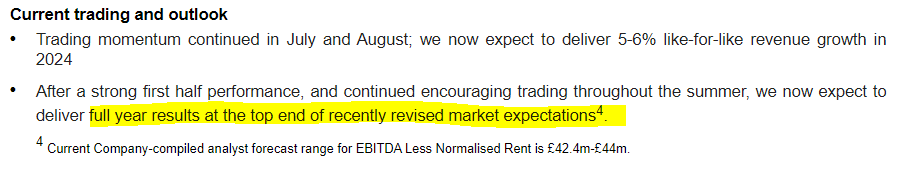
Trouble is, this EBITDA translates into zero profit. You can’t just ignore depreciation charges, that makes no sense at all to me. Operating at breakeven, all that means is the company is slowly recouping the cost of the site fit-outs & equipment, and nothing more. So why would you keep opening more sites, knowing that your return on investment is basically nil overall?
Cash generation is not actually that good in H1. Operating cashflow of £52.0m is a fantasy number. The following cash flows use up most of it - £3.3m capitalised development spend or software, £15.2m + £7.7m lease repayments, £3.4m bank interest, and £12.2m physical capex, leaves £10.2m remaining cash generation in H1.
It says in a table that £11.2m of the capex is expansionary, implying only £1m is maintenance capex, which surprises me, as that seems very low.
Hence why the company gets to a higher free cashflow number of £24.5m, because it doesn’t include the cost of expansionary capex in that number. Fair enough, I suppose.
An employee benefit trust is buying up free shares for Directors, a £1.5m cash outflow in H1.
Balance sheet - NTAV is a modest £36m. Note that it has favourable working capital, with little inventories or receivables, but a fair bit in current liabilities, so the suppliers help fund the business. Ignoring depreciation doesn’t stack up for me. The accounting policies are very clear - fixed assets are depreciated over their estimated useful lives, so there shouldn’t be much (if any) up-front effect that BurnedOnions suggests, in my view -
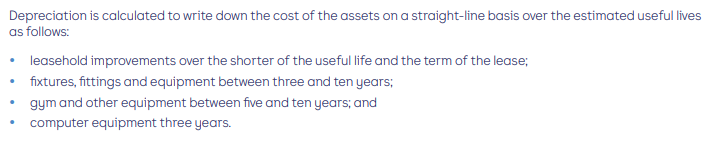
From the last annual report, I see that £94m cost gym equipment is now heavily depreciated at NBV of £26.8m, suggesting that its equipment is now generally quite old, and hence there could be a hefty repair & replacement cycle coming up.
The bulk of fixed assets are leasehold improvements (NBV £140m at end 2023), but if you can’t agree a higher rent with the landlord at lease renewal, then you have to hand in the keys and walk away.
Paul’s opinion - unchanged really, it’s not a very good business model. It didn’t make consistent profits before covid, and it’s only just reached breakeven after covid. The breakeven being a good result as it’s cash generative argument doesn’t stack up. You have to recoup the cost of your fixed assets as a bare minimum, not as a satisfactory level of performance. There’s a reason GYM has paid hardly any dividends in its whole life - because it doesn’t generate cash beyond the cost of its capex.
The bull case I could see working is if GYM is able to significantly grow revenues further, which on almost 100% gross margin could transform the bottom line eventually maybe. At £279m market cap, that positive outcome is already priced-in, but hasn’t happened yet (and may never happen).
The bull case doesn’t stack up for me, but the market likes it, and the shares are going up, so it doesn’t matter what I think!
I upped it to AMBER last time, since the bank debt situation is now sorted out, and trading is improving. But I still fundamentally think this is a lousy business model, and the shares are over-priced now. So it’s a distinctly unenthusiastic, grudging AMBER.
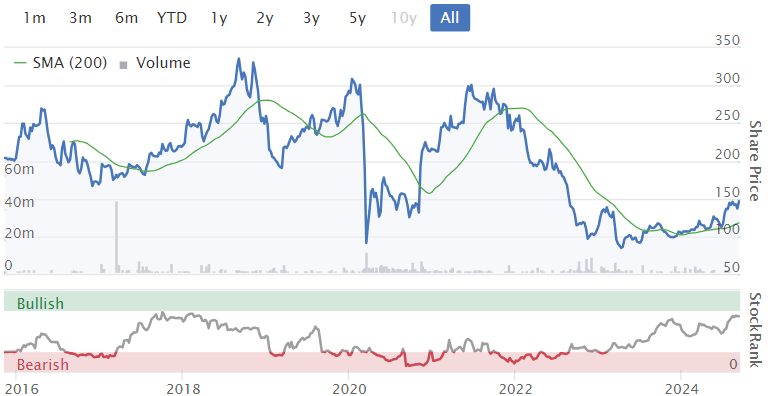
Since listing, it's been a share that comes in & out of fashion with investors, plus of course got badly walloped by the pandemic -
Ricardo (LON:RCDO)
Down 2% to 508p (£316m) - Preliminary Results [FY 6/2024] - Paul - AMBER
Not the clearest of self-descriptions -
“Ricardo plc is a global strategic, environmental, and engineering consulting company, listed on the London Stock Exchange. With over 100 years of engineering excellence and circa 3,000 employees in more than 20 countries, we provide exceptional levels of expertise in delivering innovative cross-sector sustainable outcomes to support energy transition and environmental services, together with safe and smart mobility. Our global team of consultants, environmental specialists, engineers, and scientists support our clients to solve the most complex and dynamic challenges to help achieve a safe and sustainable world. Visit www.ricardo.com “
It says performance is “in line with the board’s expectations”.
Order intake - fell 5%, but from record levels in the prior year.
Volatility in some markets.
Revenue (continuing ops) up 7% to £475m.
Automotive & Industrial returned to profit in H2.
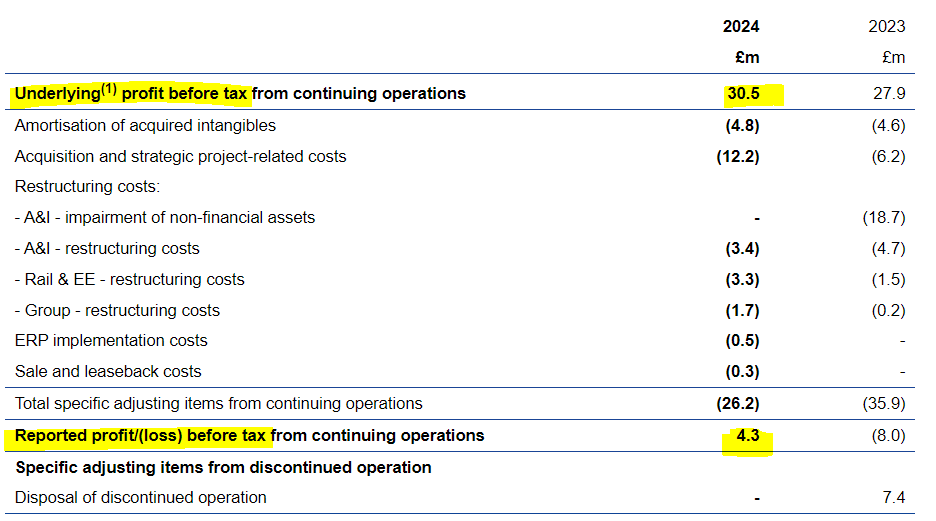
Underlying PBT of £30.5m, up 9%
Statutory PBT only £4.3m, so lots of adjustments
Basic underlying EPS 35.9p (up 7.5%) = PER 14.2x
Total divis up 6.2% to 12.7p (yield an unremarkable 2.5%)
Net bank debt £59.6m (reduced 4%) - c.19% of the market cap. At 1.25x it’s well within the covenant limit of 3.0x
Adjustments do seem considerable, in both the most recent years - so it’s up to you to decide how real the adjusted profits are - or if it’s one of these people businesses that seems to be constantly doing expensive reorganisations? -
Outlook - another case where they duck the question of performance versus market expectations for the new financial year, choosing more vague language -
“Looking forward
Ricardo is gaining good momentum to deliver its five-year strategic plan communicated in May 2022. We enter the new fiscal year with a similar order book level to the record one we achieved last year, and, through our solid pipeline visibility, we have good confidence in performance as we enter FY 2024/25.
With our expertise in environmental and energy transition, there is a real opportunity for us to do even more in supporting governments and the private sector in delivering a net zero pathway for future generations.
We also know that for us to be a pivotal part of change, we have to continue to grow and improve our business. By doing so, we can extend our reach, supporting even more clients and ensuring that our teams across the world continue to deliver meaningful work, knowing that the projects are delivering maximum impact.
The more we can do to accelerate our transformation, the more value we can create for all our stakeholders.”
Balance sheet - no better than adequate I’d say. NAV £165m includes £130m of goodwill & similar, so £35m NTAV.
Gross bank debt looks too high at £107m, although partly offset with cash of £49m - but cash is often window-dressed for year end dates remember. I’d prefer to see borrowings come down further.
Good news is that the pension deficit contributions seem to have ended.
Cash generation - improved, thanks to squeezing receivables a bit. But it’s not an impressive cash generator. There was £8m capex in FY 6/2024, nearly all of that being capitalised development costs. Take off leases, and divis, and there’s nothing much cash remaining. So a question mark over fairly weak cash generation. Strangely though, Panmure Liberaum heads its update note today with “Strong cash generation”, which is not what the figures I’m looking at say to me. Cashflow is better than the previous year, but not impressive overall in my view. It would make more sense to suspend divis and focus on building up the balance sheet, and reduce debt somewhat in my view, because debt is expensive now - note that £8.5m finance costs in FY 6/2024 consumed two thirds of the £12.8m statutory operating profit.
Paul’s opinion - I’ve always had a generally positive view of RCDO as a decent quality business, but seeing all the adjustments today does remind me that it seemed to get itself into quite a pickle which has taken several years to sort out. Are all those exceptionals going to suddenly stop? I don’t know.
Liberum has today slightly lowered forecast EPS for FY 6/2025, from 42.1p to 40.3p (down 4%) and a similar drop of 5% for the following year. That gives a new year PER of 12.6x, which looks reasonably attractive value to me. Add on the bank debt though, and it would be higher. Priced about right perhaps?
These consultancy firms can attract surprisingly high takeover bids, we had a flurry of those a few years ago at full valuations. I see Gresham House holds 18.4%, and I think they agitated for a takeover bid at something else they held recently.
Overall, it looks quite interesting, probably no more than an AMBER for me - which is a clean bill of health remember, not a negative.
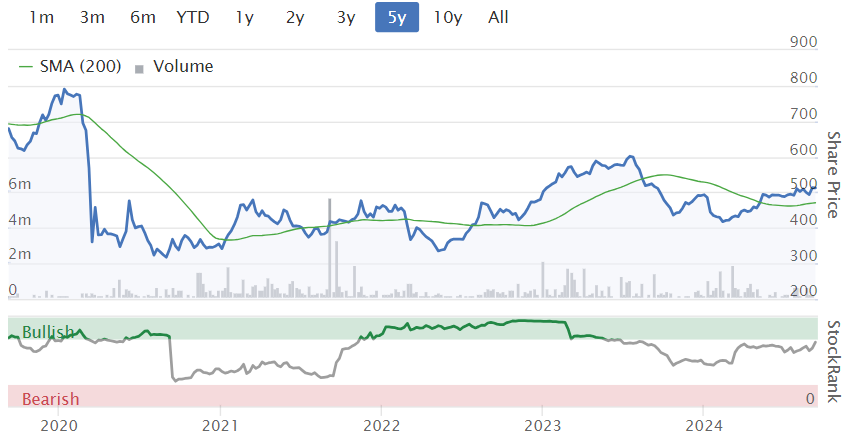
Gaming Realms (LON:GMR)
Down 4% to 36.2p (£107m) - Interim Results - Paul - GREEN
Gaming Realms plc (AIM: GMR), the developer and licensor of mobile focused gaming content, is pleased to announce its interim results for the six months to 30 June 2024 (the "Period" or "H1'24").
Mixed growth, but the core revenues are up an impressive 28% (all organic growth), and very good overall profit growth -
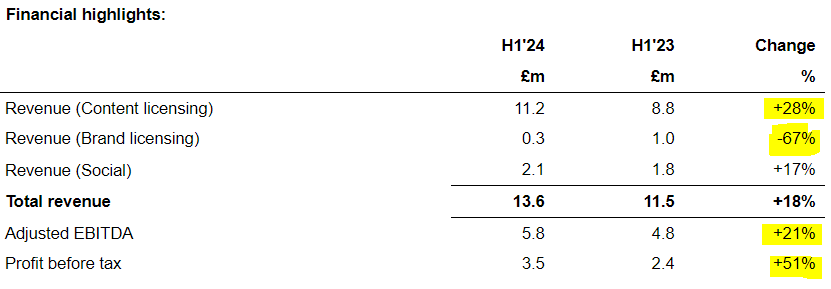
Brand licensing - why has this smallest activity dropped -67%? The explanation provided has left me none the wiser -
“Brand licensing revenue reduced 67% to £0.3m (H1'23: £1.0m) due to two brand deals completed in the same period of the previous year”
Thinking about it, these might be saying that last year saw some one-off deals that haven’t repeated perhaps? Does it matter? Not really, as it’s the core (growing) revenue stream that matters. This is recurring revenue and seems to consistently grow each period, due to the popularity of the Slingo game.
Ah the fog has cleared! Further down the announcement it gives a clearer explanation -
“Revenues from the Group's brand licensing activities, which are non-core, were £0.3m in the period (H1'23: £1.0m). This reduction is a result of two brand deals completed in the previous period, including a one-off £0.6m that did not repeat in H1'24.”
Cash continues to accumulate on the balance sheet -
“Net cash at period end up 28% to £9.6m (Dec'23: £7.5m) with continued strong cash generation”
Post period end - strong growth continued -
“Licensing revenue increased 33% in the two months post period-end compared to the same period in 2023”
Outlook - GMR doesn’t seem to realise that investors usually want a clear statement confirming full year expectations. Instead we get a rather waffly & unclear alternative, which is bound to raise questions amongst investors, which is probably why the share price is down 4% at the time of writing -
“Looking ahead, the Group is well placed to capitalise on this momentum and deliver further growth in new and existing markets.
Our focus for the remainder of the year is to further expand our international presence in new markets, while continuing to grow in existing markets with our partners.
In August we launched our content in West Virginia, the fifth regulated iGaming state the Group's content is distributed in. After the period end, the Group was also granted an iGaming supplier license in British Columbia, where we expect to launch our content shortly.
These market expansions will be supplemented by premium game launches in the second half of 2024 including Slingo Fowl Play and Slingo Press Your Luck.
The Board remains optimistic around FY24 financial performance.”
Is that in line with expectations? Who knows.
Have brokers changed forecasts today? The next port of call when uncertainty has been created in an RNS.
Canaccord says this morning that it’s leaving forecasts unchanged, and that they look “well underpinned”.
FY 12/2024 forecast is £27.1m revenues, adj PBT of £8.8m (up 63% on 2023), and adj EPS of 2.33p (up 15%).
I’ve tried to find out why EPS is only forecast to grow +15% in 2024, when PBT is +63%. Must be something to do with tax, because the number of shares in issue hasn’t changed much (the only other factor that could impact EPS). The H1 results in 2024 do show a £253k corp tax charge, vs a £160k credit in H1 2023. So it looks as if tax could be normalising after previously using up brought forward tax losses? Yes here we are, the FY 12/2023 results showed a £758m tax credit that took PBT of £5.17m and made it a larger PAT of £5.93m. So a reversal of that in 2024 looks likely the reason forecast EPS growth is modest.
Valuation - using the 2.33p Canaccord 12/2024 forecast, at 36.2p/share, the PER is currently only 15.5x - that seems remarkably cheap to me, but this share has looked strangely cheap for some time. I’m not sure why.
Balance sheet - is strong, and this is a capital-light business model remember.
NAV of £28.1m becomes £14.3m NTAV once I remove intangible assets. This includes £9.6m of gross and net cash. All creditors are only £3.8m, so it’s more than adequately funded.
Cashflow statement - is healthy, with £4.46m post tax operating cashflow in H1. Although capitalised development spend consumes just over half this, at £2.43m, giving a free cashflow of £2.13m in H1.
Paul’s opinion - every time I look at this share, I’m scratching my head as to why the valuation is so modest for such an impressive growth company. Strong, repeated organic growth like this usually comes at a large premium, yet here we are being asked to pay 15.5x PER.
What have we missed? I can’t think of anything, other than the cash generation not being as good as profit, due to capitalised development spend exceeding the amortisation charge, but that’s not a deal-breaker.
It has to be GREEN from me, with this popular game being further rolled out to more & more customers, generating a growing high margin revenue stream. Lots to like here, providing nothing unforeseen goes wrong. There are some presentational issues with this results statement too, which seem minor own goals.
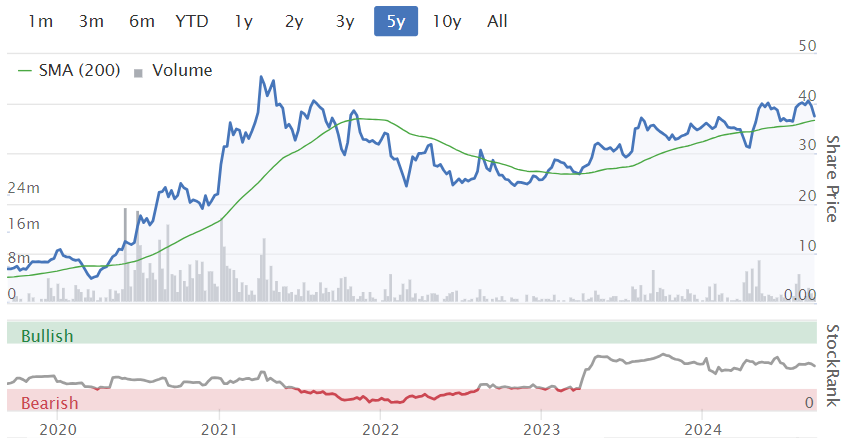
Graham’s Section:
Trustpilot (LON:TRST)
Up 9% to 210.5p (£881m / $1153m) - Half Year Report - Graham - GREEN
Financial performance at Trustpilot just keeps going from strength to strength.
Please note that we covered the corresponding H1 update in July, here.
Here are some of the highlights from today’s interim report:
Revenue +18% (£99.8m)
Adj. EBITDA +86% (£10.6m) is ahead of expectations.
Operating profit £1.8m (last year: £2.1m loss)
The strong EBITDA result is attributed to “improved operating leverage across the cost base, but particularly in general and administrative expenses”.
The full-year adj. EBITDA result is now expected to come in “towards the top end of market expectations”, with those expectations being for adj. EBITDA of $18 - 22m.
CEO comment:
“When I joined Trustpilot a year ago, I said that I aimed to bring greater strategic clarity, rigorous execution, and increasing profitability. We have made good progress across these areas.
“Our strategy is clear. We are an open, trusted review platform for consumers to help each other make the right choices, and provide insights for businesses to build trust, grow and improve. By targeting key focus markets and verticals, we maximise the inherent network effects of the platform…”
I’ve been bullish on this one because I see it as a potential monopoly, with those network effects keeping it growing and profitable. The simple argument is that the more people (and businesses) who use Trustpilot, the more useful it becomes, making it even more difficult for competitors to make progress.
A KPI worth particular mention: Annual Recurring Revenue is up 17% to $211m. In the absence of meaningful profits, this is a metric I tend to focus on.
Cash finished the period at $76m, down over the six month period as Trustpilot spent $26m buying back its own shares.
With this strong cash pile behind it and worth more cash generation expected, the company announces today a new $26m buyback.
Regional breakdown - Trustpilot’s success is most advanced in the UK, and the UK contributed 40% of bookings in H1. But booking growth is good even outside the UK: there is 23% growth in North America, and 16% growth in “Europe and Rest of the World”.
Taxes - are complicated by the recognition of prior losses as an asset. So it’s fine to completely ignore the after-tax profit numbers published today.
Graham’s view
I can’t change my stance on this after a strong interim report with full-year results now heading for the top end of market expectations.
Just take a look at the trend in market expectations. This is before today’s news:
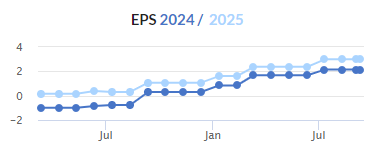
Sometimes you have to let momentum run. In this case, as an analyst, I’m happy to let my winner run and stay positive on it.
But I’m not completely ignoring the valuation. We have the following multiples:
Enterprise value to trailing ARR: 5.1x according to my calculations.
Price to sales: 6x, according to Stockopedia.
Yes, it’s expensive, but I don’t consider these to be “bubble” valuations. Given the quality and momentum of the business, I think they remain attractive.
But as I said last time, if growth slows or if valuation were to change dramatically, (e.g. P/S of 10x), then I would change my stance. But for now I remain comfortable with GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

94 comments
Hi Boon, This news story tonight found under Walmart (NYQ:WMT) might be of interest to you and Strawberry dreams
US lawmakers urge Biden to close tariff 'loophole' for Chinese small package imports
What I found interesting is that they say Amazon.com (NSQ:AMZN) and Walmart (NYQ:WMT) also benefit from the ‘deminimus loophole’ . I did a bit of digging to try understand how they benefit and came across this link which explains it and that Amazon.com (NSQ:AMZN) and the United Parcel Service (NYQ:UPS) and FedEx (NYQ:FDX) lobbied for it. The Loophole That Lets Amazon Deliver Uninspected Imports to Your Door
Thanks for sharing! Interesting, I did not know that Amazon and Walmart benefitted too.
Presume this is Amazon Marketplace and Walmart's equivalent? Where third party sellers fulfil items sold? Possibly from overseas? Maybe not China warehouses, but like Canada (so a Canada seller could offer the product across USA and Canada?)
Thanks for flagging up the bombed out shares everyone always useful to get heads up ref stocks that have been bombed out for little to no reason (or worse) . Having had my limit sell price reached on keyword studios stock recently - i have have some spare wonga too splash the cash on too - that makes refreshing change. Just a shame that Whitbread (LON:WTB) whibread stock has rallied 10% from recent lows - sigh
Not specifically mentioned here but TT electronics (LON:TTG) stock is also down nearly 20% from its recent spike up high watermark - note the spike up wasnt really on any specific news so the drop is kinda just putting things back were they were a day or so after the most recent update. The chart here to a non chartist loks pretty horrendous hey ho perhaps 130p - 140p is a support level
Well what a bruising day. I can accept risk, but when Chariot (LON:CHAR) announce in August 20th " Anchois-3 drilling and flow testing operations are expected to take approximately two months." So to announce bad news today does feel like shareholders have been uninformed at best, misled at worst.
Gaming Realms (LON:GMR) dip is another disappointment. I'm baffled by this.
I had a quick look at Chariot (LON:CHAR) ChrisR and looks like a classic retail punt over-reaction to me. The brokers removed a small amount of risked NAV for the target that didn't encounter anything and that wasn't actually a main target so a 40% drop just feels like punters bailing manically. Anyway looks like the broker still has a risked NAV of 40p on it.
But in reality that is the joys or otherwise of oil and gas exploration. You often see massive overshoots in both directions that quickly correct. I've lots count of the number of these companies that announce a find, go up spectacularly and then lose it all in execution phase. someone once said to me that it is best to trade them in waves rather than holding waiting for results.
Alpha International (LON:ALPH) more director dealing today after the recent drop - this time by the current CEO:
Alpha Group International plc (LON: ALPH) announces that it has been notified today that Morgan Tillbrook, Chief Executive Officer, has purchased 24,321 ordinary shares in the company.
https://newsfile.refinitiv.com...
I meant to post about this yesterday (the change in CEO at Alpha International (LON:ALPH) .
It was a surprise to say the least, I hadn't seen it flagged before. It's not fully clear why it happened, Morgan Tilbrook doesn't give an actual reason for leaving, although it all sounds very friendly.
It sort of sounds like the board made the decision to change him, but Morgan Tilbrook says it was his decision to sep down (could be b*llocks), and it doesn't seem to fit with the performance of the company (i.e. generally very good), the comments made by all parties (very positive) or today's purchase of shares by Morgan Tilbrook (c. £500k).
So all in all, quite confusing, but generally speaking I will be a buyer if the price settles down at £20 or lower.
Thanks
Chris
What’s going on with Warpaint London (LON:W7L) today? Treeshake or should we strap ourselves in for bad news?
Is there going to be any write up on Sylvania Platinum after their results yesterday? I see Investors Chronicle have canned them? Thanks
Hi WhizzyKid,
No sorry there won't be a writeup on Sylvania Platinum (LON:SLP)
As mentioned in the explanatory notes every day, we don't cover some specialist sectors like natural resources -
"We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos)."
The reason being that there are lots of shares in this sector, and I feel specialist knowledge is necessary. Explorers usually fail, and producers are subject to volatile demand & price. All in all making it a very difficult sector that I've tended to steer clear of in my 25+ years investing.
You're very welcome to discuss interesting resources shares in the reader comments here. I know SLP has been liked by some subscribers due to its value characteristics, apparently cheap. PER of around 5, and a big & rising yield do look attractive, but the trend of earnings is very negative -
Quickly looking at yesterday's figures, profits collapsed ($7.4m op pr vs $62m LY), but the cash pile stands out at $98m (and no debt). 3p total divis + buybacks. Almost half the profit came from interest on cash pile. Balance sheet overall is very strong. Market cap is £114m, with net cash supporting £75m of that (after converting into sterling, from dollars).
Looks quite interesting as a value investment. But it depends what you think will happen to the selling prices of the metals that it mines.
Regards, PAul.
Warpaint London (LON:W7L) being smashed today. Disconcerting to say the least!
As with IG Design (LON:IGR) , perhaps this is the result of booking of gains in anticipation of an increase in CGT rates in the October budget? Both shares will have plenty of people sitting on gains
Agreed. There seem to be many small caps turning down now which had good share price growth over the last year or so. Too many and varied to be a coincidence surely.
Anything where investors have large capital gains is surely very susceptible to profit taking given the Starmer/Reeves concerted effort to destroy UK economic activity by increased regulation and ramping up taxes, including in all probability CGT.
Hope this doesn’t overstep the mark in terms of political commentary but can see no other reason for such concerted selling in the shares of highly performing companies.
AIM is in a strong down trend, has given up almost all gains of the past 10 years. Investors anticipating removal of BPR perhaps?
I've sold out of IGR today. The persistent small selling and drip, drip in the share price convinced me to take what's left of what was a very decent profit. Reconsider when things settle down. Minor chart support at 160, but no idea where the bottom will be.
I would have thought most non leveraged investors have most of their shares in ISAs?IG Design (LON:IGR) isn't NVIDIA (NSQ:NVDA) .. yet..!But yes as an IG Design (LON:IGR) i did half wonder why the velocity of the recent move downwards.I guess we have to wait until the next trading update.Decent buying opportunity perhaps if you still believe in the company and management's story as i doubt anyone knows anything unless another Sky story is about to break!
Results on Tuesday. Every time you expect bad news from Warpaint London (LON:W7L) they suprise on the positive side. I think Paul was looking to buy if they fall below £5. He may well get his chance. One of my largest positions so taking a hit today.
I can't see any news. Is there any? For what its worth closed on the 150d ma ! Sorry just got in....
@ANP Strong half year numbers from ANP today and share price has responded accordingly - but still more than 50% down on peak three years ago. Performance last 3 years affected by relatively weak sales , but this may now be changing - up 11% in H1. Results would have been better if sales in USA had not been lower, but they do sell across the globe and most had improved. Outlook comments particularly encouraging- now well into the second half and enhancement being seen in both volumes and margin. Bulletproof balance sheet, own their freehold premises (with room to expand if needs be), good cash generator, decent dividend and plenty of cash in the bank. My type of share, held many years, but always dyor
Yes, some decent figures today from Anpario (LON:ANP) .
Good to see some sales growth but I just wonder if the business is just not big enough ! Only £30m sales and 115 people.
- do they spread themselves too thinly by trying to tackle every global market ( although presumably they use local distributors) ?
- its not that clear to me what the genuine market opportunity is. Its products seem very susceptible to being quickly dropped by customers whenever they (the customer) experiences any crisis or cost pressures ie is it viewed as a luxury, not a necessity ?
- clearly the executive board are very competent but none of them have any market or product background as far as I can see. So perhaps there is a lack of real market understanding and entrepreneurship at the top of the organisation ? Although I note that a recent non exec board appointment does indeed have that background, which is a good step in the right direction. And no doubt the day to day management team have some highly qualified individuals too.
They do use distributors although there are a number of overseas subsidiaries. The global markets for pigs/ poultry and fish feed additives must be vast and ANP is indeed a tiny player - bit surprising they have not had approaches whilst struggling last 3 years. Agriculture markets notoriously difficult to implement changes, but legislation to ban antibiotoics as growth promoters should gradually benefit Anpario products. Factory improvements made in the lean times mean high operational gearing, so if they can really move the sales there should be solid reward. CEO has around 20 years experience in the industry (joined the board when acquisition made 2006).
Thanks for those useful comments stuart and apologies for getting it wrong about the CEO.
IG Design (LON:IGR) in steep decline of late. Profit warning coming? Shipping costs have risen sharply and £ strong. Market always ahead of us PIs.
IG Design (LON:IGR) The daily volumes look pretty low, but it is quite concerning that they have dropped so much, although undoubtedly I think they had got ahead of themselves following their last update.
Whilst the update was positive and they appear to be moving back towards their targets I think there has been a lot of profit taking going on.
I have no additional info, but whilst the shipping cost increases recently won't have helped companies, those that are good at managing costs and potentially hedging some of those in this area can navigate through this period eg. Luceco (LON:LUCE) recent results. Shipping costs are now dropping again, so hopefully just short term noise - if it's not raw material costs, its power costs, labour costs, shipping costs or some other challenge - but that's why management get paid.........to navigate these various pressures.
Philip Meeson sells 5 million Jet2 (LON:JET2) shares. No price mentioned. Shares tanking.
"Philip's rationale for the transaction has been driven by personal financial considerations alone."
Presumably worried about IHT and CGT implications of the budget on October 30th. How many other insiders will sell ahead of that?
https://www.investegate.co.uk/...
Jet2 (LON:JET2)
i would say this timing is poor (probably terrible) bearing in mind they sidestepped providing updates ref current year trading on recent update. Obviously he knows how trading is going and they have chosen not to update us !!! - they didnt even take the opportunity to say they were on track. So i can see why the stock was completely hammered - imho its completely self inflicted.
I understood the explanations of not updating ref trading previously given - but this really doesnt help. I would say i am not perosnally reading any issues with regard to this sale - dont blame anyone for not being as generous as me with their thoughts.
Your rationale may well be correct and I would agree timing is poor, but given current market volatility I'm not sure I'd describe a fall of less than 5% as tanking
Currently abroad and internet a bit hit and miss. I see Property Franchise (LON:TPFG) released interims yesterday and am wondering whether the SCVR might have time to include the results in a catch-up at the end of the week. No problem if unable to do so.
Sorry to hear about your misfortune with keys Paul. I am sure most of us have been there at one time or another.
All the best
REA Group confirmed its non-binding offer to Rightmove to acquire the entire company (305 pence in cash and 0.0381 REA shares for each Rightmove share) has been rejected by the Board of Rightmove.
The offer valued Rightmove at 705 pence per share, or approximately £5.6 billion, representing a 27% premium over the 30 August 2024 share price and a 31% premium over its 12-month average.
edit: Not sure why the red flag, here's the link to the RNS.
For those of you who are wondering why Sylvania Platinum (LON:SVP) has taken a dive it looks like its because Investors Chronicle has gone negative on it. Interestingly the share chat on ADVFN seems to disagree with IC.
Thanks for sharing
Sylvania Platinum (LON:SLP) not SVP
Thanks Berksbee. Appreciate it
SLP Bit of a mixed bag for me. Bought in 2018 at 18p. In 2021 the price dropped over 10% on results, so I sold half at 98p. In retrospect I should have sold the lot when Rhodium prices shot through the roof. Hindsight is 20/20.
I found a good chart of Rhodium here: https://tradingeconomics.com/c...
You can see from about mid 2023 prices became stable and relatively flat, well above the 2019 values. The curious thing is that you can see an almost identical pattern in coal and palm oil. It doesn't replicate across all commodities, but the similarities are striking.
The $64000 question is: have the commodities reached a new "permanently high(er) plateau" so to speak, or will they revert to their pre 2019 levels?
I still hold, but that shouldn't be taken as proof of anything.
Somero Enterprises #SOM interim results presentation by management at 3pm today, following on from results released 29th August. Register here.
On Boohoo (LON:BOO) .... didn't they make a huge song and dance about the HUGE investment in a USA warehouse, how this would be the key to increased growth in the USA, as they could then save money on shipping costs, and customers would get their orders much faster?
Seems like today's RNS is a huge PR-sugar-coating of a "mea culpa" u-turn on their USA strategy. Why would anyone in the USA buy from Boohoo when shipping will take longer, just as long as Shein and Temu, which will be cheaper?
I suspect in 2 years time, when the USA business has shrunk further, they'll announce another initiative to close down the USA operations, and focus just on UK and Europe...
---
I've got a cynical view here on Boohoo...
The way they have announced this USA retreat, it is clear that management in control (aka founding family) really don't care about their other shareholders and willing to communicate to them in a PR-spin-style. They've already taken their millions out, they're just in management positions to keep themselves busy, draw down some more salary, and maybe control the transfer of assets / etc out of the company stealthily....
Don't think they are interested in turning around the company and delivering for shareholders.
They did make a song and dance about the US expansion think with a big investment in new modern warehouse. Given the founders still have significant ownership would hope they have their eye on the share price as their LTIPS won’t be kicking in.!! Got my hands burnt holding this share, given there in a market where it’s uneven rules + compition don’t think they will last Shien can undercut them and the realty is the customers don’t really care how or where their clothes are made the price matters!!
Was it not Boohoo were Management used their discretion to award ehhh themselves some or all of their LTIP shares after they failed miserably to meet the criteria?
I know they have attempted to implement a new LTIP as the company/SP was doing so badly that they had no chance of the old one paying out. Obviously, the minor detail of the company doing badly under current management is no reason for said management not to be entitled to their continued very generous LTIP, which is also, I believe, nil cost.
The track record of Management here is plain to see. Their main, I would be tempted to say "only" concern, is to transfer money from the company/shareholders, to themselves. Shareholders are barely an afterthought.
US regulators are becoming more interested in Temu and Shein and i'm kind of surprised with Lina Khan at the FTC currently still they haven't already.There are some specific safety concerns about baby and toddler products and the obvious de minimis shipping loophole.'“We seek to better understand these firms, particularly their focus on low-value direct-to-consumer — sometimes called de minimis — shipments and the enforcement challenges when firms with little or no U.S. presence distribute consumer products through these platforms,” the commissioners wrote.' A lot of their commercial advantage seems to be due to them exploiting this rule and i'd be suprised if big US companies let it slide.However that said a lot of UK companies have 'failed' in the US even without PDD Holdings (NSQ:PDD's sheer size and commercial practices.
Indeed, in the USA I've been tracking the news/chatter on this, and it looks like various parts of the government - US Borders and Custom, FDA, other parts... even representatives in the House, are starting to coalesce to tighten the rules on de minimis parcels from overseas, which is how Temu and Shein stuff gets in.
Nothing will happen before 1st Jan of course, with the change of government. But I think we could see some handicapping of Temu and Shein next year in the USA, which makes Boohoo pulling out now all the more puzzling. At least wait another 6 months to see the situation.
Unless, of course, the cash burn situation is really dire right now...
Stock picker Simon Thompson of Investors Chronicle is convinced Equals (LON:EQLS) will receive an all cash 135p/share offer (see below) from the bidding consortium.
Writing today: "I would be astonished if a formal bid isn’t made by the end of next month, as the longer the bidders wait - the less attractive it is for shareholders to accept the cash given the intrinsic value of the business is only increasing with time".
https://www.investorschronicle...
End of next month Paul? I thought the extension was just until 2nd October? Does look quite a low risk 20% for a couple of months invested
(Famous last words )
Equals (LON:EQLS)
Paul, would you accept 135p.?
Looks too low to low given results.
The Pebble Group #PEBB H1 results presentation today at 1pm following results released on Monday. Register here.
It will be interesting to hear their take on the market for anyone interested in FOUR which has been very weak since results in spite of growing market share. Granted the promotional market is down yoy.
If anyone is getting upset about Trustpilot (LON:TRST) business model I suggest you read the FTC comments in the news release and their own respective website. Add to this that the CEO is aware of this and actively dealing with it and promoting the FTC requirements going forward - have a listen to today's webcast to verify.
If a business is not dealing with obvious challenges like this then the market will deal with it accordingly. Just a matter of time. I thought investing was about looking forward not backwards.
Here is the wording in the report...which seems to be an admission that the suppression of genuine reviews has historically been an issue.
Question is whether leopards change their spots, despite admitting they are leopards.....
We continually monitor the behaviour of consumers and
businesses on our platform. This includes ongoing analysis
of the impact of our reporting tools for businesses on the
content and reviews on Trustpilot. As the online reviews
economy has grown, platforms have been required to adapt
to changing consumer and business behaviours. Attempts
to suppress negative reviews through abuse of platform
reporting tools, threats against reviewers, or misleading
placement of reviews to hide or limit the prominence of
negative reviews has been an emerging trend. This behaviour
unmitigated risks misleading consumers and businesses
regarding a true and accurate representation of businesses
online. This industry-wide risk has been highlighted by the
Federal Trade Commission (“FTC”) in the US in its recent
proposed rulemaking around fake reviews, as well as other
regulators globally.
In 2023, following an analysis of our platform reporting
tools and potential gaps that could be exploited to suppress
genuine reviews, we released changes to our platform
reporting flows and processes within our Content Integrity
team to reduce the potential risk of genuine reviews being
removed from the platform. We will continue to monitor the
effectiveness and impact of these changes through 2024 and
expect to see a significant reduction in attempts to suppress
reviews on the platform. Further mitigations are outlined
across our key responses to our “confidence in our
commitment to trust and transparency” and “changing
and varied regulatory landscape” principal risks.
FWIW, I worked at Google at the same time as the current Trustpilot (LON:TRST) CEO. We never worked directly together but I had a strong impression of him at the time as 'one of the good guys' with a lot of integrity and I wouldn't doubt his commitment to improve transparency and honesty. I don't hold though and have shorted in the past.
There was no growth in the UK economy in July, official figures show.
"Economists polled by the Reuters news agency forecast the economy would expand by 0.2%."
"Among the G7 group of industrialised nations, the UK had the highest growth rate for the first six months of 2024."
i think the labour gov can take some credit for that they have done nothing but sow doubt and confusion since they came to power
Thanks for covering both WH Smith (LON:SMWH) and Rentokil Initial (LON:RTO) today, Paul. Even if only in brief comments. I enjoy and appreciate your forays into mid and large caps. I dislike both balance sheets as well, and most of my holdings are debt-free. However, I’m prepared to make an exception for both on the basis of their strong incumbency in markets with secular growth.
The venerable retailer is entrenched in every UK airport and many stateside as the “go to” for holiday reading and last minute purchases (travel adaptors, snacks) while travel volumes and spending just keeps rising ahead of GDP growth. I see this as a long term hold with an eventually improving balance sheet.
Meanwhile, pest control is a serious business in the US and Asia. And, while RTO is struggling to digest an acquisition that makes them the largest provider in the US, the ROW is performing well. A combination of self help - cuts are announced today - and demand growth in ROW ought to bring improvement. I’ve traded this once from 400p to 480p and I hope to do the same again, possibly with a higher target in the 500s given this is the third PW. On the theme I have a longer term view of Rollins (NYQ:ROL) which I bought a while back. For a fright, look at the PER. Intimidating!
Peak Paul! Love it.
Sigmaroc (LON:SRC) i hold
I am responding to Paul’s review of Sigma Roc’s half year results on Monday when he asked if there were any limestone experts who could help him better understand the company.
Whilst limestone is a remarkable mineral with plentiful uses that we consume in our daily lives, it isn’t necessary to know more about limestone.
I suggest you need to focus on the business model instead. Given one of your main areas of expertise, think of SRC as if it were a retailer that had cornered the market in a product that is in finite supply and cannot be manufactured by anyone else. This, in effect is what SRC did when they bought all the limestone quarries owned by CRH. This deal gives SRC the scale to dominate the market in western Europe and the UK and Ireland. There are many economies of scale to be extracted and little competition on price so margins should remain good.
Yes they have sizable debt but in my view it was a price worth paying for a once in a lifetime opportunity to acquire an awful lot of limestone in the ground. The company has a clear vision of where it is going and how to get there. They are also very entrepreneurial in seeking ways to be carbon neutral or even negative. The management team are experienced and highly capable in my view. We cannot live without limestone, there is no easy substitute so it is only a matter of time before demand returns to a more normal level. Lower interest rates will add a tailwind. Forget about it being a natural resources business and focus on where competition might come from and how big or small a threat that is.
British savers have at least £430bn of excess savings sitting in cash, putting them at risk of missing out on potentially higher returns from investments, according to a new report.
"Tom Stevenson, investment director at Fidelity International, said the UK stock market was trading “pretty close” to “absolute bargain territory”.
https://archive.ph/AzoHv
Following up on Equals (LON:EQLS) last week( I don't hold) ...
An interesting comment yesterday from the Ben Evans tech newsletter https://www.ben-evans.com/news...(consistently great - I recommend) providing some transparency on OnlyFans. (Fenix International limited https://find-and-update.compan... )
(BTW Great podcast Paul . Funny. of course ahem...the bikini clad melon smoothie maker is not really selling smoothies...)
Anyways - This from Ben Evans..
"Onlyfans is the only big company in its market with any real transparency - as a UK private company, it publishes a detailed set of accounts (as ‘Fenix International’) every year. There are now 4.1m creators and 305m users, both growing at close to 30% year on year; $6.6bn user payments, $1.3bn take rate; $485m net income and $172m in taxes. There’s no chance of an IPO, so the owner pays himself all the profits as a dividend"
Ooff. The oldest trade continues to deliver. For some. But i fear not the smoothie maker...
Facilities by ADF (LON:ADF)
Last night Harwood Capital disclosed a 10% stake in Facilities by ADF (LON:ADF) following the recent placing and retail offer to fund a significant acquisition - a positive sign for those of us who already hold?
Thanks Sheriff, I missed that RNS, thanks for highlighting, yes very positive indeed.
And those of us who hold once more as of this morning :-D
It looks so cheap.
Talking my book so take it for what it's worth, but with Gaming Realms (LON:GMR) , Facilities by ADF (LON:ADF) , Good Energy (LON:GOOD), Alumasc (LON:ALU) and a few more, it seems like crazy cheap bargains are back in the market again.
https://news.sky.com/story/uk-...
GYM (LON:GYM)
Superb numbers from GYM, they have managed to push through decent price rises and increase membership numbers at the same time.
I know Paul doesn't like it because of the depreciation factor but the reality is it is a cash flow machine, £57m pa on a 12 month basis against an EV of £312m (at the time of writing) and it looks like it is now making 52 week highs.
The depreciation will fall away in time as the largest element of it relates to building fit out costs which are largely non repeating items, so enjoy it while it lasts as it disguises the profits and keeps the tax bill down.
Here are some other metrics that I found interesting;
When KKR bought into PURE Gym 3 years ago they were buying in at an EV of £1.835 billion or £3,670,000 per gym and £1088 per member
GYM enterprise value is £312m or £1,316,000 per gym and £344 per member
For sure 3 years ago interest rates were lower and PE was a lot more free wheeling with the cash but that is a big difference in valuation metrics and one i find very reassuring as a GYM holder.
I think anything under £2 is a bargain but I would say that as I have been bullish on this stock all year, it's revenues are sticky, they are a very affordable activity, it is operationally leveraged and they are not exposed to ever increasing labour costs (utility costs is the main thing to look out for here).
Thanks.
Interesting post. My membership fee went from £19.99 to £23.99 a month and I was livid. The only other low cost option was pure gym at £23.99 so I had to swallow my laughable outrage. As you say it seems they had scope to raise prices without hitting membership numbers.
GYM (LON:GYM)
"My membership fee went from £19.99 to £23.99"
In the presentation posted today, there's a slide showing the company being on average cheaper than 2 competitors (JD and Pure Gym) and an aim to increase their prices for parity.
So the price rise you mentioned makes sense.
Thanks
A
https://www.tggplc.com/media/1...
I need to find a new "Stocks &Shares" ISA provider - I can analyse comparative data (charges etc.) myself but would appreciate any comments based on user experiences. Sorry if this question goes over old ground but I have not been able to follow the SCVR for several weeks.
I did this exercise a few months ago as I was looking to move ISA providers (from IG, but decided to stay put).
I have an Excel spreadsheet file. Happy to send over? It has 18 providers I looked at.
Find me on Twitter/Substack and DM me (link in my Stocko bio)? And I can attach and send over.
Thanks, and yes I would like to see your spreadsheet. I can't find a messaging facility here - could you please post your Twitter/X name? I can't log in to Substack for some unknown reason.
Here you go: https://x.com/boonfund
Hi Michael C - ISA providers
I hold UK listed shares & Investment Trusts, no Funds.
I have experience of 3 platforms :
Iweb - very cheap (£5 per trade, no annual fees), too big to fail (Halifax/Lloyds Bank), fairly basic, online only, disallow some "complex" investments at seemingly random times (EBOX), refuse to reclaim US witholding tax on UK listed shares (eg Somero). Surprisingly decent but clunky online support, but no phone line, and were excellent in handling my late mother's probate.
Interactive Investor - different pricing to Iweb but comparable. Large company, bit more flexible than Iweb, phone trades at online pricing where unable to deal electronically (eg EBOX). Good support. A bit painful in handling my late mother's probate - nothing serious, just hassle.
AJ Bell - Trading account & SIPP only. Recently reduced dealing fees, but still more expensive than Iweb/II. Everything seems slower than Iweb/II, support is v good.
I'd not want all eggs in one basket so, for my personal accounts use II & Iweb. Hope this helps!
I have the same three but am moving from ajb to ii. Agree in general with above but if starting out I would try Interactive Brokers. They are so slick.
All - thanks for ideas, I am dealing with power outage on our farm/business so probably can't reply again for a while
The latest comparison from Monevator of broker platforms and charges
https://monevator.com/compare-...
Paul, my sympathies for door locking - I locked myself out of my flat a couple of months ago. I bought a fingerprint lock and never have to worry about losing keys again. It was (surprisingly) easy to fit and could do it myself.
Remember to keep hold of your fingers though...
No fat fingers!
#cost not a great sign re: 13% discount especially at multi-year highs; makes you question it a little
Costain LON:COST
Interested to understand why Costain have been purchasing shares for cancellation at market rate when one of their largest shareholders were prepared to sell at a 13% discount?
Epwin (LON:EPWN)
An as it was update today here with company being on track to hit expectations - they seem to be holding their head above water in tough markets - I am happy with their current plans on minor acquisitions share buybacks and divis. No sign of any uptick in their markets and I note brickability also said similar today - so the uk home improvement / house building sector seems to remain at very subdued levels with no signs of uptick yet - happy to carry on holding here.
Trustpilot (LON:TRST) says the number of paying customers, net of churn, increased 2% year on year.
Sooner or later the market is going to focus on this number. Paying 70x earnings (Stocko figure this morning) seems crazy to me.
but why not focus on the diluted EPS figure which is on track to beat next year's (FY25) figure of 3.41c? In other words EPS is now forecast to grow at 100%+ this year. Surely, significantly increasing profitability is far more important for investors in Trustpilot (LON:TRST) ? I hold but always happy to hear bear case.
Trustpilot .
Lets just say im not a fan.
Just overpriced horrible company built on the internet book with extortion tactics to online retailers who were manipulated into joining .
No longevity in the business at all and retailers and customers are waking up to see this is a scamtastic opportunity .
They tried it with me at planet x and for a couple years we had a pretty bad rating but being stupid snd stubborn I told then to do one .
The scam is as simple as this
- anyone can leave a trustpilot reviiew
Lets imagine we have 1000 customers , and 1% have a bad experience . These are likely to post on trustpilot because they are not happy and “well tell everyone how shit you are on tristpilot” - which is also used by customers sometimes as leverage along the lines ”if you dont do xyz im going to say how shit you are on trustpilot”
Of your 990 customers everyone got what they orderred, on time , and are happy but dont go to trustpilot to leave positive review
Result is probably a 2/5 rating
UNLESS
If you pay trustpilot some wonga - these 990 customers receive an email kindly asking / reminding them to “come leave us a positive review” which of course shoots you up to 4.8/5
NOW
When you are say there on 2/5 rating - of course trustpilot come knocking and “Show you how to improve your rating” by just signing up .
And aa an added bonus you can get yoir negatives reviewed and removed if you are a member .
Its just legalised extortion but both customers and rettailers are waking up .
Horrible scumbag company model and deserves to go bankrupt for its manipulating methods and for 100% sure its been found out .
If you do not believe me
https://medium.com/@ryanbadger/how-trustpilot-extorts-businesses-91ca4b6a6f62
Should invited reviews be banned?
I performed an analysis of 9 million reviews posted on Trustpilot for businesses that invited reviews from their customers.
Trustpilot claim, “Generally we find that organic reviews tend to sway more negatively because consumers are more likely to be motivated to seek out the opportunity to share their voice if they have had a bad experience. By contrast, invited reviews, both automated and manual, tend to encourage those who have had a good experience to share their thoughts, when they may not have thought to do so without being prompted.”
It is true that organic reviews sway more negatively than invited reviews. However, this says more about the manipulation of invited reviews than it does about the nature of organic reviews.
Trustpilot (LON:TRST) planetx - I heard a very similar tale from an online retailer I use. Good honest straightforward salt of the earth hard-working guy who bends over back-wards to get you your order and not interested in paying Trustpilot
He noted that Trustpilot started downgrading several 5 star reviews that happy customers had left previously as he wasn't paying Trustpilot. Not a company I'd be comfortable investing in because of this but each to their own.
Yes, this is probably not a morally right business model by Trustpilot (LON:TRST) .
But then so is Google's with their paid ads, taking up pretty much all the page before you scroll down to the results.
In fact, Google makes is so that Brands have to buy paid ads for their own brand terms (i.e Nike), otherwise they will place a competitor ad (Adidas, On, Reebok, etc) above the Nike organic listing.
------
Is this ethical or moral? Probably not, if you ask a large swath of customers.
Is it legally wrong? No.
There is absolutely no whiff of regulators asking questions about Trustpilot. Not even by the EU Commissioner, which is pretty hard ass...
-----
Planetx, I do get your moral stance on this. I really do. But from a financial perspective, Trustpilot have figured out a way to create a legal money making machine...
(I do not hold in the Boon Fund, despite my defence of this company!)
Nicely put Boon. I read an FT article by a media professor who has coined the term enshittification, he was taking all the giant platforms to task for tying customers to their platforms and monetising everything.
Boon
Im not sure I agree .
Google - their paid ads are marked as paid ads and it is clear . incidentally I never paid google one cent in 25 years for paid ads
Trustpilot - my point is the rating is very high and retailers are more savvy so they cannot be valued so highly .
Here is what is happening / will happen
Retailers
- the old school / existing customers are now under pressure , they may stay eitj trustpilot because once signed up you tend to stick ‘with it . So probably a low churn rate .
But
NEW entreoeneurs / business owners are both more aware and more savvy, as are their customers .
So they will not get the new customers , simple as that .
It is going to become a dinosaur of a company, A flawed manipulative business model that is neither embraced , respected, nor needed by the new generation.
Might take a year or so but its time has gone this is not a future growth story deserving of a growth rating .
Its s sham that rode the wave and reached a high valuation but the next wave of businesses with smart owners know its limited just as much as readers now take their reviews with a pinch of salt .
Watch this space its not got the agility to adapt to grow or the current customer base to do anything more than fail to justify PE
I would never invest in Trustpilot after all the information about Jamie Wallis former MP emerged. He was the Bridgend MP who was convicted of failing to stop after a car accident . He had a trail of dodgy businesses. One long term one employed women in Thailand who had to speak fluent English. It was thought by most who investigated it that this business was about providing favourable reviews into Trustpilot and similar.
I agree about Trustpilot being a horrible company.
Curious to know how you booked your self catering accommodation with Trustpilot (LON:TRST) ?
Trustpilot (LON:TRST)
"the number of paying customers, net of churn, increased 2% year on year....Sooner or later the market is going to focus on this number."
Agreed.
Here are the numbers for any interested (although note that I calculate the YOY% increase in paying customers as 2.5%, not 2%)
Given the number of paying customers is increasing so slowly, I was trying to understand why bookings continue to grow so fast.
The answer appears to lie in the ACV (Annual Contract Values), which have increased by a whopping 18.1% YOY%.
This can't all be due to new large customers coming on board - it must surely be a material price increase for current paying customers too.
(please note that the first row here are published figures; the second row (check) is my own calculation so that I could see the long term trend.)
Aside from the fact that I don't really like how the company is reporting ACV (which includes bookings from the prior half alongside active customer numbers today) surely such large price increases are not sustainable?
And if free customers aren't converting to paying customers, as seems to be evident from my firs table, then surely revenues will eventually flatline?
At that point it's got to be all about operating leverage, which looks entirely possible given that the Operating Expenditure % continues to decrease.
It's this last point that leaves me undecided.
There certainly seems like there could be an opportunity here even at the current seemingly high valuation and even if revenue growth slows materially.
It's one to ponder, though for now I think I'll leave my valuation hat on and hope for a better entry point in the future.
A
The Nikkei fell 1.6% today after a Bank of Japan board member warned that interest rates would need to be hiked again if inflation met forecasts.
Meaning UK investors should probably expect more volatility going forward (re 'Yen carry trade' 2.0).
So possibly some bargains to mop up from panic sellers before the market quickly recovers again? Excellent!
Can you give your opinion on TRX results yesterday please.
Tissue Regenix (LON:TRX)
Hi Simplicius - I don't think Paul covers small biotech companies, especially that are perennial loss makers - it is an extremely hard sector to get to grips with and there are so many jam tomorrow stocks it would be nigh on impossible to draw any conclusions unless you were an expert in the field and had an inordinate amount of time to research the company.
Its sea of red figures year after year and stock rank would be enough for me to stop looking - without even going into any of the other measures I would look for, before investing.
Tbf Tissue Regenix (LON:TRX) is not a loss-making biotech engaging in clinical trials which defies any kind of numbers-based analysis. It's selling medical devices with a good gross margin and has moved from substantial losses to break even, and well within Paul's remit. However I'm sure he would have appreciated a few comments from OP about why it would be an interesting company to cover
Hi simplicius,
We've got too many other companies reporting today for me to look back in detail at Tissue Regenix (LON:TRX) results yesterday I'm afraid. Also as KevinS1 says, it's not the sort of company we look at, and haven't ever covered it before (loss-making, and outside our area of knowledge).
However, having a very quick look at its results yesterday, it seems to have reached just above breakeven, on growing revenues, so there might be something interesting here. What's your view?
It seems to have enough cash, although is in an overall net debt position, so terms of the debt would need checking, and assessing the risk of another placing. I see the share count has risen about 6x in the last 5 years.
So probably not something I can productively spend time on, but do let us know your views on it (presumably you hold?)
Regards, Paul.