Small Cap Value Report (12 May 2015) - TTG, TPOP, CAMB

Good morning.
TT electronics (LON:TTG)
Share price: 143.5p (up 8% today)
No. shares: 159.0m
Market Cap: £228.2m
I reviewed the issues facing this company here on 4 Nov 2014, when it issued a profit warning. My conclusion then was that, despite the various problems, it could make an interesting turnaround investment at some point.
Trading update - today's update sounds generally quite positive, saying;
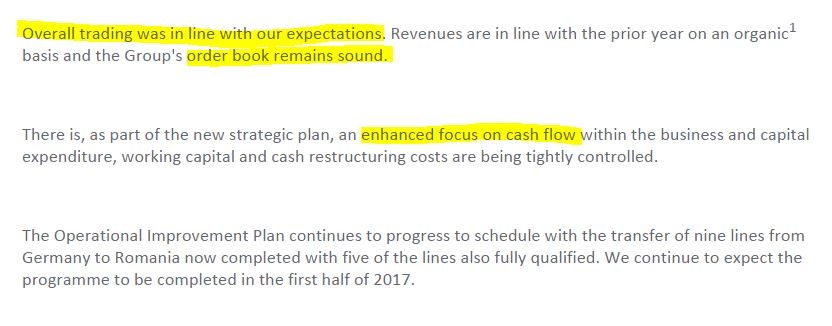
The comments about having an enhanced focus on cashflow are a little worrying - that implies that the cash position might be getting tight? Or that the bank might be pressing them to reduce debt - net debt was £30.7m at end Oct 2014, which doesn't seem alarming, given the size of the company. I did notice that inventories looked high in the last set of accounts, so action to reduce them is a positive.
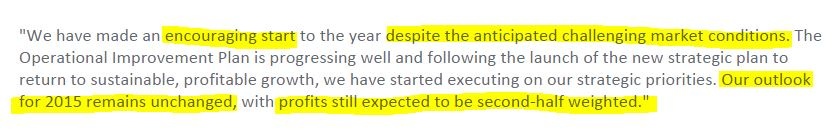
Outlook - the Directorspeak sounds upbeat, but note that it leaves the door ajar to another profit warning, if H2 doesn't improve on H1, as expected;
Valuation - tricky, because the company has been undergoing major restructuring, moving production from Germany to Romania. Note that the broker consensus has been steadily reducing over the last year, although seems to be bottoming out around 10p EPS;
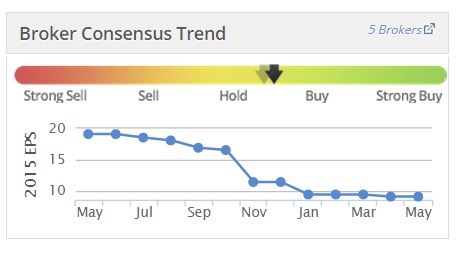
Personally I like to see this chart going in the opposite direction! Although at some point estimates factor in all the bad news, and start rising again, we just don't know when that will be.
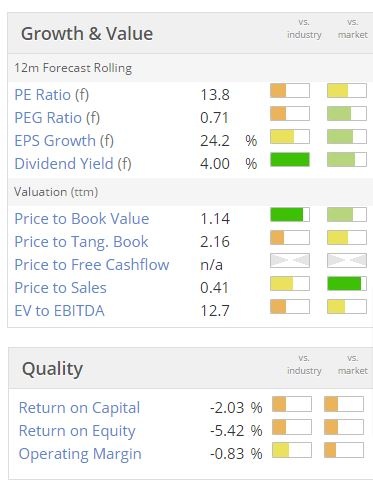
Assuming that broker estimates are correct, or even too cautious, then the valuation looks possibly about right, at the moment, who knows? It's impossible to say with any certainty, as we don't know how the turnaround will play out.
The divis look attractive, if they are sustainable - that's a nice 4.0% yield.
Note there is a large pension fund here, but the deficit is not too bad, but is still a cash drain of over £4m p.a. in deficit recovery payments.
My opinion - the shares have bounced nicely from the profit warning in Nov 2014.
One of the most frequent conversations I have with other investors, is when to sell - especially if there has been a profit warning.
Most people seem to think selling immediately is the best strategy, and they always say that "profit warnings come in threes!", etc. Yet I keep coming across lots of situations, like this one, where actually if you'd held your nerve, even bought more after the despondency of the profit warning (waiting a month or two for all the sellers to be flushed out), then you'd be quids in about six months later.
So I'm firmly of the view that stock market adages work, except for about half the time when they don't work! Maybe I've just created a new adage there!
In this case, I can't see any particular reason to get involved with the shares now that they've already bounced about 50% from the lows - I'd probably be taking some (or all) of my money off the table now, if I'd ridden out the Nov 2014 profit warning.
People's Operator (LON:TPOP)
Share price: 129p
No. shares: 77.1m
Market Cap: £99.5m
Final results - for 2014 are a bit of a joke considering the market cap of nearly £100m, but this company is a start-up, so I suppose it's all about growth. Even so, they have a mountain to climb. Turnover in 2014 was only £432k, and there was an operating loss of £2.3m.
The concept sounds nice, but I'm very sceptical whether it will work commercially. The company operates a virtual mobile phone network, and the idea is that customers can opt for 10% of their bill to go to their favourite charity. Then 25% of the company's profits will also go to charity.
The idea seems to be that social networks will lead to customer altruism encouraging other people to sign up, so very low customer acquisition costs - c.£7 per customer, as stated today.
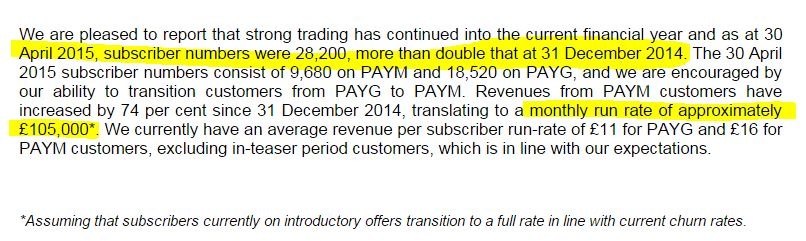
Current trading - I had to chuckle when the company says that "strong trading has continued..." - what are they smoking?! Trading is dismal, but the growth rate is high - doubling subscribers in 4 months is quite impressive;
Balance Sheet - very sensibly, the company raised a big wedge of cash, and had £18.4m in net cash at 31 Dec 2014, so there shouldn't be any worries about cash for some time.
My opinion - based on what the company has achieved so far, the valuation is completely ridiculous in my opinion. How can something that is little more than a start-up be worth £100m? I think the valuation has very much been hyped up on the name of the Chairman, Jimmy Wales of Wikipedia fame.
However, it's a company with an honourable aim, so I hope it succeeds, but personally I think people paying so much up-front for jam tomorrow are bordering on insane.
Cambria Automobiles (LON:CAMB)
Share price: 57p
No. shares: 100.0m
Market Cap: £57.0m
Interim results - for the six months ended 28 Feb 2015 look excellent, as you would expect, since car dealerships are enjoying bumper trading conditions from low interest rates (making finance deals very attractive) and a favourable move in the £:Euro exchange rate, making imported European cars cheaper.
Against this very favourable backdrop, Cambrian seems to have done particularly well, with revenue up 18.6% to £242.8m, and profit before tax up 63.8% to £3.3m - note the very thin profit margin though.
EPS for the half year was up 66% to 2.59p.
Valuation - the full year forecast is for 5.4p this year, and 6.3p next year. That makes the shares look good value at 57p, a PER of 10.6 and 9.0 respectively, although to my mind the shares should be on a lowish PER, given the huge tailwinds that car dealers are currently benefiting from. Other car dealerships are similarly cheap.
Balance sheet - not only is CAMB cheap on a PER basis, but it also has a balance sheet with lots of freehold property, and little debt. There is £13.8m of gross debt, which in itself looks modest, but also at the year end date that was almost completely offset by £13.0m in cash. That may be a favourable snapshot perhaps, on one day, but it's consistent with the last half and full year end dates too.
The P&L has £436k of interest charges in H1, so annualise that and assume an interest rate of about 5%, and this suggests perhaps £17.4m of average borrowings throughout the year. So the half year & year end net debt is probably a bit flattered, but not so much that it's a problem.
All those freeholds should mean this share is copper-bottomed, so I see CAMB as an excellent sleep at night share - this company won't be going bust.
Dividends - small, but growing. The company's stated intention is to use surplus cash to buy more car dealerships, rather than pay big divis - fair enough, everyone knows what they're getting. The interim divi was raised 50%, but it's de minimis at 0.15p per share, so the % gain is largely irrelevant.
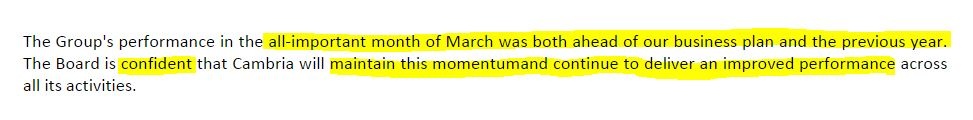
Outlook - sounds like the good times are continuing to roll!
My opinion - there's a good investing case here, in my view - a reasonable valuation, strong balance sheet, and competent, shrewd management (in my opinion). So even though car dealers are enjoying exceptionally favourable conditions, I reckon this company is likely to continue acquiring other sites, often turning around under-performing ones.
Therefore, in my view it's a nice long term GARP share. There were some rumblings about excessive Director remuneration a while back, so that's worth checking out.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
Makes sense to me Paul. I find charts like this one very useful and would love to see them against every stock:
Of course then it would be useful to be able to screen against a trend (rising or falling) in order to filter candidates for further research.
Cheers.
Yes we do plan on adding them... just can't promise when and can't promise it will be at the same price as we're working on a whole StockRanks upgrade bundle. Deeper hierarchy of ranks (cashflow rank, earnings momentum rank, low vol rank etc etc ;-)), histories, charting and more backtesting plus portfolio building tools. I hope we'll be able to let subscribers build their own StockRanks too... will be some time though.
Thanks Ed - looking forward to the new features already! My only concern is that having more than, say, six pieces of information won't improve my investment analysis....
Additionally with regards to Cambria...The H1/H2 underlying eps splits for the last three years whilst sales have been so buoyant are actually very interesting and do show the seasonally strong H2 effect...
2012 H1 0.80p
2012 H2 1.84p (70%)
Full year 2.64p
2013 H1 1.04p
2013 H2 2.53p (71%)
Full year 3.57p
2014 H1 1.56p
2014 H2 2.59p (62%)
Full year 4.15p
2015 H1 2.59p (just reported today)
2015 H2 ???
Full year ???
If we use last years 62% as a base then we can see a second half with 4.25p and a full year total of 6.84p. Now that would be perfectly fine if last year was replicated, however....If they can do the historic average nearer to 70% at 68% then the H2 underlying eps would be 5.51p and give a full year total of 8.1p which would totally smash forecasts for this year and next year!
It looks certain to me that with sales steadily increasing and monthly figures for the whole sector beating like for likes for 40 months on the trot my fairly safe assumption is that the second half will bring us at least 4p and that 6.6p for the full year is a good target....rather interestingly that is 5% better than the 2016 broker forecast. So upgrades are surely on the way.
Vertu Motors (LON:VTU) results out today also show some improvement, adding to the general upturn in the sector. Well spotted sir!
The management at Cambria are in the top quartile IMO and certainly know how to build a very good business in this sector. If a couple of you would like to meet them tomorrow for lunch and a presentation then do email me.
It will be in London at their PR company Tavistock at noon.
David
Hi Paul,
Thanks for the write-up on CAMB. As ever, you make some excellent points about the company - the low dividend is a little frustrating but acceptable whilst the company is able to re-invest and grow faster than the industry average. I think one of the things which is really important with these type of situations is the quality of management, not something you will readily get from the fundamentals - although they are obviously important too.
One of my best ever investments many years ago was European Motor Holdings which had a similar modus operandi to Cambria in buying up underperforming dealerships and sites and using their skill to turn them round. The recent acquisition of a Land Rover dealership in Swindon seemed a particularly smart move in that respect. If the CAMB management are even half as successful as Ann Wilson and Richard Palmer were at EMH, myself and other holders will be very happy bunnies, especially if they sell out at the top of the market as EMH did in 2007 to Inchcape :-)
All the best
Si
Paul
IMHO, CAMB are well ahead of the current broker forecast, to the extent that they could perhaps deliver next year's forecast PBT & EPS in the current year.
Cheers, Martin
Hi Martin,
Interesting, thanks. I didn't look at the seasonal phasing of results with Cambria Automobiles (LON:CAMB) but they do have a track record of out-performance against forecast.
If this link works, it might be of some interest - compares the 5-listed car dealers I found within the speciality retailers sector. Caffyns (LON:CFYN) could be the dark horse - as there are not any forecasts, but it pays nice divis, and has excellent asset backing, plus has unlocked some surplus property value from its freeholds recently. (I hold shares in CFYN). Although some people don't like the controlling family shareholding at CFYN, although I'm coming round to the Stredder/Lord Lee view on this, that as long-term investments, family controlled companies can be some of the best things out there.
Regards, Paul.
Hi Paul
Thank you for sharing your thoughts re CFYN. I had a small holding in them until fairly recently, having bought them not realising the extent of the pension deficit. Unfortunately I sold the shares just before the recent pension commitment rejig and property disposal, the former of which significantly benefited the company at the expense of its shareholders, with the latter also being positive.
Regards, Martin
Hi Paul
With the CAMB interim results having been loaded onto Stockopedia overnight, the V and Q metrics have increased significantly and the StockRating has gone from 77 yesterday to 91 today.
Not quite as high as LOOK which I see issued a TS today, but still quite handy.
I continue to hold CAMB having added a few more on the day of the interims.
Cheers, Martin
Hi Martin,
A very good point! This reinforces my belief that man+machine is the best approach - ie. a shrewd market participant can not only manually screen out the dodgy things like small Chinese AIM stocks, which get past the machine with high scores for a while, and only slip down the rankings once they lose momentum (because human beings have realised that they are not what they appear to be!)
But man can also anticipate forthcoming changes to StockRanks by recognising which companies are likely to out-perform (from interpreting trading statements). So I love it when stocks I already hold rise up the StockRanks, as it helps confirm that my analysis was correct.
Hence why personally I find the StockRanks so useful - it gives me a shortlist of new ideas, and also helps confirm which stocks in my portfolio are more likely to do well, especially when the StockRank gradually rises after I've bought. It's particularly enjoyable when we spot the nuggets of gold before the StockRank has caught up with the positive fundamentals!
Since most stocks are too expensive right now, my main hunting ground is looking for stocks where there is some indication from the company that it's going to out-perform the broker forecasts. Recent examples which are doing well are Avesco (LON:AVS) and Character (LON:CCT) .
E.g the StockRank of AVS went like this;
Oct 59, Nov 64, Dec 77, Jan 85, Feb 75, Mar 88, Apr 86, May 91.
I wonder if Stockopedia could do a StockRank chart for each share, showing how its StockRank has moved over the last year, say, as I would very much like to see that, and home in on shares with rising StockRanks.
Regards, Paul.
"I wonder if Stockopedia could do a StockRank chart for each share, showing how its StockRank has moved over the last year, say, as I would very much like to see that, and home in on shares with rising StockRanks."
This would be awesome wouldn't it Paul? In the same way that a trend of broker forecasts being hiked is a 'good thing' a rising stockrank trend could be indicative of improving fundamentals and a possible re-rating. Definitely an idea worth sharing with Ed.
Hi Damian,
Yes it would be great if the StockReport page could be amended so that there are 2 little charts next to each other - one showing the trend of broker forecasts in last year (as now), with a new chart next to it showing the StockRank change over the last year, for each company.
If Ed doesn't pick up on these comments (he usually does lol!) then I'll message him with the idea.
Regards, Paul.
A significant Director share purchase (£50,000) just announced for Cambria - so I guess there is an internal confidence that the good performance has much further to run
Raigerfield Capital Limited, a family company controlled by Philip Swatman (Chairman) and his wife Rosemary Swatman, has today acquired a total of 85,000 ordinary shares of 10p each in the Group ("Ordinary Shares") at a price of 59.25 pence per Ordinary Share.
Hi Paul, if you get the chance to look at Cambria Autos (CAM) it would be much appreciated. Good looking results today from what I can see.
Thanks
Yes I agree about shares recovering after profit warnings, Asos and Xaar have both gone up over 100% in the last year, there are many others like Pure Wafer and Quindell that have gone up even more. But then there are others that seem to keep on falling, (falling knifes), any tips on picking the time to buy, what do you think about double bottom chart pattern?