Small Cap Value Report (12 Nov 2014) - TRCS, FLYB

Good morning!
Equities First Holdings
This is an American, apparently unregulated, finance company which has been doing deals with UK listed company Directors, to provide "loans" against Director shareholdings in their companies. However, a little digging online shows that EFH's modus operandi is clearly to sell the shares that are transferred to them as collateral, and that the "loan" is non-recourse - i.e. that the borrower can just walk away from it, with no penalty.
Directors at five companies appear to have used this facility - one is Quindell (which I can now mention, as I am no longer short of it, as of this morning), IQE, IGas, CloudBuy, and Angle.
It appears that the loan facilities could be used as a backdoor way of Directors selling shares, in a way which avoided having to disclose that to the market, or so they thought. It could even be used to disguise selling of shares, and make it look as if the Director is buying shares (if some new shares were simultaneously bought with the "loan" proceeds).
The whole thing has unraveled, and three of the five companies concerned have been forced to issue clarification or correction statements. It's possible that some of the Directors involved did not realise the consequences of using this arrangement, but it has reflected badly on all of them.
Shares in Quindell (LON:QPP) have been in freefall, and I expect to see the departure of the founder within days, in similar circumstances to which he was ejected from his previous listed company Innovation (LON:TIG). Good riddance quite frankly. I'm afraid that type always come unstuck eventually.
Shares in Cloudbuy (LON:CBUY) (statement today) and Angle (LON:AGL) (statement today) are also down sharply today. Although in both these cases it looks as if the Directors concerned were probably genuine, in wanting funds for a house purchase, and were probably unaware that the modus operandi of EFH appears to be that they immediately dump the transferred shares in the market.
The FCA, or whoever it is that is supposed to be regulating London markets, needs to issue some immediate instructions on this subject. Although the hot water that the above companies have got themselves into will surely deter other Directors from going down this very unwise route. I would like to see such deals banned altogether. Or at the very least, full details must be immediately disclosed to the market, making it clear that tranferring shares to EFH is actually a disposal of shares by a Director. A non-binding agreement to repurchase the shares in two or three years' time, does not negate the reality that the shares have been transferred to another party, in return for money - which to any rational person would be called a sale.
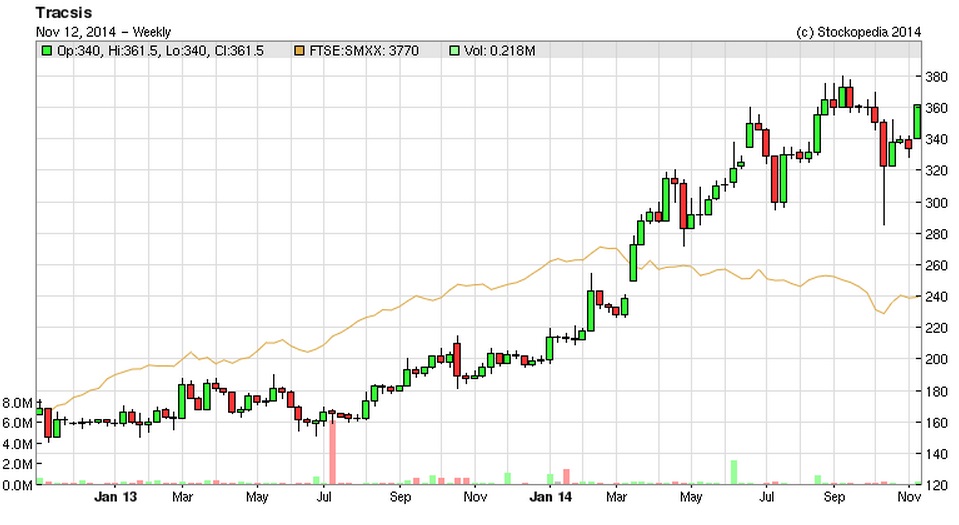
Tracsis (LON:TRCS)
Share price: 364p
No. shares: 26.4m
Market Cap: £96.1m
Please note that I am interviewing John McArthur, CEO of Tracsis, around lunchtime today, and will be publishing the interview as an audiocast on my AudioBoom channel at about 3pm today. I'd like to make the interview interactive with listeners, so if you have any questions, then please submit them before 1pm today in the comments section below this article, and I will ask John on your behalf.
Tracsis is a small group of niche companies serving mainly the rail sector, mainly in the UK, offering products & services like scheduling software, passenger counting, remote monitoring equipment, and consultancy (e.g. for franchise bids).
Final results - for the year ended 31 Jul 2014 are published today, and look very good.
Turnover is up 106% to £22.4m (some due to acquisitions), adjusted EBITDA is up 61% to £5.4m (note the high profit margin), and profit before tax up 62% to £4.2m. Earnings per share was up 53% to 12.9p. Note that the reported 12.9p is the statutory EPS, i.e. with no adjustments. So I presume the 14.9p forecast from WH Ireland must have had some adjustments in it. I'll clarify that with John McArthur in my interview shortly.
Outlook - the US potential sounds interesting, as trials have already been underway for almost a year;
We continue to benefit from transport markets that are experiencing record levels of government spending, steadily rising passenger numbers and regulatory change. This environment provides for good growth opportunities as we look to help solve the transportation problems of tomorrow. In the year ahead we intend to make further in-roads into overseas markets, most notably the US, whilst continuing to diversify our technology portfolio and UK offering through a combination of in-house development and further well placed acquisitions.
Balance Sheet - very strong, with net cash of £8.9m (up from £6.6m), which works out at 34p per share, over 9% of the market cap. So the company has enough fuel in the tank for one or two more acquisitions, which have typically been quite small, but successful.
EBITDA - I'm reassured to see that although the company has some intangible assets on the Balance Sheet, these relate to acquisitions, and it has not capitalised any other costs into intangible assets during the year. Hence EBITDA is a figure that can be taken more seriously here, than at companies which capitalise a load of developments costs during the year.
Valuation - the valuation of this share always look high, but broker forecasts were increased three times last year, so what looked expensive at the start of the year would have ended up looking good value by the end of the year. On the basic EPS of 12.9p the PER comes out at a pretty spicy 28.2. However that includes non-cash amortisation of intangibles, and various other items which you may agree are OK to adjust out, or you may not. Personally I have a problem with share-based payments, as to me that's just remuneration, so I tend to leave that in when calculating EPS to value the company on.
One should really take off the net cash from the share price too, since that cash will at some point be used to buy other businesses. I've not got the latest broker forecasts for this year, so will update this article once I have those.
My opinion - I will reserve judgment until I've interviewed the CEO shortly, but to my mind the share price is aggressively valued on the historic numbers, but that's probably because the company is trading well, and has potentially exciting upside from overseas sales of its remote condition monitoring equipment - especially in the USA where trials are ongoing. Note this comment in today's results;
North American pilot established and since extended. All indications point to a significant long term market opportunity... Our expansion plans within the US are a key driver of growth for this division and whilst the specific timing of technology uptake is difficult to predict, we see a considerable market opportunity that is many times larger than what we have achieved thus far within the UK
Therefore I think one should see the share price as a hybrid of existing earnings, plus an additional amount for anticipating sales taking off in the USA.
UPDATE: My audiocast with John McArthur of Tracsis is now live. Click here to listen, on Audioboom, or here on SoundCloud
Recap after interview- I've not managed to get hold of the revised WH Ireland forecasts yet, but should have them tomorrow. So I'll press on without them. Tracsis today reported 12.9p basic EPS, which is equivalent to about 15p adjusted EPS (which mainly strips out amortisation of intangibles, which is fine, as there is no development spend capitalised).
Therefore if we take the share price of 364p, and take off the 34p per share net cash (which will be put to use in earnings-enhancing acquisitions over time), then the Enterprise Value is 330p/share. With 15p adj EPS just reported, then the historic PER is 22, quite a punchy rating.
However, with the USA trials underway, and the potential there for orders (of the highest margin things Tracsis sells) which the company describes as "many times larger than... the UK"), it could get exciting if the potential in the USA turns into large scale orders.
What might EPS for the current year come in at? It could be anything from 15-25p in my view, depending on the scale of overseas orders. Last year broker forecasts were raised three times, and by a quite substantial amount, so if the same thing happens again this year, then I'll be kicking myself again that I didn't buy because the PER looked a bit too warm at the time, which is exactly what I decided when these shares were 130p, and again at 200p.
Overall I think the shares are probably a little too high for me at the moment, but I could easily regret not buying if & when orders are announced for overseas sales. As always, John McArthur comes over really well in my interview - telling it how it is, very open, and very much the type of management that is backable. Hence the shares deserve a management premium - as he's done 6 acquisitions, and hasn't put a foot wrong. So I remain keen on the company, and am looking for a nice spot to pick up some shares on the next decent pullback.
Flybe (LON:FLYB)
Share price: 112p
No. shares: 223.1m
Market Cap: £249.9m
Interim results - for the six months to 30 Sep 2014 were published this morning, and although I read them straight away, I didn't have time to do a write-up here, due to being so busy with other stuff. So am catching up now in the evening.
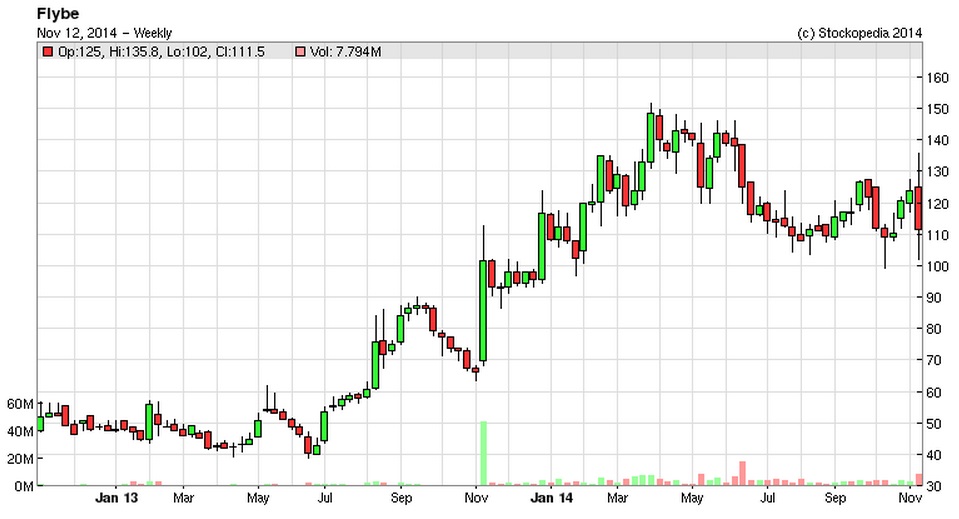
FlyBe is a turnaround situation, and my initial reaction to reading the results today was that they look disappointing. Clearly the market agrees, as the share price has dropped back to the previous support level of 110p, which was the price of the large Placing earlier this year.
However, the headline loss is explained by one-off factors;
Loss after tax of £15.4m compared to profit after tax of £13.6m for the same period last year, impacted by £34.3m of one-offs and revaluations: Finland net impairment (£9.9m), EU261 flight delay catch-up provision (£6.0m), a net movement on surplus capacity and restructuring cost (£10.4m) and movement on revaluations of USD loans (£8.0m)
The Finland JV looked a millstone, so exiting from that is a positive in my opinion - FlyBe's 60% stake is being sold for a token E1 to its JV partner, Finnair. It was loss-making, so that's another problem gone.
Other legacy issues are also being dealt with;
"Our UK business performed well in the first half of the year showing the strength of the new Flybe. We delivered an increased adjusted profit before tax in the Flybe UK business and importantly became cash generative. Though our business transformation is far from complete, we are seeing the benefits of improved commercial execution with the right cost base and we now have improved operational and financial disciplines throughout our organisation.
"We are making significant progress in addressing the legacy issues within the business, which will ensure we operate with a simpler business model. We have taken decisive action in removing the overhang of the outstanding $750m order for 20 unwanted E175 aircraft, withdrawing from the Finland joint venture as well as providing for the potential costs for the arbitrary EU 261 regulation for flight delay claims in Flybe UK. We are working hard to resolve our surplus fleet issue.
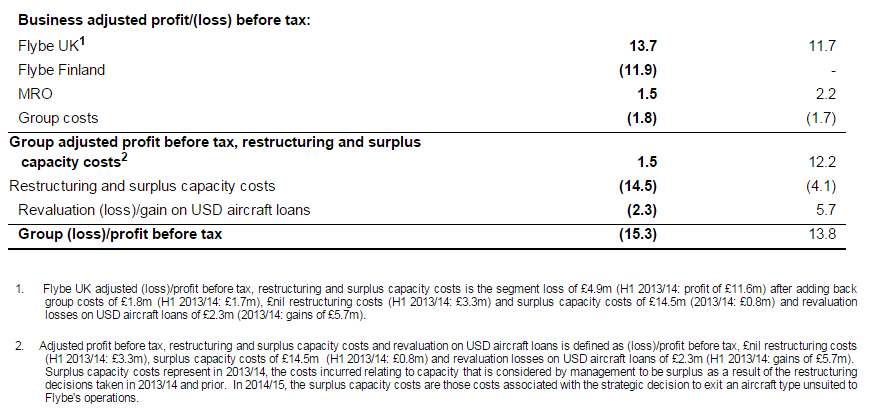
The surplus fleet issue worries me a little, as it's quite a chunky item in the P&L, at £14.5m for the six months.
Although, as you can see from this table from today's results, the ongoing UK business actually showed an improvement in underlying profits from £11.7m to £13.7m;
Balance Sheet - this looks fine to me, with £167.5m net tangible assets. That includes £72.0m of net cash, and I note that 5 aircraft have been purchased outright in the period to reduce costs.
My opinion - I'm moderately disappointed with these figures, and was hoping for more progress in the turnaround. That said, new management have made dramatic progress in turning around what really was a basket case of a business a couple of years ago.
The key issue now is sorting out the surplus planes. Hopefully the new routes from London City Airport will do well - being only 20 mins by DLR from Bank station, this is a far better proposition for business travellers than Gatwick or Heathrow, and should do well in my opinion.
My personal price target on this stock is 200p+, but it might take another 6-12 months to get there perhaps?
Regards, Paul.
(of the companies mentioned today, Paul has a long position in FLYB, and no short position.
A fund management company with which Paul is associated may hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
Just watched the web cast of the Flybe web site (if I was more technically adept I would include a link)
Long but worth a watch. FWIW here are my thoughts
1. Impressive management with a clear vision
2. Business model of an airline providing regional connectivity makes sense
3. UK business growing and clear direction
4. Disposing of the Finnair business made sense
5. Legacy issue of EU261 ruling now provided for and should be less of an issue going forward (as I understand it there is a right to compensation of GBP 250 for any flight delay of more that 3 hours - quite an exposure if you are selling tickets at a third or less of that price - the court ruling means that claims can now be brought going back 6 years and that is now fully provided for going forward there should be less exposure with newer planes etc
6. Disposal of unwanted jet aircraft is the outstanding legacy issues - they are uneconomic for Flybe's routes for which turbo prop is the way to go - 5 out of 14 jets have gone and 9 are still to be sold.
So I am a happy holder
Ah - not so good for us (or maybe it's just me) that do not twitter or facebook or other "social media"
Best,
Laughton
In practice, it's very rare for me to update any SCVRs after about 3pm, but occasionally I get swamped with other things & then catch up in the evening. I like to keep the archive as complete as possible. You can always search for comments on any company by putting its ticker into the search box at the top of the page - that will then list (under the "Discuss" tab) all comments from me & others on that company.
P.
I've recently discovered something that might help: http://www.stockopedia.com/discussion/
By default this shows the most active (recently updated) articles and so if Paul makes a change or somebody adds a comment then the article will be towards the top of the list. Also if there are unread comments then you can just click on the link and jump to the first new comment.
This is a great feature and it's also useful for seeing which older articles are still attracting interest. I don't even bother to go to the homepage any more.
Damian
Hi Paul,
Just come across your thoughts on Flybe - but only because I received a link from elsewhere. I usually read your post when I get the email notification and then refresh the page a few times through the day to read the comments section. But the Flybe write up was obviously done late in the day so easily missed - and then the next day comes along.
Isn't there some way of letting regulars know if you've covered a share very late in the day - either by a second email notification or a note on the next day's Report or something similar?
Best,
Laughton
I usually Tweet out if I've updated a SCVR late.
P.
Re EFH. Interesting legal arrangement. If the stock is, or has been, sold by EFH then on the face of it they are short and are using the company director as a 'lender.' Is it really the case that neither the loan, nor the stock may be returned at the choice of the respective owners of the stock or money? That means the clause covering repayment is totally meaningless and the transaction is a sell by director and purchase by EFH. If it was otherwise the owner has a call option, which in a stock like QPP over 2 years would be way too expensive to make sense.
I dare say that if the rules were changed to force disclosure of the sale, alternative schemes would be dreamed up to achieve much the same objective, allowing the directors trade their stock ahead of the public, ideally secretly. One of the best things about this website, and other more aggressive publications, it the ability to inform the public and let them form their own opinion. Personally I was surprised to see IQE among the companies doing this.
A non-binding agreement to repurchase the shares in two or three years' time, does not negate the reality that the shares have been transferred to another party, in return for money - which to any rational person would be called a sale
From an accounting perspective the question is have the risks and rewards of ownership transferred?
It's not completely clear to me in that the borrower must make a margin call if the share falls below a certain level.
However, in cloudbuy's statement today it notes :
http://www.investegate.co.uk/cloudbuy-plc--cbuy-/r...
The Agreement contains a margin call, if the value of the shares falls below 19.5p Mr Duncan may either terminate with no further liability or provide additional security in cash or shares.
So in other words, the director can terminate the agreement if the shares fall below a certain level and at that point the risks and rewards of ownership are fully passed over hence it's safe IMHO to call it a sale.
Hi Paul
Re TRCS. I have just finished listening to the audiocast, and John McArthur the CEO comes across as a very credible and 'backable' leader. Prospects for the next FY look really good and I'll be investing.
Regards
Excellent discussion on EFH.
I would certainly agree that it is a purely a device for Directors of questionable companies to walk away with some cash. As a someone said - deal with EFH and you are raising the white flag to shorters.
In truth this is just a another symptom of the totally dysfunctional AIM market. Paul makes a fine attempt to create a bargepole list, but it would be much easier to start the other way round and try to list the decent companies on AIM.
Hi Paul,
I've followed the whole Equity First saga with interest, and ignoring the underlying reasons of why Quindell, Cloudbuy etc are using this facility, I'm still a bit puzzled by Equity First's 'business model'.
You mention their "modus operandi is clearly to sell the shares that are transferred to them as collateral". I agree.
What I don't understand from their perspective is, say they sell the shares and pocket some cash, but then 2 or 3 years down the line the loan is paid back and the Director/CEO wants their shares back, what are they going to do if the share price has increased? Say Cloudbuy (LON:CBUY) has a unique IP that massively takes off and the shares 10 bag over the couple of years. How on earth are they going to afford to buy the shares back at multiples of what they've made on the loan in terms of initial discount plus the 4 or 5% interest rate?
Surely the potential risk involved of loaning against shares in companies that could go up automatically adjusts their selection criteria to avoid "good" companies, and only loan against shares in companies where there is a high degree of certainty that the related share price will be significantly less by the end of the term?
Furthermore, it's in their INTERESTS to do whatever they can to bring the Share Price down e.g. through selling the collateral shares, since
1) If they tank the Share Price, they can buy the shares back at a significant reduction (if it ever really came to that), and
2) If they tank the share price below 80% of the value at the time of the loan, they can make a margin call for even more collateral.
Whatever way I look at it, I cannot see how any of this is in the interests of investors?
THE SELLER / DIRECTOR / CEO - Gets instant cash for shares whilst masking the fact they are reducing their holding and are therefore not seen to be directly influencing a share price decline like a direct sale into the market would.
EQUITY FIRST - Make money in the difference between the discounted loan arrangement through selling the shares, receive interest on the loan, and potential to make more money if they can bring the share price down to get a margin call. Not interested in loaning against "good" companies whose Share Price might be higher at the end of the term.
INVESTORS - Value of investment goes down as shares are dumped into the market and investment case for PI's buying into the stock lowered through being tainted by the fact the stock has passed Equity First's selection criteria of a stock not expected to increase over the next few years.
So can we assume therefore that the interests of Equity First are in direct contrast to the interests of the PI's, and as such, the Directors who are doing these deals are also effectively operating in contrast to the interests of their own shareholders through doing these types of deal?
Hi JPshares,
I agree with your comments. I believe that, in the majority of cases, Equities First will realise that their offering will attract Directors of companies where it is very unlikely that the share price will be higher in 2-3 years' time. So it's really an exit route for Directors of dubious companies.
EFH has been sued by people who have tried to redeem their stock, only to discover that EFH has sold it - you can find such legal cases easily on Google. So it's very far from a reputable organisation. Who in their right mind would sign away their physical shares to some unregulated outfit in America? Either the desperate, or the naive, I would suggest.
The problem is that TW has blown the lid off the whole thing, and forced 5 companies to put out correction statements, and put a rocket under the relevant NOMADs too, and if ThisIsMoney is to be believed, has got the FSA on the case too.
People may not like his style, but he's actually doing the PI community a huge service by shining a light on the murkier depths of AIM. More power to him I say. It sickens me the way longs in certain stocks try to shoot the messenger, whilst blithely ignoring obvious wrongdoing at companies which they hold, simply because they are blinded by their own financial self-interest.
Just look at the shares on my Bargepole List - it's not even been going 4 months, but has already correctly identified lots of disastrous shares, with few false negatives too. So heeding red flags is incredibly important. It utterly mystifies me why so many PIs seem to want to be ripped off, blindly ignoring all the warnings from experienced investors.
Anyway, despite all the abuse I've had thrown at me elsewhere, I'll very much carry on doing what I'm doing, as it saves people who listen potentially a lot of money.
Regards, Paul.
Cheers for the reply Paul, I think you're absolutely spot on.
Please keep up the good work and stick to your guns even if exposing the truth is not what people want to hear. I lost a lot of money in my early investments purely because I buried my head in the sand and didn't want to accept that I had made a mistake. I'm sure others will realise in due course that the work you do is in all investors best interests, even if it is (and often it REALLY is!!) a bitter pill to swallow at the time.
Hi Paul, I find it bizarre you are allowed to talk about Quindell (LON:QPP) now you are long but couldn't when you were short? I fail to see the distinction, surely they are just two sides of the same coin?
Hi Webpax,
That's just Stockopedia's editorial policy, which I have to comply with.
The bottom line is that some subscribers to this website get upset by writers with a short position talking down stocks that subscribers hold, so they then put pressure on this website to stop giving airtime to shorters.
So it makes for a quieter life for everyone if writers here just don't talk about shares where they hold short positions.
I'm fine with that, as I can just put my remarks elsewhere & also it keeps all the unpleasantness off the nice tidy & civilised discussion boards here.
But yes, you're right, it is totally illogical!!
Regards, Paul.
Thanks for the explanation Paul.
I'd be interested in you thoughts on the Flybe (LON:FLYB) results if you get the chance.
"That's just Stockopedia's editorial policy, which I have to comply with"
Seriously poor judgement from Stockopedia in putting subscriptions from low grade members before transparency and open discussion. I recognise that such discussion perhaps requires more moderation to keep it civil, but the answer is not censorship of a particular class of valid views, and inhibiting the exposure of poor investments and wrong-doing.
Hi Brian,
In fairness, the editorial rule only applies to me, and other Stockopedia writers such as Ben & Alex.
All Stockopedia members can of course discuss anything they like, and are not censored at all.
So other people with shorts on stocks can talk about them here.
I'm fine with the editorial policy here. In the past when I got over-excited & broke the rule, it dragged the discussion into the gutter, as it attracted a whole load of nutters from advfn over here. Quite frankly, I'd rather they stayed put on advfn & hurled abuse at each other there!!!
Regards, Paul.
Hi Paul,
The interview with the Tracsis (LON:TRCS) CEO keeps crashing :(
Regards,
Sully.
Hi Sully,
Sorry about that. The audio hosting is out of my hands unfortunately. AudioBoom & SoundCloud host it. If one link is proving troublesome (pls let me know which), then try the other (below);
https://audioboom.com/boos/2643867-john-mcarthur-ceo-tracsis-trcs-interview-with-paul-scott-12-nov-2014
https://soundcloud.com/paul-scott-uk/john-mcarthur-tracsis-interview-12-nov-2014
Regards, Paul.
Hi Paul,
Thanks, I'll try those later. It was the link from Stockopedia that kept breaking up. I'll let you know if I get any issues with the other links
Regards,
Sully.
Sully.
Paul,
Now you have sat with John Mcarthur, any more thoughts about Tracsis' valuation? You said you would update the article as well after broker updates.
I am long on Tracsis.
guys, it is true that Paul has been right about Quindell's share price movement and it is true that he has explained why very clearly. Before I say this I should declare I don't own any of the shares but I have looked at them several times and I am still not convinced it is quite the sham that is now being claimed. Accepting the cash issues I cannot help believing that in line with the comments about a more serious management team the model may have some success. Given they have some fairly impressive clients who are using the services perhaps there may be a white knight step in. I am with Paul but cannot quite bring myself to do it (I am not as flush!) but I think you may find there is upside from here.
Paul
thanks for your reply, you short did well due mainly I think due to TW blogs along with co-ordinated action by bloggers and press sowing the seeds of doubt.
Time will tell if the company is making money or not, which I personally believe it is.
If it does do you think TW would apologise for the huge losses investors have suffered and the negative effects this has had on all aim shares, which I am sure he is soley responsible for.
,
Magic
the short was ultimately helped by the directors selling, at a much lower price than the price when they were telling us it was cheap. And not long before the long awaited positive cash flows get announced. Or not.
magic,
Shorters can inflict short term damage on a share price, but it quickly recovers.
The reason the price of Quindell (LON:QPP) has not recovered, in fact is about 90% down, is because what the shorters & bloggers have been saying has turned out to be TRUE.
Anyway, I've been long QPP since this morning, as a bear squeeze is also a good money making opportunity.
If you can't stand the heat & all that.
Funnily enough, well managed companies with decent management, transparent accounts & real cashflows don't ever have problems like this. You should have a think about why that is perhaps
Anyway, I'm really not interested in discussing it any further. If you haven't learned the right lessons from this yet, then there's probably no hope of that ever happening.
PP.
Hi Paul,
regarding Quindell (LON:QPP) I hope you had some good success with this. Anyone taking risk and getting it right deserves the reward regardless of whether they are short or long.
The purpose of the market is too correctly price assets not to make people rich. Those thinking that the price is too low or too high have their roles to play in achieving this. Those who are right are rewarded and those who are wrong are punished.
Anyway sorry to ramble ...Any thoughts on Flybe (LON:FLYB) I just bought in as the fall today seem to be due to temporary one off factors. Also the sale of the Finland JV looks positive for profit. .
Cheers
John
P.S what was the name of the app you use for your RNS alerts?
Don't have position in QPP but any share that generates so much ramping / comment on BBs is best well avoided, especially those associated with, shall we say, dubious CEOs with history.
There's no smoke without fire, and personally I prefer to invest in businesses I can understand and that don't have the crazy BB following (Bulls and bears).
It's been entertaining watching from the sidelines though. Tom W may be outspoken - but given the level of corruption / insider dealing / general ethos of shafting shareholders employed by many listed companies I think this is a positive.
I was immediately put off QPP way back by this description of their business on their website:
In today’s digital world the pressures on an organisation can come simultaneously from multiple directions including the need to add customers, increase wallet share, reduce costs and improve customer satisfaction. At Quindell we have the People, the Processes and the Supply Chains, underpinned by our sophisticated Champion and Challenger Business Process Management Technology Platform and Industry Solutions to help our customers tackle these efficiently and effectively.....
How could anyone invest in a business described in that manner?
I would pay big bucks to get Tom Winnifrith and the Quindell (LON:QPP) management in the same room. Perhaps Mello 2015?! although I doubt that Quindell (LON:QPP) will be around that long.
Nearly two years ago there was a very simple sign that things would turn out very badly for shareholders at QPP - a CEO tweeting about the share price.
Hi Paul, any thoughts on Flybe's latest update? 16.5% drop seems harsh and a bit short-sighted IMO.
Keep up the good work
Cheers, James
I am not entirely convinced of the Quindell business model to be honest.
They claiim to be able to reduce costs for Insurance companies whilst increasing profits from Quindell's various companies - which make (and have made) their money from the same Insurance companies.
Quindell have shrouded their business plan in wordy and obtuse statements so that this basic conflict in logic has got a bit lost. This was probably the first indication for me that Quindell might not be exactly what it seems.
@Magic,
I thought Paul said some time ago that he was short QPP? well before TW's comments.
Paul
as you have now admitted you have had a short on Quindell and have been in contact with TW on this for time.
Have you in fact been part of a organised market attack on Quindell that one might call market abuse ?
I cannot understand either how you can call a loan agreement (clearly the document says this) as a sale, this seems to me to be twisting the truth to suit your own and TW's agenda.
Can you explain please !
"as you have now admitted..."
I've plastered the fact that I've been short QPP all over the internet for a long time. If you missed it, then you must have been half-asleep!
"Have you in fact been part of a organised market attack on Quindell that one might call market abuse ?"
If I think a share is no good, then I short it. Other people can read the figures too, and for the same reasons may also go short. That's up to them. I could just as well ask you - Have you been part of an organised group who went long of QPP?! The appalling ramping of QPP shares all over the internet has been market abuse, if you want to go down that route. Everything the bears have said about the company has turned out to be true!
You might also like to consider this fact - the shorts got it right. The longs got it wrong.
I was right all along. QPP shares have dropped about 90% from the peak, and I warned my readers about it here 18 times in 2013, before the bulls silenced me on here. I'm very proud of that, and am sure that I saved my readers money by repeatedly warning them about the dangers at QPP.
I think there might be a short squeeze, so have today closed & gone long. But you see I have integrity - so if I think a company is rubbish, I will say so, even if I'm long. I am now long of QPP, and I still think the company is rubbish, and I can't wait to exit the position asap, but there's money to be made from a bounce in my opinion.
Anyway, let's move this discussion over to advfn, I don't want bickering about QPP cluttering up a civilised board here.
PP.
Hi magic
Whatever you may be alluding to here Paul has been consistent in his declaration that he had been shorting Quindell. There can be very few readers who would have been surprised by his "revellation" this morning
Re Tracsis. Would be useful to know how the CEO compares Tracsis offerings with those of Trapeze Group in North America and Atos' rail division in the UK and Europe. Of interest wd be the number of times they have tendered for contracts against them and their success rate.
Appreciate this is an open-ended question but finding out how a CEO acknowledges competition can sometimes be quite revealing.
Hi Paul
Interesting story about Equities First Holdings. My understanding of collateral is that title isn't transferred to the lender — or at least, not unencumbered title. So I don't quite get how EFH can sell shares that have been given to them as collateral. Unless they have had full ownership transferred. And if a director transfers full ownership in return for a "loan"…!!!! And these directors are running public companies??!??
If EFH didn't have full title, they would take the risk the director just runs with the money and keeps their shares, so they need something more or less equivalent to full title, give or take a few minor restrictions like not voting them if they keep them on their own account.
Still the director has a call option to buy them back (should EFH not default), so they've got some residual interest, hence why it doesn't show up as a sale in the regulatory shares count the director has an economic interest in -- although the real economic interest is much diminished because of the optionality protecting the downside.
Hi Paul -
RE. QPP. The tragedy to me about Quindell is not seeing it disappear down a plug hole. I genuinely believe that Quindell's business model of providing an integrated set of outsourced services to the insurance industry is sound and crying out for someone to do it profitably. I am convinced that a new company with a new breed of professional managers will come along in a few years time and do what Quindell should have been - a large successful, profitable insurance focussed outsourcer. This lot had the opportunity but by sheer stupidity and incompetence they let the prize slip out of their hands.
Regards, Ram
Hi Paul,
As an investor who mainly buys and generally holds a share/ETF/Fund can I ask a question about shorting shares bearing in mind your recently exited position in Quindell. I assume as an individual as opposed to institutional investor you would use CFDs to short a stock like Quindell. I have recently downloaded the Plus 500 CFD Demo software and there seems to be a fairly limited universe of stocks that can be shorted. Are there other 'reputable' platforms that provide CFDs on AIM stocks and if so who are they?
Any retail investor can short using CFDs or Spread Betting platforms. I personally use IG which has a larger choice of small/AIM shares whilst others boast tighter spreads.
Hi Paul
In terms of your comments re QPP and other companies, which have made use of the services provided by Equities First Holdings, is it fair to say the associated NOMADs have not exactly covered themselves in glory either?
AIUI, they effectively have sign-off on RNSes issued by companies for which they are NOMAD and often request changes if they feel a proposed RNS mis-represents reality. This seems to have been sorely lacking in these cases.
All IMHO, DYOR.
Regards, Martin