Small Cap Value Report (12 Sep 2016) - RST, BRY, GAH, SSTY, CTG

Good morning!
Groan, it's one of those days where the RNS only lists results & trading updates from companies which I find of no interest to me whatsoever. So I can't cherry-pick the interesting ones, as there aren't any.
We seem to be having something of a correction at the moment. Not before time, as the post-Brexit boom really has been remarkable, and maybe got a bit excessive perhaps?
Whenever the market goes wobbly, I have a standard procedure now - I chuck out some of my low conviction positions (especially if they've risen a lot, and look fully priced). Then I also open up some short positions on over-valued US large caps, and/or indices. That tends to act as a good shock absorber for any downturn in the rest of my portfolio.
Then when the sell-off seems to have run out of steam, I buy back the shorts, and that usually provides a little pot of extra money to grab some bargains on the long side, at or near the lows. Obviously that's all a lot easier said than done. However, it's worked for me a few times now, and as my guru says to me - "Just do more of whatever works". Some of the best advice is the simplest.
ShareSoc Brighton evening
Is tomorrow! I'm very much looking forward to this, which we're hoping to make into a monthly event. It's ShareSoc's event, but I'm just an enthusiastic helper! There are a few places left, so if you fancy coming along for what should be a fun evening, here is the booking form.
The company presenting is Palace Capital (LON:PCA) . Also, I'll be giving a 30 minute presentation on my best small cap stock ideas from the last month's reports, and which shares I've been buying/selling personally. If people like this slot, then it may become a regular monthly thing.
Of course one of the best things about these events is that we also have the whole evening to chat to each other about shares we think look interesting. So there's always a lively & friendly discussion until closing time. Everyone has a shared interest, so conversation flows easily right from the start - so nobody should ever feel intimidated or shy about coming along to investor events.
Restore (LON:RST)
Share price: 356.6p (up 0.6% today)
No. shares: 112.1m
Market cap: £399.7m
Interim results, 6m to 30 Jun 2016 - the adjusted figures look very good;
Revenue (£m) | 55.4 | 43.9 | +26 |
EBITDA (£m)* | 12.3 | 9.0 | +37 |
Operating profit (£m)* | 10.5 | 7.7 | +36 |
Profit before tax (£m) * | 9.6 | 7.1 | +35 |
EPS (p) ** | 7.9 | 6.8 | +16 |
Dividend per share (p) | 1.33 | 1.00 | +33 |
Net debt (£m) | 29.3 | 30.4 |
However, I note that there's a yawning gap between adjusted EPS of 7.9p for H1, and statutory EPS of 3.8p, both are for continuing operations only. So it's worth looking into what the adjustments actually are - are they reasonable or not?
There's a reconciliation in note 4 to the interim accounts today, where you can see that it's exceptional items that are doing the heavy lifting to get adjusted profit up. That worries me a bit. Personally, I like nice clean profits that don't need any adjusting.
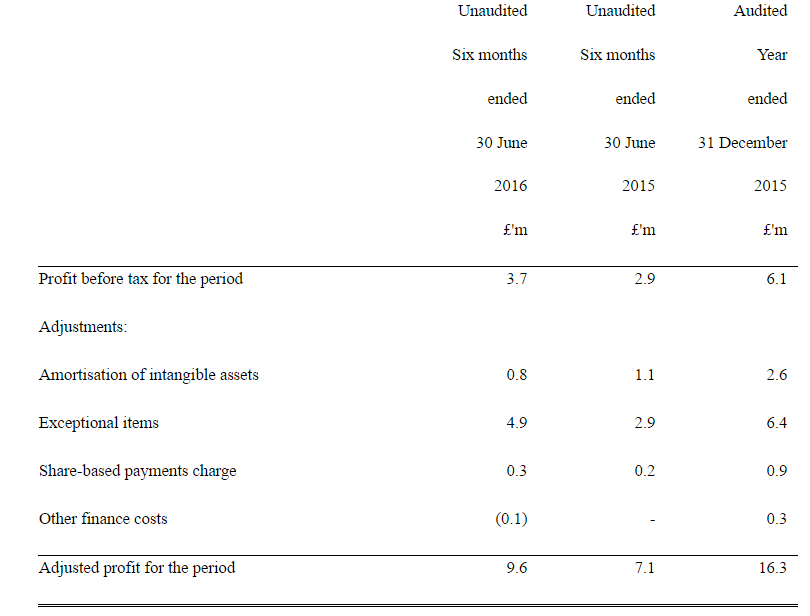
Cash generation is also nothing to write home about here, indeed looks quite meagre for a £400m mkt cap group. That is reflected in small dividends.
Outlook - sounds solid, and in line with expectations;
The second half of the year has started well and we remain confident of making progress in the remainder of 2016 to deliver a full year performance in line with current market expectations.
Balance sheet - not great. As growth has been primarily driven by a series of acquisitions, it's the usual story of intangibles becoming an ever greater mountain at the top of the balance sheet. Strip those away, and NAV of £113.5m drops down to NTAV of minus £4.2m.
That's not necessarily a problem though, for a profitable business. Although it is important to note that there's nothing in the way of net tangible asset backing.
Net debt of £29.3m seems fairly reasonable. It makes sense for profitable businesses, with reliable income streams to use a bit of debt when it's so cheap. The trick is not becoming over-reliant on debt.
Share issuance - it's worth nothing that the average share count rises every year with this company, and has gone up from 27m in 2010 to just over 4 times that amount today. Sure, the group is now much bigger, as it's been buying up other companies. Personally I prefer companies which can grow without issuing new shares and taking on excessive debt.
Further acquisitions - note that a substantial acquisition was made post period end;
On 26 August 2016, the Company acquired PHS Data Solutions, which is the second largest provider of document shredding services in the UK, as well as having a significant records management business and a presence in document scanning, for a total consideration of £83.2m.
My opinion - this has been a fantastic investment since 2010, being a serious multibagger. However, that doesn't necessarily mean it will be a good investment in future, from today, which is all that interests me.
My main concern with this group is that there's a finite life to its main activites - document storage & shredding will probably be largely defunct in say 20 years, if not earlier. Everything will be digital by then. Sure, Restore can make money on the way, and can digitise content for its customers, etc, but what happens after that, when document storage is no longer needed?
To my mind, the current valuation of a PER of about 19 looks very warm for a business which is in this space. Also, there's no net asset backing, the divis are poor, and cashflow doesn't look great.
So for those reasons, whilst acknowledging what a terrific investment it has been to date, I wouldn't be interested in getting involved now.
Brady (LON:BRY)
Share price: 66.25p (down 2.6% today)
No. shares: 83.0m
Market cap: £55.0m
Interim results, 6m to 30 Jun 2016 - I'm scratching my head to understand why this company is valued at £55m? That seems a very warm valuation, given that it performed badly in 2015, and is now only moving into very modest profitability due to cost cutting. Plus its long-standing CEO recently decided to move on, suggesting to me that there's not a particularly exciting future ahead for the company - if there is, then people tend to stick around. That's assuming he wasn't pushed of course.
As we saw last year, revenues are fairly predictable, due to more than half being recurring in nature. However, the problem is that profit is unpredictable, because it relies so heavily on Q4 licence wins. So the company itself really has no idea what profit it's going to make from one year to another.
How on earth can investors value it then? Broker forecasts are just guesswork.
The cash position looks fine, and if Brady win some good contracts, then profit may recover. However, for me the present market cap looks wildly optimistic, so it's of no interest to me. Why pay up-front for future success which may not happen? That just strikes me as poor risk:reward.
Gable Holdings Inc (LON:GAH)
Suspension & delisting - Zeus has resigned as its NOMAD, so shares are then suspended, with one month to find a new NOMAD.
In a separate announcement, the company says it needs to cut costs to survive. It's a general tale of woe. So they won't be seeking another NOMAD, but will just be de-listing.
The writing has been on the wall here for a while. I warned readers away from this share, in the strongest terms I dared, here on 21 Dec 2015. A broker friend had strenuously warned me not to go near it, describing it simply as "a wrong 'un". The figures, and related party transactions stank too.
So there we go, that's the end of that one. I doubt very much that shareholders will see any return now, so best just write it off & put it down to experience, and of course never touch any company in future run by the same Directors.
Safestay (LON:SSTY) - as mentioned before, I like the concept here, but the figures just aren't working. Today's interim results show only an operating profit of only £191k, from fixed assets valued at £46m. That seems an extremely poor return on assets.
Moreover, the operating profit is nowhere near enough to cover the interest bill - finance costs are £789k for the half year.
Despite the upbeat commentary, I feel that this posh hostels provider is a long way from having demonstrated a viable business model yet. The aggressive property valuations make the balance sheet look OK, but I wonder how the book values would compare to an actual free market disposal price?
It clearly needs to grow more, which means more dilution for existing holders. Everyone knows that, so I can't see the shares gaining any traction for long, as rises will probably just be snuffed out by another discounted placing.
Running hostels strikes me best viewed as a lifestyle business for an owner/manager, run on a shoestring. It's difficult to see SafeStay getting very far with their business model. The sites don't generate enough profit to fund a central overhead, finances costs, let alone dividends to shareholders, in my view.
Christie (LON:CTG) - poor interim results from this services group. I can't see any appeal in this company at all. Although the shares have come down quite a lot, as they should have done.
The outlook for H2 is better though. Note that there's a hefty pension deficit on the balance sheet.
I'm losing the will to live here, so think I'll just sign off for the day now, and hope there are some more interesting companies reporting tomorrow.
Hope to see some of you in Brighton tomorrow evening!
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

25 comments
So not in the nick then. I will certainly avoid luminaprime!
In reply to Samsgrandad,post 20
I believe C.Dif and MRSA are as much a problem in Australian hospitals as they are in the UK. Tristel will, no doubt, want to become 'de facto' supplier there too.
Disclosure: I hold shares in TSTL.
Titon Holdings (LON:TON) I've seen it written that they manufacture MVHR exclusively in South Korea which offers(ed) a cost advantage in the UK. If so, I assume that will now be reversed.
It will take more thinking for me to have a view overall one way or the other.
I've looked at Titon Holdings (LON:TON) several times before, and didn't like it. Can't remember why, but there was something wrong with it.
Regards, Paul.
Restore
Interesting that both last year and this year , the "exceptionals" exceeded the adjusted profits. No wonder the cash flow is a bit thin.
I always wonder how regular charges like this can be called "exceptional". for several years
Not for me
Hi Paul,
Next time there is a slow day for RNS test interest you, perhaps you could take a look at Joules (LON:JOUL) . There were a couple of plees to get your verdict on them last week while you were on holiday so you may not have seen them. Given its your specialist area of clothing retailers I and several others would welcome your thoughts.
Cheers
I was interested to see that Tristel has received Regulatory Approval for it's Fuse for Surfaces and Jet for Surfaces disinfectant in Australia. Sales reached £1.2m for these two products in the UK last year and Tristel now has it's own wholly owned subsidiary in Australia which should enable the Company to take advantage of this new Approval.
I believe Tristel are also seeking approval for it's range of products in the States and, while still some way to go, I believe that this will provide significant further growth for the company when this is achieved.
Disclosure: I hold shares in TSTL.
I was unsure before I invested that Tristel had a unique product that they could protect from competition. They have, I found, patented methods of packaging the two chemicals which produce chlorine dioxide, in a manner which enables on demand mixing for all manner of cleaning and disinfection. They have, from what I could find on the net, become the de facto supplier of disinfectant for the control of C.Dif and MRSA in UK hospitals. I have posted my research on the TSTL thread on ADVFN.
One would love to know the identity of a mentor's mentor! You have certainly become a valued though non-exclusive mentor to yours truly.
Thank you for all your valued and direct eveluations.
Paul, regarding Gable you say "and of course never touch any company in future run by the same Directors". The problem here is that 10 years down the line we will have forgotten all about Gable and who the directors were. What we really need is a sort of database of duff directors and companies that they (used to?) control to help research possible investments. In doing due diligence I usually look at Companies House website to see what other companies the directors have been involved with, but that does not really go far enough. I do have a little database of my own duff directors, and if my attention is initially drawn to a company where a director is on my list that would be an automatic red flag. But I would rather spend my limited time investigating companies I want to invest in than ones to avoid. Something collective here would be helpful, but probably run into all sorts of problems. Just my thoughts!
I've just made a long overdue move to start my own blacklist of directors, so thanks for the prompt for that. About 30 years late. If there are any pre-existing sources of data, perhaps that's a better starting point.
Charlie Munger keeps advocating "inverting". e.g. Figure out how people lose money and avoid that.
Top of my list would be Sean 'Baldy' Nutley out of Silverdell .If he is not in prison he should be.
I did not own shares -thank the Lord-but had reasons to follow the story.
Seemingly flourishing http://www.luminaprime8.co.uk/sean-nutley/
Re: GAH I'm not surprised what has happened to this Company and as you say Paul the writing has been on the wall for a while. I was a shareholder a long time ago, but sold out long before the present troubles.
I came across them latterly in a professional capacity where they were insuring a construction risk. It was high margin risk stuff and the premium matched it. I experienced the worst ever service from an insurance company when seeking an assignment of the policy. You can tell a lot from a business in terms of the business that it does and the customer experience.
Any thought on Real Good Food, Paul? Interesting research note published by Hardman & Co released today. Seems like it could be a turnaround stock following the sale of its sugar business, Napier Brown.
Hi Paul, long time reader who thoroughly enjoys your reports. I recently came across a share you have yet to cover and wondered if you would look at it, it came to my attention via John Lee. Titon Holdings. http://www.titonholdings.com/media/download/news/Interim-Statement-March-2016.pdf These are half year results from May. Maybe a bit small and boring but thought it point it out for a future report?
Titon Holdings (LON:TON) keep cropping up on my value screen, but they look pretty much valued right to me. They make fixings and accoutrements for windows and vent sysytems. The Korean side of the company has seen a slowdown, and their future in the UK seems tied to the uncertain housing market. The US side may now be impacted by rate rises. They have cash though, and the continued weakness of sterling should also help. Hardman give an EPS forecast of 13p and DPS of 3. So plenty to be happy about, if you trust the housing market. Perhaps one to buy on the dips (when they come)?
I sold a modest holding a month ago because I couldn't see a catalyst for a rerating, in so doing I crashed the price 10% or so on the day so it is horribly illiquid. Thankfully what I bought went on to perform as I'd hoped but be aware that the painful spread on the stock is exacerbated if you want to deal in more than a hatful and in less than week or so!
Titon Holdings (LON:TON) is shooting up now. John Lee bought back in, and said in last weeks FT Money "on a recovery trend, backed by hard assets, cash rich, well covered growing dividend".
Very hard to trade though. I managed to get 2000 today at 130p.
It's not a sector that Paul covers, but this morning's interims from Central Asia Metals (LON:CAML) look very good.
http://www.investegate.co.uk/central-asia-metals--caml-/rns/half-year-report/201609120700074637J/
Revenue, EBITDA and profit before tax all up despite falling copper price. Interim dividend up from 4.5p to 5.5p.
Steve
Disclosure: I hold shames in CAML.
Hi Steve,
Disclosure: I hold shames in CAML.
There's really no need to feel ashamed for holding a resources stock ;-)
PP.
I always suspect that the risk with Central Asia Metals (LON:CAML) is political. They operate almost solely in Kazahkstan and acquired the second half of the asset by getting a local businessman to buy it from the government and sell it on to them (he got a seat on the board an lots of money).
The financials always look fantastic but it worries me that a new government might not look so favourably on these transactions.
"- document storage & shredding will probably be largely defunct in say 20 years"
I remember reading that 20 years ago
... however I see the land registry is now largely electronic and so it may be the time has come.
Hi Andrew,
Yes, I'm also surprised that paper records have lasted this long. I recall back in my Pilot days, c.2001, my management accountant persuaded me that we didn't need to produce any more paper audit trails from our accounting system. At a few clicks of a button, he just copied the files onto a hard disc. which was then backed up. In practice, we hardly ever referred back to the digital files anyway.
We had a room full of historic paper records, which eventually just got burned in the yard by our oddjob man.
Interestingly though, I think the move to digital may now be accelerating. I see the Govt has some policy along the lines of digital by default - i.e. every new project now has to be managed online, unless there is some specific reason why there have to be paper records.
It's great, I think. Members of the public can now do so many things online that used to involve a time-consuming visit to the local council office, e.g. paying council tax, parking permits, etc.
Regrds, Paul.
Who's your mentor Paul out of interest ? also any idea yet on on a release date for your book ?
Cheers
Andy