Small Cap Value Report (13 Jan 2015) - MCLS, ESS, SNTY, NPT

Good morning!
McColl's Retail (LON:MCLS)
Share price: 181p
No. shares: 104.7m
Market Cap: £189.5m
Trading update - this convenience store group updates for the six weeks to 11 Jan 2015. It describes trade as "resilient", but LFL sales were actually down, at -0.9%. OK that's not much, but bear in mind that retailers have general cost inflation running at maybe 1-2%, so they need to generate a small positive sales growth each year just to stand still in profit terms.
Total sales were up 4.7%, which suggests that they've opened a fair number of new stores in the last year, or enlarged existing ones.
It's interesting to note that McColls says they do not experience strong seasonal fluctuations in trading, as they are used for top-up purchases throughout the year, rather than a main shop.
Post Offices are key to this business, I seem to recall, from last time I looked at it.
Value metrics look quite good (especially the divi yield), but quality measures less so.
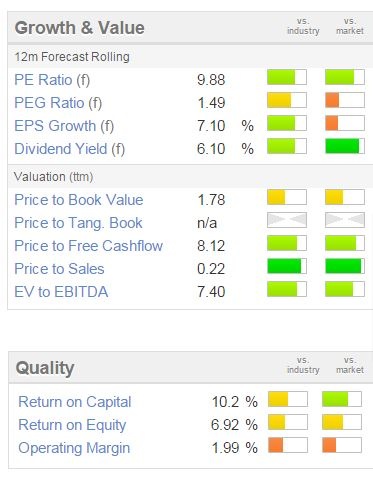
Note also that the free cashflow isn't bad.
My opinion - I think it's dangerous to chase a high dividend yield, and end up buying not very good quality businesses that might not be able to pay generous divis forever. This is a very low margin business, in a highly competitive sector, and I've seen in my local area how existing convenience stores find it impossible to compete as soon as Tesco, Sainsburys, etc, open a convenience store nearby.
For that reason, I would only dabble in this share if it was on a PER of about 6 - to me that's the right price for a not very good quality business in a very competitive sector. Feel free to disagree, it's only my opinion.
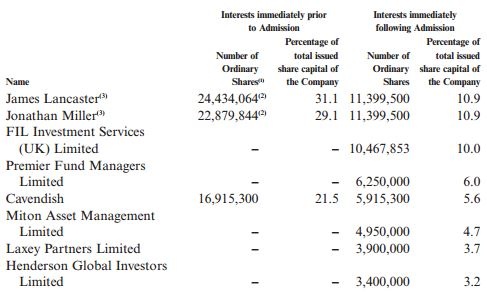
Also, I am always highly sceptical of all IPOs. After all, if the business was so great, why do they want to sell? Here is table B6 from their Admission Document, showing the shareholdings of the previous owners, and how they reduced in the IPO - the majority of the IPO proceeds went to the previous owners.
Essenden (LON:ESS)
Share price: 70p (up 2p today)
No. shares: 50.1m
Market Cap: £35.1m
Trading update - the company cleverly mentions full year LFL sales first, which are up 6.6% for the 52 weeks ending 28 Dec 2014. Sounds great, but if you check back to the last trading update, LFL sales were up 9.2% year-to-date when reported on 18 Sep 2014.
The trend has therefore been a deceleration of sales growth, indeed it was only marginal, at 0.1% for the four weeks to 11 Jan 2015. That suggests to me that the low-hanging fruit of the turnaround has probably been bagged, with the company now up against much tougher comparatives.
Nevertheless, the EBITDA and adjusted profit figures for 2014 look good;
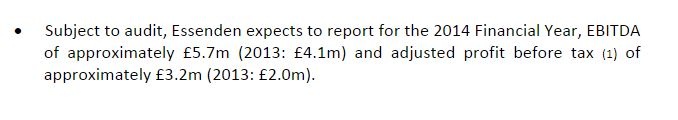
Net cash (excl. finance leases - on equipment presumably) was £2.3m.
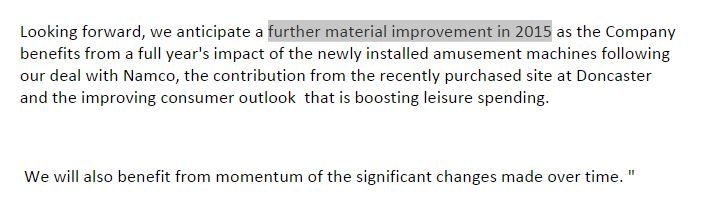
Outlook - this sounds good;
My opinion - I am an existing holder, and there's enough red meat in today's announcement to make me happy to hold for the next six months at least. These figures look ahead of broker forecast, and the valuation seems reasonable to me. I like it. Very illiquid though, and a horrible bid/offer spread sometimes. Hopefully they will start paying divis soon?
Synety (LON:SNTY)
Share price: 190p
No. shares: 8.4m
Market Cap: £16.0m
Quarterly KPIs - look good to me. The growth rate of annualised recurring revenue (the most important KPI) has accelerated in Q4.
I am hoping to speak with the company at some point, so will come back and update this section after I've queried a couple of points.
UPDATE: Right, I'm up to speed on Synety! I have copied below the KPI table published today. The most important line, in my view, is the first row, Annualised Recurring Revenue - i.e. this is the current monthly run rate of revenue, multiplied by 12. This is appropriate as a performance measure because almost all SNTY's revenue is monthly fees paid by customers, as is usual with telephony products.

Just as a quick reminder SNTY's product is a cloud telephony system which integrates into clients' CRM systems. So it places recordings of telephone calls with each customer into their client record on whatever CRM system is being used (e.g. Salesforce). SNTY integrates with about 30 different CRM systems, and more are being added all the time. It also now integrates with Google Chrome, which greatly increases the addressable market - but that's only just launched.
Growth in Q4 2014 was very strong - ARR rose from £2.22m to £3.02, in just three months! That's a remarkable growth rate.
My opinion - Synety is still loss-making, but I'm quite excited by the growth, which is being achieved organically. The product is superb (I've tried it, and it works briliantly). There is very limited competition, and SNTY has the keenest pricing. The company is on target to reach breakeven in Q1 of 2016, and has (just about) enough cash to get there. Cash isn't an issue - if they need to raise a small amount (say £1-2m) that could be done with a few phone calls, so I'm not at all concerned about cash.
I am very enthusiastic about this share, as I can see the potential for this to be a much bigger company in a few years time. The product is superb, customers love it, and client retention rates are extremely high (almost 95% of customers renew after 12 months).
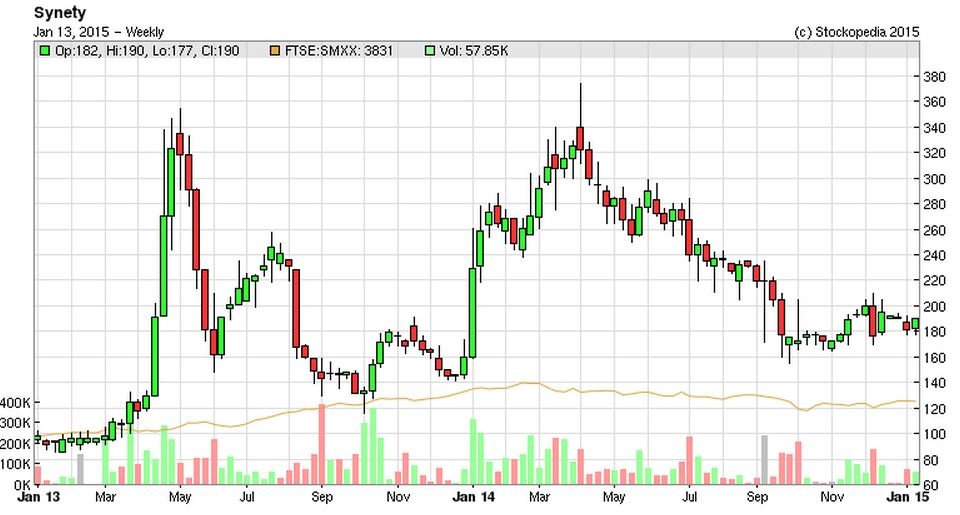
It's speculative and quite early stage, so definitely not a share for widows or orphans, but FWIW, I like it and can see a lot of potential here. Very smart management too. The shares are a rollercoaster ride, as you can see from the two year chart below. However, with the share price being low, yet performance KPIs being strong, that to me seems an anomaly, hence I've been topping up today. Please DYOR as usual, this is just my opinion, definitely not a recommendation, we don't do those.
NetPlay TV (LON:NPT)
Share price: 7.4p
No. shares: 296.6m
Market Cap: £21.9m
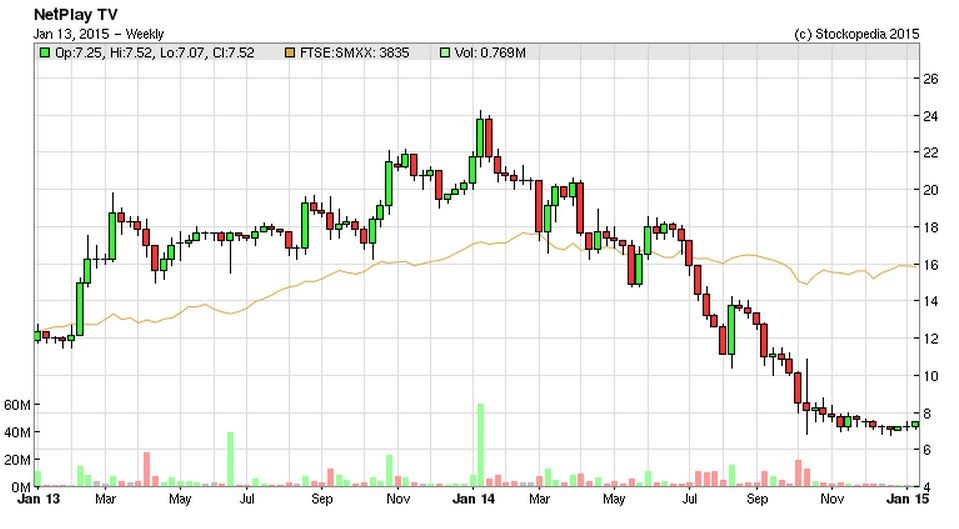
Trading update - 2014 results are in line with expectations. However, that doesn't really matter, as the change in taxation affecting online gaming has moved the goalposts, and could heavily dent profits.
For this reason I decided a while ago to sit on the sidelines until it became clear what profit Netplay might make in future, under the new tax rules, of the point of consumption tax. On this issue, the company today says;
My opinion - given that this company (like most) tends to put a positive spin on everything, if the best they can say is that they "remain cash flow positive", for me that rings big alarm bells. That suggests to me that they are now maybe marginally loss-making, but didn't want to say so, so instead have focussed on cashflow instead - since cashflow will generally be better than profits, as non-cash charges such as depreciation and amortisation are excluded.
The company does however have a strong Balance Sheet, with plenty of cash, although I note there is no mention of the cash figure in today's announcement. They indicate that acquisitions are possible, which suggests further to me that the existing business is probably not doing very well under the PoC tax.
I'm making some suppositions above, so could be wrong. However, I'm not going to risk it, and will await full year results in early April 2015 before looking at this stock again. It's not a bargepole stock due to the cash pile, but it's certainly on my "be very sceptical & cautious" list.
Remember there was very heavy Director share selling here a while ago - so as usual, follow the money! If Directors are offloading £millions of stock, it's telling you something!
All done, see you tomorrow!
Regards, Paul.
(of the companies mentioned today, Paul has long positions in ESS and SNTY, and no short positions. A fund management company with which Paul is associated may hold positions in companies mentioned).
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

15 comments
re: SNTY - revenue approx 8m for 2014?
I am deeply suspicious of companies who invent new metrics for their success, because by conventional metrics things are not going that well. E.g. in the dot com boom people talked about "eye-balls" (page-impressions), and then "user-registrations" chiefly because revenue, let alone profit, was non-existent.
SNTY has its KPI's. Will the product ever be big enough in revenue to justify the market cap? It's easier to double revenue when revenue is a low base. Not sure SNTY qualifies as small cap VALUE.
Of course in the future, this could all change, but on the basis of what I see currently (the facts)....
Checking the Stockopedia rating, it has a value rating of 3/99 a quality of only 5 and a stock rank of 1.
winning and then losing and then winning like that doesn't half make you learn from your mistakes. I didn't have leverage but I was exposed to oil services, mining, oil and gold mainly during 2008/2009. It was painful but I won it all back by 2010 - basically buying zulu-type stocks. It was like shooting fish in a barrel from spring 2009 on, but the problem was having the guts to invest at all. I was probably only 50-75% invested for a couple of years. Really I should have plunged from summer 2009 on - 100% invested, but was hyper-sensitised to risk by paper losses in 2008-early 2009. At least I didn't sell at the bottom.
Cyber interesting post, if you don't mind me asking what were your big winners that contributed to a spectacular 1500% return. I follow the Naked Trader and although he's up about 2 mil an awful lot of that was generated by two massive winners.
Several shares clarea, since 2009 I have made 5+ baggers on CIU, YELL, AGQ, QFI, and a number of doublers or treblers (most recently KIBO). I have learned to be bold and go in heavy if I think something is genuinely severely undervalued for a clearly explicable reason like a large seller or a discounted placing (Paul Scott came up with an excellent example a couple of years ago in TNI which almost 10-bagged). I like trying to wait for capitulation on bad news in a company which people panic and think is going bust but clearly isn't.... Regrettably I have also made some foolish errors through greed (rushing in, buying too high and/or failing to sell), particularly in the 2012-13 period, which have pegged my returns way below what I could have had... but that's life, I am learning all the time like the rest of us! No advice intended of course. Best of luck.
Interesting Paul, my sympathies. I can imagine you were indeed "all over the place emotionally" for a while after that roller-coaster :-(
I had a similar experience, came into the markets for the first time in spring 2007 (spectacularly bad timing!) with X quid in my portfolio, got sucked in and foolishly/inexperiencedly threw more money in chasing falling knives in 2008, by summer 2008 had lost over 80% of my (and unfortunately my family's) life savings... I was also severely "all over the place" emotionally for about a year... picked myself off the floor in spring 2009 and since then I have made around 1500%... so in fact after all that time I am only a little over twice 'X' value in my portfolio! But I suppose over 8 years a 'net' 120%-odd profit would probably still be considered a good return compared to putting it in the bank... if an AWFUL lot more stressful!!
I have come across a few people on the bulletin boards since my debacle who have also lost heavily in some dogs, and been in serious depression, and tried to help them by getting them to take a step back and have the courage to either (a) cash in their remaining shares and walk away for good, or (b) cash in their shares, take a break, and then look long and hard to consider how they are going to make it back, slowly and methodically. Sounds like you and I chose (b), but there is no shame in (a) at all - many, many people have lost their fortune in the stock markets and got over it in the rest of their life.
Best wishes, and thanks for all the continuing insights into investment, which are very helpful.
Hi Paul,
Glad to see you bringing McColls up for discussion.
I had a quick look over this after John Lee mentioned it on 12 Dec in the FT. He's attracted to the yield & the defensive nature. He also considers the business must be attractive to others wanting to expand in the sector.
In this particular case, I dislike:
(i) Very small profit margins, with no obvious catalyst to increase them. Possible increasing competitive pressure.
(ii) The balance sheet
(iii) The takeover potential could be currently reduced as all the big supermarkets are currently struggling with their own issues. However, I guess the profit margins might increase if this chain was taken over by a big 4 supermarket and had their economies of scale on the purchasing side.
Incidentally, I've been following both your excellent posts and the articles written by Lord Lee for some time now. Would be very interesting if you ever decided to post details of your long term percentage returns in the same way Lord Lee has done.
Jeff
Hi Jonesjeff,
I've commented on my returns here before.
In a nutshell, I made £multiple millions (no idea how much, but somewhere between £5-10m, pretty much from nothing) from the markets from 2001-2008, then blew it in 2008 when the credit crunch hit, because I made the huge error of using gearing on large positions in illiquid stocks, which I couldn't get out of.
So I've been rebuilding essentially from scratch since then. I was all over the place emotionally from 2008 to 2012, but properly refocussed in 2012. Since then I made 200% on my long term value portfolio from 2012-13, and I lost 15% in 2014. So that's about a 155% gain in the 3 years from 2012-2014 (calendar years).
On top of that, I do short term trading, which was lousy in 2012-13, but spectacularly good in % terms in 2014, albeit from a fairly small starting size portfolio. I haven't worked out the figures on that.
I think that pretty much sums it up!
Regards, Paul.
Thank you Paul. Sounds like you have potential for a top selling book there.
Considering you seem to be very value focussed, it's interesting to see such a spectacular performance profile!
Are you still using gearing (in any form) in the last 5 years?
How do you feel about sloppy companies that have to reissue an RNS - especially if there are several numbers wrong as in the RNS of Synety (LON:SNTY) this morn.
Could not agree more on McColls, the convenience store business is very susceptible to the big 4 opening up against them. Where I live a few convenience store popped up and seemed busy, then Morrisons opened a local, and a few of them have already disappeared. If they are in good spots, one of the big 4 will open up there, if they're not good spots, then how good a business is it ?
K
Imran, thank you.
Paul, also any thoughts on IDOX, one of Ed Croft's naps for 2015?
I had a brief look at the IDOX full year results issued this morning and my thoughts were:
- Profit before tax was broadly flat at £7.58m for 2014
- There is a large amortisation charge of £5.9m for the current year
- They're capitalising £1.64m in intangible assets so I'd therefore broadly agree with their adjusted EPS of 3.25p for 2014
The balance sheet looks weak to me, with net tangible assets negative to the tune of £18.2m
Therefore my view just based on the numbers is that the current share price is up with events and I can't see much value in the company based on performance in 2014.
Paul, I know DEB is not small cap but about a year ago you sounded cautiously positive on the stock. What do you think of today's RNS?
Many thanks.
Hi Paul. Would be keen for your thoughts on Netplay (NPT) given trading update today. POC tax is an overhanging issue but they confirm trading inline and the metrics all look good. Thoughts....?