Small Cap Value Report (13 Jan 2016) - HOME, SPD, SHOE, RGS, XAR, SGI

Good morning!
I had a second wind yesterday, and added some new sections to yesterday's report in the evening, covering: Avesco (AVS), Best of the Best (BOTB), and McBride (MCB). So if you haven't seen those sections, then this link to yesterday's full report is a good place to start.
The main indices seem to be stabilising after the recent sharp sell-off, although everyone seems terribly nervous still. Although personally I am enjoying the buying opportunities, and see a correction as healthy. Even though the economic data is softer in the US, that doesn't automatically mean that we're heading into oblivion again.
With most of the retail sector having reported now, it seems as if things weren't as bad as feared, generally speaking. As always, it's all about execution, so good companies trade reasonably well, even in difficult conditions.
SBRY / HOME
(at the time of writing, I hold a long position in HOME)
J Sainsbury (LON:SBRY) seems motivated to push ahead with its possible bid for Home Retail (LON:HOME). Sainsbury has published this document on its website setting out the rationale for the deal. Having read this, I feel it's far too light on the numbers. It's all very well coming out with management buzzwords, and generalised waffle, but if I were a SBRY shareholder, I'd want some hard figures to justify the deal.
As a retailing man myself, I can entirely see the logic for the deal, it makes complete sense. Especially considering that Argos branches are already within some larger Sainsburys stores - so the trials have worked, thus proving up the concept of store combinations.
Plus SBRY knows Homebase inside-out, as it used to own it. Going forwards, retailing is all about multi-channel. So the winners will be not only the best at operating physical stores, but will also have the best IT and logistics, to satisfy customer demand in store, by home delivery, and click & collect. HOME adds expertise in some key elements of that which SBRY is currently lacking.
With cost synergies, and letting go of some of the Argos estate, and putting them into larger Sainsburys stores, it's entirely feasible that SBRY could drive profits at HOME up from c.£150-200m to perhaps £300m+. That would be a fantastic outcome for SBRY shareholders, given that the EV of the acquisition price could be as low as £400m (given that most of the consideration will actually just be giving back HOME shareholders their own money from HOME's balance sheet!).
Sports Direct (LON:SPD)
(at the time of writing, I hold a long position in this share)
Continuing the retail theme (and please note that I stray outside of small caps in these reports, into larger companies sometimes, but only for the retailing sector, as that's my sector specialism), there's an intriguing announcement today.
Strategic US investments - Mike Ashley has a history of buying stakes in other retailers through Sports Direct, in which he is the majority shareholder, so has complete control.
Today Sports direct announces that it has taken stakes in two US sportswear companies, using Contracts for Difference (CFDs) - a leveraged instrument that mimics owning the shares in terms of financial risk:reward, without having to stump up the full cost of actually buying the shares.
11.52% stake in Iconix Brand Inc (NSQ:ICON) - underlying value c.£19.3m (based on market cap of £167.8m) - note that I am working in sterling, having converted from dollars.
A quick review of the Stockopedia page for NSQ shows that it is very highly geared, with an EV of £1.19bn, so over £1bn in net debt. Also note that it achieves an operating profit margin of 47.7%, amazingly high. This fits with the company's activities - it owns brands, and licences them to manufacturers. The Stockopedia profile summary gives a synopsis, from which it becomes very obvious why SPD has taken an interest in it;
So clearly this deal is all about trying to gain access to the brands which Iconix owns. I hope he doesn't go for a takeover, as that would mean assuming a large amount of debt.
2.34% stake in Dick's Sporting Goods Inc (NYQ:DKS) - this is a US sportswear retailer, with c.$7bn turnover, and a reasonable operating profit margin which is around the 8% of turnover level. Stockopedia shows it is rated on a fwd PER of 10.6, which seems fairly reasonable. The shares have been sliding since Apr 2015, when they peaked at nearly $60, to around $35 at present.
The market cap of Dick's is c. £2.8bn, which is the same ballpark as SPD's market cap of around £2.5bn. SPD's 2.34% stake has an underlying value of £65.5m, so it's a meaningful exposure by SPD, and looks an interesting investment. I might follow them and take a long position in Dick's, once I've researched it, as it looks quite good value at first glance.
Shoe Zone (LON:SHOE)
Share price: 187.5p (up 12.6% today)
No. shares: 50.0m
Market cap: £93.8m
Results, 52wks ended 3 Oct 2015 - the highlights are self-explanatory;
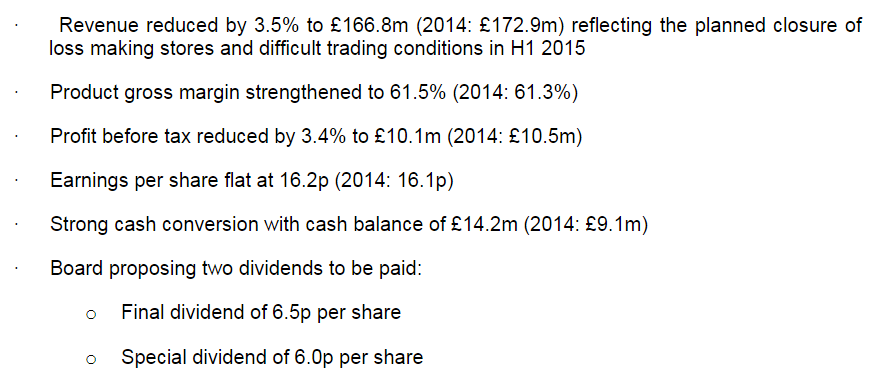
That's a very good gross margin - which is important because retailers need strong margins to make enough profit to cover all the fixed costs of High St sites.
Although profit was slightly down, EPS was slightly up, due to a reduced tax charge.
Balance sheet - looks great. Working capital is very healthy, with a current ratio of 2.02. There is no debt, and the company has net cash of £14.2m, a very healthy position. Note that there is a £5.2m pension deficit.
Cashflow - this a strongly cash generative business - note operating cashflow is consistent with last year, at £14.2m (£14.8m LY). Also, the shopfits are done on the cheap, so there's not a great deal of capex, although that might increase in future as larger shop units are to be tried out.
Dividends - given that this business is a cash machine, it's paying out not only a 6p final divi, but a 6.5p special divi on top. Very nice!
Outlook - a bit mixed. Trading in Q1 (Oct-Dec 2015) sounds like it has not been too good, but no figures are given;
Shoe Zone's trading in the first quarter of the year has been challenging, amid the well documented high street trading conditions for clothing and footwear retailers. Despite this we have continued to make progress against our strategic objectives. Our stock position is well controlled and we have achieved strong gross margins choosing not to discount stock before Christmas as is usual for our business. We anticipate the full year effect of our new merchandise director will continue to improve our stock and cash position.
...The falling oil price is already having a positive impact on the cost of logistics and should also impact the price of raw materials thereby improving gross margins for the remainder of the year.
So it sounds as if sales might struggle this year, but margins should do well - offsetting influences. I am perturbed by the downbeat Q1 comments, as this could be lining the company up for a profit warning later this year perhaps? Although as we saw with the profit warning last time, it wasn't a disastrous one.
My opinion - overall then, not a bad set of results in the circumstances, and the spike down in price in recent days looks to have been spurious.
The great news today on divis looks to have been the prevailing influence on the share price today. Also, the commentary says that any cash balances over £11m will be paid out in special divis, so this share could be a nice cash machine for investors in the longer term too.
I'm not sure there is much upside on the actual share price from here, but it looks worth holding just for the future dividend stream, if you can live with the share price volatility.
Regenersis (LON:RGS)
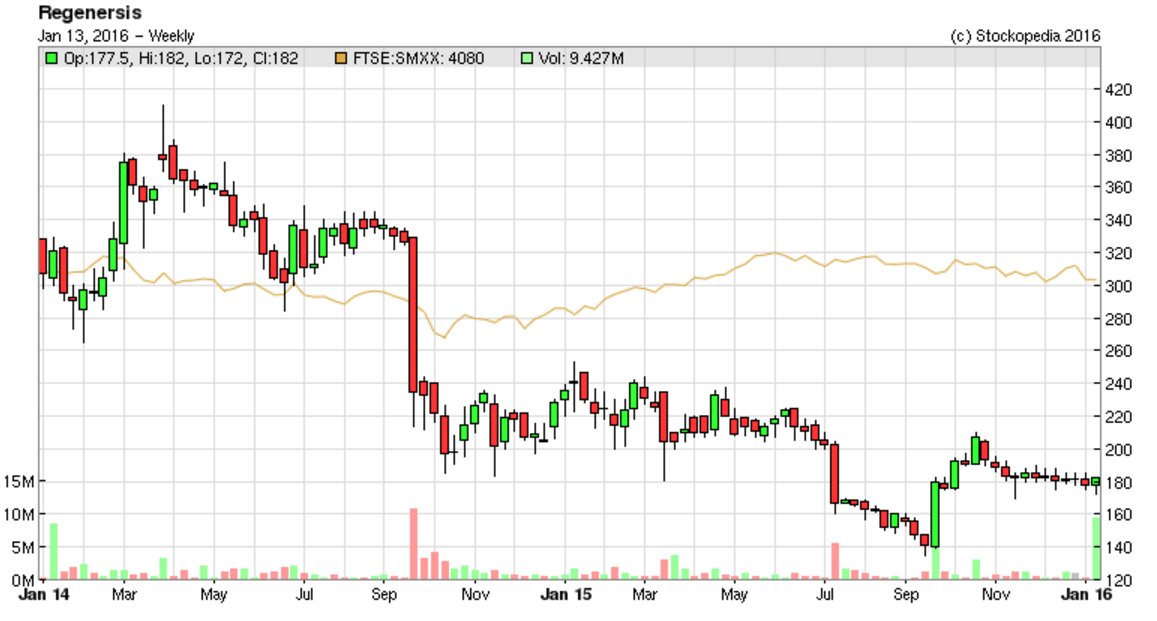
Share price: 182p (up 3.4% today)
No. shares: 79.0m
Market cap: £143.8m
Trading update - this group has a 30 Jun year end, so is reporting today on H1 to 31 Dec 2015. It says;
The Group's performance in the first half of the current financial year was strong compared to the prior year and in line with expectations.
The Software business significantly increased sales, in line with the market's expectation for the full year, whilst also maintaining its operating profit margin. The Aftermarket Services businesses performed in line with expectations.
That sounds straightforward.
Outlook - the background is that the group is being rejigged - what used to be the main business, a collection of low margin electronics repair companies, is to be sold off. The new group will focus on data deletion software.
We are updated today;
As a result of the strategic review process announced in September 2015, the board has received several indicative offers for the Aftermarket Services division. Although there can be no assurances, this process remains on plan and has moved onto its next stage within the expected time frame.
My opinion - this share is impossible to value at the moment, as we don't know what the likely sales proceeds are for the legacy business. I'm unsure how to value the software business too, so really this share is just a punt at the moment, until the figures become clearer.
I'm wary of management, and the way they present the accounts (too many adjustments), so won't be investing.
Xaar (LON:XAR)
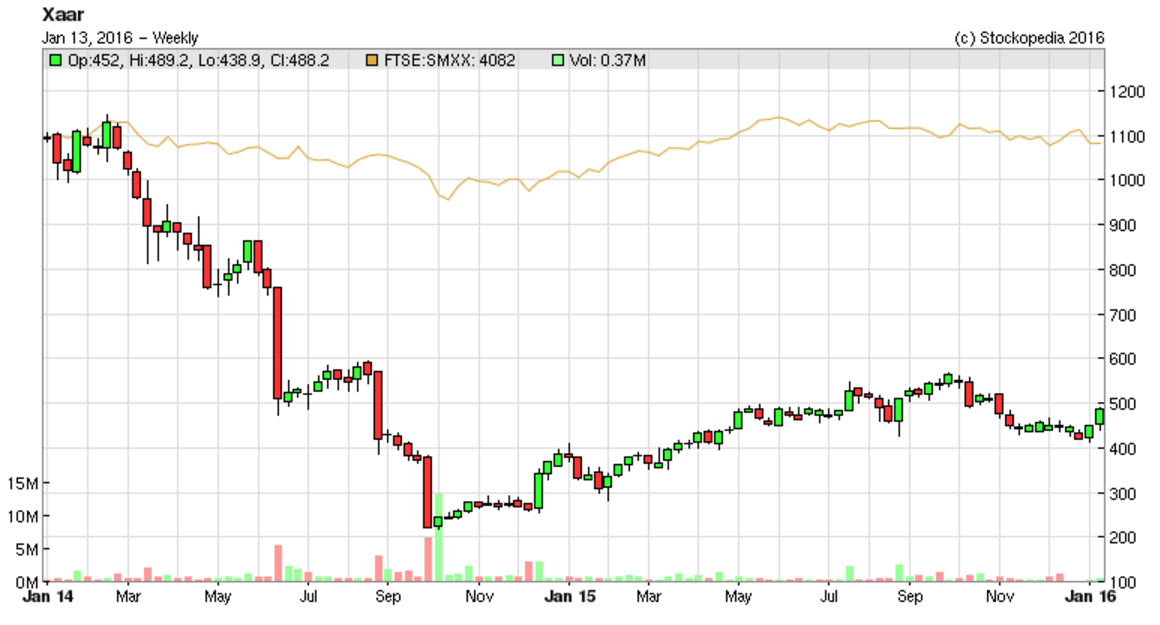
Share price: 488p (up 8.2% today)
No. shares: 77.5m
Market cap: £378.2m
Scheduled trading update - I like the use of the word "scheduled", which reinforces that it's probably not a profit warning! It looks as if the company has managed the downturn in revenue well, maintaining a strong operating margin through cost-cutting;
In line with the Board's expectations, Xaar expects to report total revenue for 2015 of approximately £93.5 million. Since the last trading statement on 4 November 2015 sales have performed in line with expectations, with revenue growth in packaging being offset by the anticipated softening in demand in ceramic tile printing in China.
As a result of improved operating efficiency at both the Sweden and Huntingdon manufacturing sites Xaar expects to report an adjusted operating margin for 2015 of approximately 20%.
The Group remains in a strong financial position with net cash at 31 December 2015 of £70 million (30 June 2015 - £59 million).
My opinion - the big problem that Xaar has been grappling with in recent years, is declining demand from China for its ceramic tile printhead. This has been the mainstay of the business.
I certainly wouldn't want to invest right now in any company which is hugely dependent on sales to China, would you? Worse still, it's sales into just one specific niche, in one country, and the country that is probably the most worrisome of all major economies.
True, Xaar has other interesting things in the pipeline, but to my mind the market cap is much too elevated given the risks. That said, if the company can make a commercial breakthrough into other sectors, and it tends to see waves of adoption of its innovative printheads, then who knows what the future holds?
Risk:reward looks unattractive to me, right now. Although my judgement may be clouded by my having been scalded on the shares in 2014. I often see that trait in other investors - they refuse to accept that a company is a good investment, if they have previously lost money on the shares. Maybe I'm doing that here, subconsciously?
Stanley Gibbons (LON:SGI)
Share price: 59.5p (down 13.1% today)
No. shares: 47.1m
Market cap: £28.0m
Share price movement - this sounds odd;
The Directors note the recent movement in the Company's share price and would like to update on current intentions for funding the business.
In response to a number of unsolicited enquiries from shareholders and other investors, the Board is considering a number of fundraising alternatives to reinforce the working capital position prior to the year ended 31 March 2016. However, whilst an equity fundraising is one option potentially available to the Board, the discount to the Group's net asset value at which any such fundraising would likely be priced could make it a relatively unattractive route to alternatives under consideration. The Directors will update the market on the progress of these considerations in due course.
Let me translate this for you. We're in a financial mess, and are looking at various ways to raise money. Equity financing is available, but on lousy terms, so we're trying to see if anyone will lend us money instead. The bank are not keen on extending the overdraft.
Whilst the balance sheet looks apparently strong, the big unknown is what the last reported £54.9m of inventories are actually worth in reality. Given that stamps have no intrinsic value, they're just tiny pieces of old paper, they're only worth what someone is actually prepared to pay for them. That could be a fraction of book value, for all we know.
My opinion - it looks high risk to me. I think there could be a huge writedown of inventories to realisable value, and in a fire sale that could be a fraction of book value. If they had to write off say two thirds of book value on inventories, then current assets would be a £36.6m hit, and would take current assets down to £41.1m. Total liabilities are £45.3m, so that would put the company in a precarious position, with net tangible assets of barely above nil, once you add in the £6.1m property, plant & equipment.
OK, a two thirds write off on inventories is a savage cut, but I wouldn't be surprised to see that kind of figure happen to shift inventories which are not now in such demand as they were when Chinese buyers were bidding up prices.
Overall, I think this could be a value trap, and is best avoided, so am putting it on my Bargepole List - admittedly closing the stable door after the horse has bolted. At the very least, the valuation is now too uncertain in my view, and with financing issues now rearing up, it's not one I shall be revisiting, until there is more clarity.
All done for today!
Regards, Paul.
(of the companies mentioned today, I have long positions as noted above, and no short positions.
NB. These articles are my personal opinions only, which are subject to change without notice.
Please always DYOR)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

31 comments
Proposed sale of Homebase confirmed, price 340m pounds, proposed cash return of 200m pounds to shareholders, info on updated financial position:
http://www.investegate.co.uk/home-retail-grp-plc--home-/rns/response-to-media-speculation/201601131822168105L/
That is only about 24p per share?
Re: Sainsbury/Argos
I seem to be in a minority of one but IMO the deal makes no strategic sense at all.
Obviously the retailing sites and internet knowledge are valuable to Sainsbury, however Argos's own management havent been able to turn it round and it will be a massive distraction for Sainsbury who face a much bigger business model pivot challenge if they are to ever seriously compete with Aldi/Lidl.
They should be concentrating on this much more than a desperate attempt to add unrelated product lines and tons of retail space (when most retail analysts dont think extra space is the answer).
Go in to any of the top UK supermarkets (I have) and be awed by the lack of competitive challenge to a typical LIDL. I bought 6 eggs at 4x the cost LIDL charge and couldnt taste any difference.
Its classic strategic inaction, i.e. after 50 years of ripping consumers off (UK supermarkets have made double the net profit % of US supermarkets at c.8%). This has led to a culture of not having to change for so long that they obviously now can't. Until they overcome this they should not undertake any other distractions (e.g. like HomeBase was last time they couldnt solve that either).
99f, agree with you re: the lack of innovation in UK supermarkets.
I'm a regular visitor to California and the contrast with UK supermarkets couldn't be more pronounced. Bagging your own groceries? No way. Scanning your own shopping? You're kidding. Sky high prices? Rude customer service? (yes, even in my local waitrose they're as stroppy as hell)
The UK retail experience ( can't comment about Lidl or Aldi) is crap. I think the logistics logic for sainsbury is sound and HOME is undervalued, but I see it as a last ditch attempt by Sainsbury to divert attention away from their declining business and bring in new tech - after all Sainsbury don't even have contactless payment? I mean, what a joke! Their head of IT should be sacked - it's embarrassing.
Now to Sports Direct - never buy something just because it's cheap. Those suckered in to what they believe is a cheap share price are similar to the Sports Direct customers who believe the advertising about how much a product has been marked down and rush to buy it.
Quite simply it should be in private hands. With Ashley at the helm it's a barge pole of the longest length.
And Stanley Gibbons - it looks like the valuation is dependent on their inventory - who can guess what that's worth? I'm sure the potential customer base is dwindling by the day.
In terms of the auction business, you only need look at the devastation eBay has caused to the antique business to see that it's s declining part of the sector.
I am a Telegraph reader and follow John Ficenec with interest, but not always with any degree of concordance.
He was not impressed with Boohoo's Christmas trading update in today's edition. Points of criticism included... 'a sharp fall in GM from 60.8% to 55.7%'...'cutting costs by reducing spend on marketing'...'increasing expenses by offering customers next day delivery'. His conclusion? ...Telegraph readers should avoid the share.
Fortunately, followers of this column have the benefit of the more erudite views of Paul when forming a view on the worth of a particular share.
Something add is happening at Trakm8 Holdings (LON:TRAK) - an acquisition and an oversubscribed placing was announced, to complete by the end of December or, with the NOMAD's agreement, by the end of January. It hasn't yet completed and the share price has fallen well below the placing price.
If the acquisition has fallen through, then TRAK should be little worse off than it was a month ago. So what could be the reason for the slide in price?
I love the SGI translation, Paul.
Inventory write-offs are looking highly likely.
Tapping "Stanley Gibbons" into Google Trends makes for worrying viewing. The trend has been downward over the last decade. I suspect that's management's motivation to diversify into other things.
"the Board is considering a number of fundraising alternatives to reinforce the working capital position prior to the year ended 31 March 2016."
Presumably, whereupon, the whole carraige will turn into a pumpkin.
Heres the article re Homebase sale for £350m
http://news.sky.com/story/1622098/wesfarmers-in-talks-to-buy-homebase-for-350m
Sky news have just announced that Homebase is in advanced talks with Australian DIY chain called Wesfarmers for £350m - game on for big share rise tomorrow.
Re HOME
To put the value of this company into perspective, by liquidating the loan book and using the excess cash, HRG could afford to pay a special dividend of 85p and the company would still trade at about 90p a share after that.
Just think what value Sainsbury's could add to that by synergies and utilising its floor space to close down circa 175 stores. SBRY could pay £2 a share and still have a good deal.
Paul,
Re Xaar (LON:XAR). Share your concerns re focus on China and single product sector but the business has good IP and the potential for some of the products in its pipeline could be significant. Also this is probably the last major listed UK industrial ink jet business and must be on the acquisition target list of many overseas players (US, Japan, etc.)- no doubt they too are biding their time given the risks of the current product/sector focus. Linx Printing Technologies and more recently Domino Printing Sciences have been acquired by Danaher (NYQ:DHR) and Brother Industries (Japan) respectively . Maybe the market thinks Xaar will be next given today's share price reaction to a relatively muted trading update.
I agree, the key thing in todays statement is the switch from China ceramics into other areas like packaging, so China has gone down but its been replaced elsewhere also the margins have increased to around 20%, no wonder the shares are up 10%.
Paul,
HOME/SBRY:
Not having lived in Britain for quite some time, I'm rather puzzled why "click and collect" seems to be seen as something new and innovative and why this is seen as one of the key features and attractions of Argos.. It has been common for years now that online sites in other countries offer one the choice of mail or courier delivery or collection at one's own choice of any one of several points in your neighbourhood. Obviously, this would not apply to very heavy or bulky items, I appreciate that. For just about everything else, I can have deliveries made to my local "maison de la presse" in France or to the local computer shop in Spain and then simply collect them when it suits me. The concern about the dreaded "whilst you were out" card just doesn't apply. There must be something similar in Britain, surely? If not, it would cost very little to set up such a collection network.
SPD:
Iconix is reportedly the owner of the "Umbro" brand. That may well be part of its attraction for Mike Ashley:
http://www.insidermedia.com/insider/national/sports-direct-ups-stake-in-umbro-owner?utm_source=northeast_newsletter&utm_campaign=northeast_news_tracker&utm_medium=deals_article
SGI:
Their inventory valuation can really be anything they like since for much of their stock there'll be very little to compare it with. Its true value is only known once it's sold and they seem to be having trouble selling it which perhaps indicates it's not worth its carried value?
Its not that new but it s become popular lately. Many internet based retailers are doing it, however if they only have a few shops then its difficult for them to compete with the likes of Argos who are in most towns. Interesting some ebay items you can now pick up free at your local Argos. Yes some you can pick up from your local shop but there is often a charge for this. Click and collect suits many people in uk who are in and out all day and dont want to wait in all day for a delivery.
I iiked the idea of Argos becoming a sort of pick-up point at the station. I suspect sucking it into the Supermarket chain will destroy that opportunity and the first competition that Amazon was ever going to get will be gone. Homebase has been a dog for years and needs to be shot.
I do like the rationale for the Sainsbury's / Home Retail proposal but I am less confident in them agreeing terms. The Home shareholders seem a bit greedy to me - no harm in trying but if your opening position is silly then the negotiation won't get far. Sainsbury's may have to go hostile. We'll see - I would like to see it work.
Brackendale
"I have absolutely no doubt that if you think Sports Direct is a good business at a cheap price, then it is. But I cannot work out why you think this - its not particularly cheap on PE or on book value, ROCE not that great, its already a big firm,etc. Could you educate me? (this sounds sarcastic but I am being absolutely sincere, just trying to educate myself!) "
Looking at next years forecasts the p/e is currently only 11 - this must be below the average for FTSE 100. I think there is pereived to be less risk with buying shares in larger companies (did i buy Rolls Royce shares recently yes- doh). so 11 * seems reasonably cheap to me for a quality money making machine.
The good thing about Sports Direct is that they have the brands to go with the retailing, a very clever strategy that makes them a cut above most other retailers and they have proven themselves competent at being able to grow the business for a long time. Maybe they are the next Tesco type Banana skin if they are being a bit unethical in their practices - but they give the punters what they want - a bit of cheap that that does the job.
Finally Mr Market was valuing the business at 800p a share not so long back so on the basis that a good company at some stage will revisit its highs there should be decent bounceback potential. strangely my first ever share purchase back in the early 2000's is nicely profit but still well below its all time high price - so that theory may be crapola too.
Thanks rmillaree, appreciated
You had me right up to this point:
Finally Mr Market was valuing the business at 800p a share not so long back so on the basis that a good company at some stage will revisit its highs
Beware the perils of "anchoring"!! Basing any investment decision on a historic share price is dangerous and you make a good case for this in mentioning Tesco... it will be a very long time, if ever, that TSCO gets back to £4. Just saying...
All the best, Si
Paul, in terms of Shoe Zone (LON:SHOE) cash flow, the first year rental discount tends to cover setup Capex. I don't see any reason for this to be different at their Big Box format shops, but would be interested to hear if not the case.
Hi Paul,
I have absolutely no doubt that if you think Sports Direct is a good business at a cheap price, then it is. But I cannot work out why you think this - its not particularly cheap on PE or on book value, ROCE not that great, its already a big firm,etc. Could you educate me? (this sounds sarcastic but I am being absolutely sincere, just trying to educate myself!)
Also, Stanley Gibbons saying today they are considering a fundraising? What are your views? On the other hand seems amazingly cheap to tangible book, and is incredible that has fallen from such highs (or perhaps it is incredible that it got to such highs). Any thoughts welcome.
Stanley Gibbons "tangible" book value....hmm.
I think this is based upon the stock/inventory that they hold and that as such it's value can't be certain.
Whilst they might think that the entire back catalogue of Good Housekeeping (or whatever it is they have in their warehouses) is worth a fortune, the fact that they haven't sold it suggests otherwise. The demand for a lot of the old tat that gets traded (stamps, back issues of Wisden etc.) comes from China and I think we're all aware of the reality of the economic situation there.
Also, talking to a few of the local charity shops near me (actually the root source of some of the stock that businesses like SGI trade), they are being inundated with donations, in some cases 4 - 5 times more than ever before and say that people are decluttering like mad (all very zeitgeist this move to a minimalist way of living) and there are all sorts of rare things turning up and finding their way into the market. More supply.....
A fundraising suggests to me that they can't shift the stuff at a price that they are happy with and would prefer to hold on to it in the hope that the demand picks up. In the meantime, they're running out of money.
I wouldn't touch it with a bargepole I'm afraid.
Hi JD72,
Thank you, that is interesting, particularly your point on the fundraising. And on a similar note to your point on supply, a second hand bookseller in London recently was lamenting that many older people are dying and their book collections being simply discarded by uninterested family.
It is amazing to me how quickly and drastically sentiment has changed for this stock. I wonder if sentiment could change in the opposite direction or not, for example if they having a storming second half.
I suppose the bear case is that Chinese demand has gone and the inventory has an unreliable value, whilst the bull case, a la Simon Thompson in IC, not everyone's favourite I know, is that the tangible book is much higher than what is on the balance sheet, because they are valued at cost.
I think I will put it into my "will be fascinating to watch" pile!
Thanks again for your reply
Valued at cost might very well be overvalued.
There are indexes for rare stamps and coins etc. but they are calculated by firms who sell stamps and coins as investments and unbelievably (literally) have shown remarkably consistent and impressive growth. Now, why would a firm selling a thing as an investment want to show that the value will never go down.....I wonder? I'm amazed they can get away with it to be honest.
It's not like a freehold property where you can look at the value of similar local land and come up with a sensible number. It's completely opaque. We simply don't know what they have in stock and hence can't value the company on a book value basis.
If this was all true a) clever rich people with deep pockets would be doing it (they're not) b) there would be loads of new companies starting up to get some of the action (they're not) c) SGI wouldn't be raising money
I quite agree. I think the main problem is Stanley Gibbons (LON:SGI) can't shift some of the big ticket items because of the situation in China, they may think a stamp is worth n million but until they sell it who knows. I have lost faith in the management I think they were ok in the old days before the internet took off. You know how much they spent on their website and it took 5 years. So of the recent acquisitions do not seem good value either, the disposals have been well below book cost.
Re. SBRY/ HOME. Thank you for the link for the strategy rationale. Interesting read.
It is clearly a ppt put together by MBA type management consultants, full of buzzwords and consultancy-speak. Gives me the shudders because regrettably I used to be one of them. Here is a choice bullet point
"
* Creates a leading food and non-food retailer of choice for customers
"
Really?
Still not convinced.
Morning Paul,
I totally agree that the purchase of Home Retail (LON:HOME) by J Sainsbury (LON:SBRY) makes sense, for the reasons they give and also to have a head start on Amazon, when they fully launch Amazon Pantry in the UK.
I'm sure that they have found a buyer for Homebase already as there was no mention of Homebase in the document.
As a holder of both - I think it's a win-win situation - two questions remain however:
1) What price will be agreed - Major Shareholders of HOME have stated they would want any bid to begin with a £2. Sainsbury's shareholders will have to be won over, especially the Qatar Holding Company, which holds 26%
2) Will another bidder appear? There has been rumours of Sir Terry Leahy heading a rival bid on behalf of Private Equity.
There is a lot of value to be unlocked from the HOME balance sheet but the key to sainsbury's is for them to get hold of the mobile & online infrastructure that HOME has developed (2nd only to Amazon in the UK). Sainsbury's management also realise that there is little growth available in food and margins are larger in none food. Through buying HOME they are saving themselves the time and effort to build the non-food arm of their business, which would take years.
Any thoughts on BDEV,Paul ? [Not a small cap,obviously].
Hi Paul,
I assume the Secured Property Developments (OFEX:SPD) section of today's SCVR related to Sports Direct and not Secured Property Developments.
Best wishes,
Imran.
Yes, I correct any glitches like that, with tickers shortly after publishing - now sorted.
Hi Paul, thanks for your analysis of SHOE. Where did you see the detail on the £5.2m pension deficit? I couldn't see that in the results.
Cheers