Small Cap Value Report (13 Jul 2015) - ALNT, SPRP, CVR

Good morning!
Greece
Grexit now appears to be off the table, with an all-night EU leaders conference apparently having thrashed out an outline agreement. So we're seeing a bit of a relief rally in UK shares this morning, although I think the market had correctly anticipated that a compromise would in all probability be reached.
No doubt the next panic will be whether the Greek Govt is able to pass the necessary legislation internally, or whether the Govt collapses, triggering elections? So I'll be keeping an eye on things, but personally it's only having a marginal effect on my portfolio decisions. Let's hope they get things properly sorted, so that Greece doesn't descend into a humanitarian crisis. Although things are bad in Greece, it's nothing compared with the terrible conditions being endured by people elsewhere, e.g. Syria - evidenced by the large numbers of people risking the dangerous crossing by sea, and arriving in packed dinghies in e.g. Lesbos - there was a fascinating TV programme about that last week.
M&A
Another interesting investment theme which I've mentioned recently is the surge in M&A activity - in particular, the high ratings for US companies means that they are hunting for relatively cheap acquisitions in the UK.
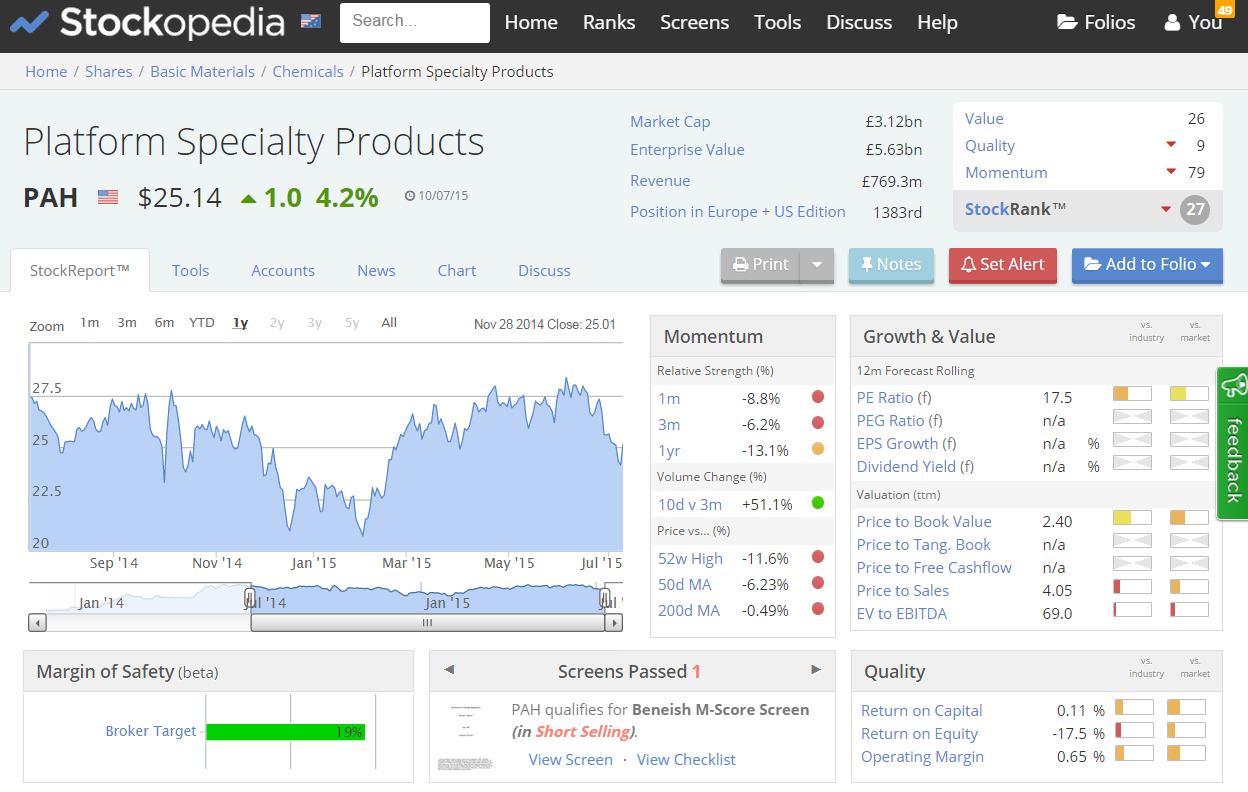
Today there is another deal announced - Alent (LON:ALNT) is up 45% this morning on news of a cash bid at 503p per share from a US company called Platform Specialty Products Corp. I'm lucky enough to have the European & US data on Stockopedia, so I've had a quick look at the StockReport for Platform Specialty Products (LON:PAH) and it looks pricey - a fwd PER of 17.5 looks high, given that Platform has a lot of debt, and a weak balance sheet (which is negative once you write off intangibles). Although scanning the news announcements from the company, it seems to have raised fresh equity and bonds since the last balance sheet date of 31 Dec 2014.
Here's the top part of the StockReport for Platform:
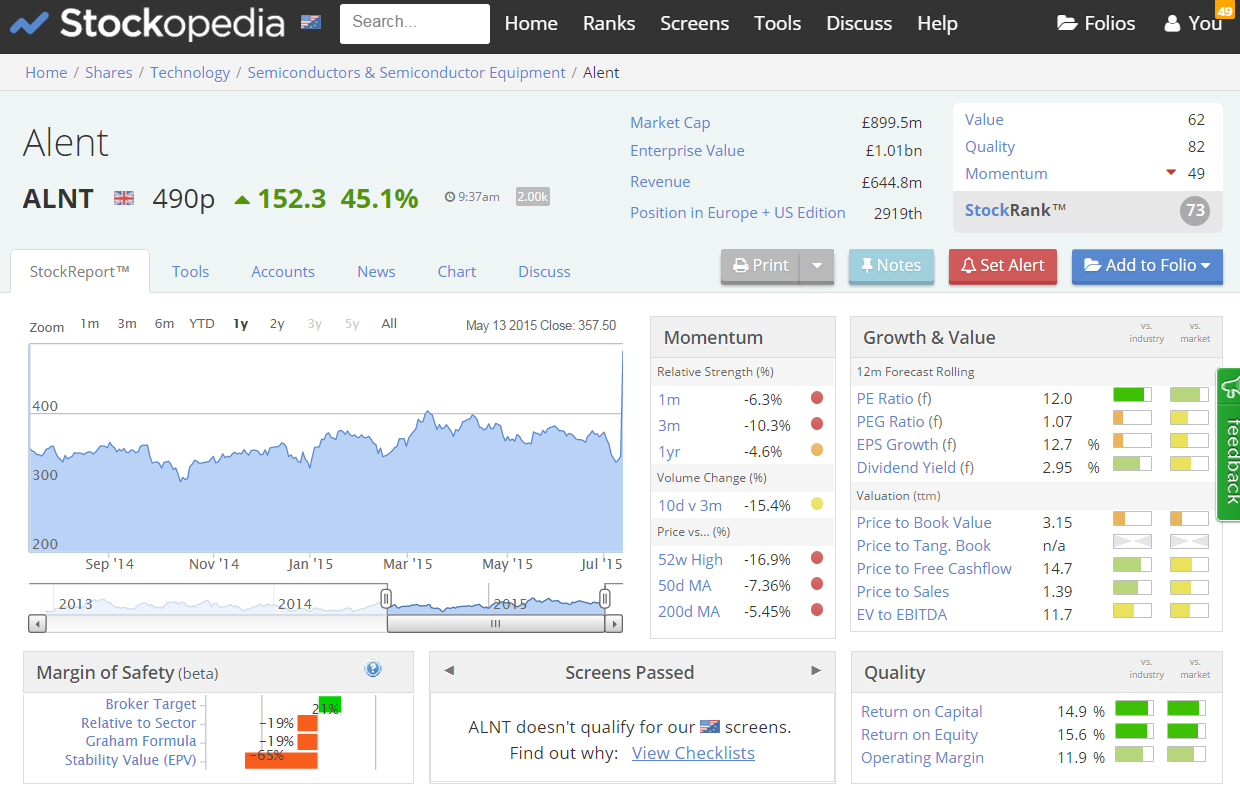
Contrast that with the target company it's buying, Alent (LON:ALNT) and you can see why the highly rated & heavily indebted US company sees the UK company as a bargain:
So I hope some of the M&A activity spills over into the bottom end of the market too, where I rummage around for bargains. Having a focus on value, and GARP, my investing approach does tend to happily see takeover bids quite often, which providing they are at a decent premium, is a good way to exit, and free up more money for new investment ideas.
Although I'm not at all happy at the latest takeover happening in my portfolio, that of Essenden (LON:ESS) - which is at a very poor price, where a major shareholder has obviously twisted the arms of management to agree a deal which seems very poor for other shareholders.
Sprue Aegis (LON:SPRP)
Share price: 330p (up 9% today)
No. shares: 45.5m
Market cap: £150.2m
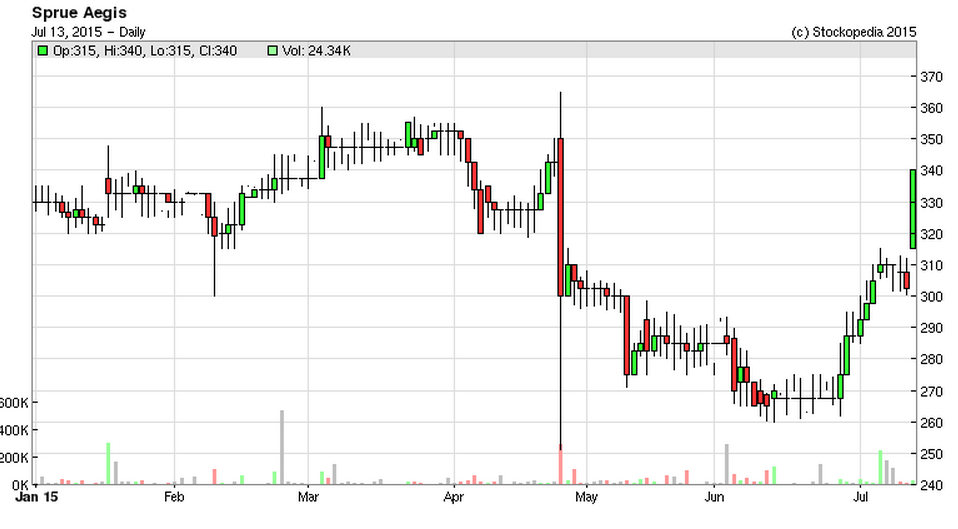
Trading update - today's statement from this smoke alarms company reads well, and patient bulls have been rewarded with a strong share price recovery over the last 3 weeks. This got me thinking about charts - some investors swear by the chart - saying that it will indicate to you in advance how the company is performing, because insiders will be buying or selling.
However, the chart at SPRP disproves this, and I can think of lots of other examples where big rises and falls in share price have been completely spurious. The only conclusion I can come to, is that large movements in share price may, or may not be related to fundamentals! Which isn't a lot of use really, is it?!
Note also the huge spike down (as indicated by the spikes on the candlestick chart below) in late Apr 2015, where a trading update seemed to cause investor confusion (hence the wild gyrations in share price on the day):
Today's statement reports excellent profits growth for H1:
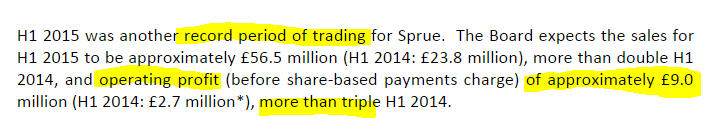
Bear in mind that the broker forecast shown on Stockopedia is for full year profits of £8.46m, but they have done more than that in just H1. So it's no surprise that the outlook statement today says (inter alia):
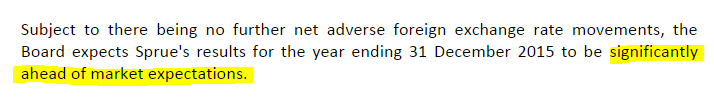
Net cash - has risen significantly, helped by a number of factors beyond just strong trading, such as extended credit terms with a supplier.
Currency movements - what's all the more remarkable, is that this excellent performance has been achieved despite currency movements being particularly costly. This reduced the gross margin from 37.4% to 29% in this period, which is a huge impact. The company quantifies this by saying that profits would have been an astonishing 68% higher, at constant currency.
I am surprised that the company left itself so exposed to currency movements, although it sounds as if they are addressing that by having agreed to buy in sterling from 1 Apr 2015. Although there's always the risk that companies put in place currency hedging arrangements after a heavy loss, and then miss out on the profit from that currency move reversing.
Sales in France - the company reiterates today that the bumper H1 trading was due mainly to surging sales in France, which look to be a one-off factor, driven by a legal requirement for landlords to fit smoke alarms in rented properties:
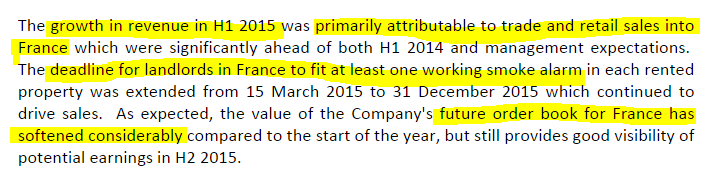
Also note that the order book for France has already "softened considerably".
Valuation - this is tricky, because it would be wrong to value the company based on EPS for 2015, since this is likely to be a one-off good year. It's more important to ascertain what the ongoing level of profitability will be.
So whilst broker forecast EPS of 18.0p for this year is likely to be thrashed - it wouldn't surprise me if the company delivers say 25p EPS this year. However, that is very likely to fall sharply next year. So the existing broker forecast of 17.0p EPS for 2016 is probably the more sensible figure to use as a basis for valuation.
Bearing in mind the significant cash pile, I think you could justify a valuation in the range of about 15-20 times 2016 earnings. That arrives at a valuation of between 255p to 340p. So at 330p the current share price is near the top of that range.
My opinion - with hindsight, it would have been a cracking buy 3 weeks ago at about 260p, indeed it was getting close to the point where I was interested in buying - my report here on 3 Jun 2015 concluded that there might be about 10-20% upside on the share price of 287p, but it wasn't sufficiently compelling.
Given the likelihood of earnings having peaked, and set to fall next year as demand in France dries up, I'd be more inclined to think about selling rather than buying, given the recent strong surge in price.
Conviviality Retail (LON:CVR)
Share price: suspended on 9 Jul 2015 at 155p
No. shares: 66.9m
Market cap: £103.7m
Results 52 wks ending 26 Apr 2015 - this company is not one I follow closely, so hadn't spotted that its shares were suspended last week, pending the issue of a prospectus for a reverse takeover deal (i.e. where the target company is bigger than the company buying it).
I'll come back to that later, but firstly looking at the results, they don't look madly impressive to me. Pre-exceptional profit fell slightly, from £10.0m last year, to £9.8m this year. Profit before tax rose vs last year, but that was due to the reduced finance costs line on the P&L.
Note that it's a low margin business, wholesaling alcoholic & other drinks to a chain of mainly franchised stores. So the operating margin is only 2.7% on turnover of £364.1m for the year. That doesn't leave a lot of scope for bad debts, if & when franchisees go bust.
Balance sheet - not madly impressive, but not worrisome either. Net tangible assets are only £8.0m, although it's very much what I think of as an "in & out" balance sheet - i.e. they buy stock, then sell it on in smaller parcels to their franchisees. So they just have continuously rotating stock and debtors on the assets side, and trade creditors on the credits side.
The current ratio looks a bit weak to me, at only 1.0, so this could mean that the company is not able to negotiate early payment discounts from suppliers - which could be a material benefit for a high turnover, low margin business like this. So there is a good case for them strengthening their balance sheet with an equity raise.
Reverse takeover - details are scarce at the moment, but the target company is a drinks wholesaler called Matthew Clark (Holdings) Ltd. Thanks to Companies House now giving completely free access to data on their website (a wonderful development!), I've had a quick look at the accounts of MCH, and it's over double the size of CVR.
MCH's latest accounts show turnover £811.2m, and an operating profit of £18.0m, for the year ended 28 Feb 2015. It has a sound balance sheet (better than CVR's!) so this is clearly not a distressed sale. There would be obvious benefits from combining the two businesses, with increased negotiating power for purchasing, so it looks a sensible deal to me, depending on the price to be paid.
I can't see anything in the results statement today about the proposed acquisition of MCH, and since that will dramatically increase the size of the group, I'll hold fire on any further comments until the prospectus has been published. Clearly there will have to be a substantial equity fundraising, since CVR doesn't have the firepower to buy MCH from its existing resources, and it would be crazy to try to buy it using debt.
I have to leave it there for today, as am returning to Hove from London, due to seeing the dentist tomorrow - one of my molars disintegrated last week, so needs fixing. Therefore tomorrow's report will be earlier, but a bit shorter than usual.
Regards, Paul.
(of the companies mentioned today, Paul has no long or short positions. A fund management company with which Paul is associated may hold positions in companies mentioned.
NB. These reports are only Paul's personal opinions, and are never financial advice nor recommendations. We urge readers to do your own research, and not rely on Paul's opinions).
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

15 comments
Thanks Paul. Assuming an equity raise is required, what usually determines whether its a placing or rights issue?
From what I know, PI's can usually take part in a rights issue, but less often the case with placings.
Cheers, Mark
I suspect QE has damaged your wealth much more.
This Greek malaka has cost me a lot of money. I closed down a number of long positions over the past 4 weeks to reduce my portfolio risk, Sprue Aegis (LON:SPRP) being one of them.,
Grrrr...exit
Paul, thanks for Sprue Aegis (LON:SPRP) review. In early June they said they " results for 2015 to be line with market expectation. " Now about 6 weeks later they are saying "significantly ahead of market expectations", confusing or what? I did think about buying some more at 260p but was put off by their statement and Paul's views.
Hi Herbie47,
Yes you're right, that it's unusual for Sprue Aegis (LON:SPRP) to have said in line with market expectations just 6 weeks ago, and now saying significantly ahead. So they've obviously landed some big contracts from France in the last few weeks.
As mentioned above, I wasn't bearish on SPRP, in fact I said in June that I saw 10-20% upside on the share price. So not clear why that put you off the company!?
Regards, Paul.
Thanks Paul, Well it was not just that 10-20% upside but some of the other comments, "So clearly the company has traded very strongly in H1, but drops a bit of a bombshell by saying H2 will go backwards. Why? No explanation is given." I think there was a lot of talk about France legal requirement being a one-off and distorting the 2015 trading.
I'm not blaming you in any way, we just work on the information available. It just looked like at the AGM things were either flat or going backwards. So in my opinion the shares were a hold not a buy.
Yes maybe they have had some recent new contracts/orders.
Morning Paul any thoughts on the Conviviality figures this morning and the potetial reverse take over annouced late last week of Matthew Clark.
Seems like a decent price - £200m for a company recently reporting PBIT of £20m
CVR's balance sheet looks weak to me, with the potential need to riase another £200m from shareholders. Twice the current MCAP.
I'm a small holder here and so would be interested in your views.
Cheers, Mark
Morning Paul, I see Sprue Aegis (LON:SPRP) has a trading statement today. Looks pretty good "the Board expects Sprue's results for the year ending 31 December 2015 to be significantly ahead of market expectations"
Herbie, this article from Wall Street Journal is rather more instructive about pensions in Greece:
http://blogs.wsj.com/brussels/2015/02/27/greeces-pension-system-isnt-that-generous-after-all/
As for the bailouts, they were very largely exercises in bailing out German and French banks and allowing them to get off scot-free from the consequences of their poor judgement and bad business decisions. About 90% of the funds from those bailouts went straight back out of Greece to those banks. It was the Greek equivalent of the UK taxpayer being landed with the bill for the mistakes of RBS, Lloyds, Northern Rock, etc, etc.
In 2009 the average Greek state pension was Euro 1,350 per month. Considering the cost of living in Greece compared to the UK, I wish my state pension was that high. Many proffessions like hairdressing are classed as hazourdeous so women can retire at 50. End of the day they can't afford it. The bailouts in the UK went straight to the banks as well? We had years of austerity, we have changed, still long way to go yet but slowing we are recovering.
Hi Jane,
Many thanks for the WSJ article on pensions in Greece.
It's striking how, even after all those adjustments, Greece is still spending far too much on pensions.
That is the fundamental problem with Greece - it's a poor country which has been masquerading as rich for the last couple of decades, and expecting creditors to fund its expensive lifestyle. The party's over now, and they will just have to accept a much lower standard of living.
Regards, Paul.
That article is skipping on the broader picture: pensions are a larger part of the welfare system in Greece than elsewhere as there's very little unemployment benefit, income support, etc. So people end up using early retirement or having entire poor households live off granny's pension to a greater extent than elsewhere. So even if abusing the pension system that way is a bit messed up and it would be good to tidy it up, the total welfare bill is likely nothing special compared to other European countries.
Also a country can't be treated as if it was one person. While the profligacy of the past was relatively widely spread, you can guess who benefited the most. The guys who are sent the bill now -- the poor and the lower middle class -- are getting a much larger share of the bill than is really fair. Should people really pay for their neighbours' or parents' misdeeds?
As for expecting creditors to fund their lifestyle: first, they have a balanced budget and are not asking for any new net credit, the debate is only on who should pay for the errors of the past and how much. Second, nobody was forced to lend to Greece, and looking at the place's credit history what happened wasn't exactly a surprise. You can't really argue that irresponsible lenders should never lose any money, can you?
Re. M&A activities. Not surprisingly as the chart below shows the M&A hot sector is by far Technology, Media and Telecomms (TMT) followed by Pharmaceuticals. Perhaps a bit of focus where we should be looking for the next potential targets.
But if you give countries easy loans, would they change? Greece has had 2 bailouts already. Their pensions in 2012 were 17.5% of GDP. Greece needs to change.
Cannot help but wonder if there's some suitable US based company for whom buying IND would make sense at this point ? if they had a good brand in the market in the US but could use some of their by all accounts good high end products wouldn't this be a match made in heaven ? Not that I know enough about the us comptetitors to know if there's anyone suitable in the market I must admit,
Good news that a Grexit has been averted, (hopefully), the EU haven't covered themselves with glory here, a bit more compassion for the greek people wouldn't have gone amiss. Although I appreciate that if they did too much Spain, portugal, italy and ireland would be knocking on their door tomorrow. Clearly a warning shot to the public that they can vote for anti austerity parties but they won't get it. I can't help but feel that a less austerity approach might have been better for europe. I remember deep in the crisis suggesting that the ecb just print a trillion euros, put it in a fund to lend to countries over a range of maturity dates at low interest rates to allow european countries to refinance and limit the cost of their debt burden perhaps with part of the coupon repaying the capital. Not sure that austerity has really worked where it's just caused a deeper and deeper recession such as in Greece.