Small Cap Value Report (13 Nov 2015) - DX., SGI, CGS

Good morning!
I was just thinking how it was unusual not to see any profit warnings today, as they seem to be coming thick and fast on most days - which makes me nervous, given the high valuations a lot of small caps are currently rated at.
Then out pops a profit warning at 10:51 today;
DX (Group) (LON:DX.)
Share price: 42.25p (down 50% - but moving fast)
No. shares: 200.5m
Market cap: £84.7m
(at the time of writing this section I did not hold any shares in DX.. However, when they dropped further in price, I bought some - as explained below)
Profit warning - this is a courier firm, which floated in Feb 2014. It has looked an attractive value share for a while, with a PER and divi yield both around 7. However, things are cheap for a reason, and in this case I've kept away from it because the operating margin looked suspiciously high, given that it operates in a highly competitive sector. High margins don't usually last long, as competitors chip away at them.
So what's gone wrong? The company says that trading patterns in H1 have deteriorated. In this case, its financial year end is 30 June, so H1 is Jul-Dec inclusive.
In particular, the DX Exchange operation is experiencing a higher than expected level of volume erosion and there have been increased cost base pressures, mainly arising from driver resourcing issues (where there is an industry wide shortage). In addition, the new business pipeline in our parcels operation, while healthy, is converting more slowly. This means that while revenues for the first four months are 5.3% down against the prior period, the Board now expects that profits will be significantly below current market forecasts. The balance sheet remains robust, with low levels of net debt (30 June 2015: £1.8m). The Board anticipates the dividend payout for the full year to amount to 2.5p per share.
So to summarise;
- Volumes declining at DX Exchange faster than expected
- Higher cost of employing lorry/van drivers (due to industry shortage)
- Parcels - new business pipeline converting more slowly
- Revenues down 5.3% Jul-Oct 2015
- Profits significantly below market forecasts
- Dividend being slashed from 6.1p expected, to 2.5p
That's pretty bad, which the market has reflected by halving the value of the shares in the last 20 minutes. Dividend seekers in particular will be gutted by the slashing of the divis - it just goes to show that chasing a high dividend yield can be dangerous, as they are often unsustainable.
My opinion - I've questioned here before how this courier manages to make an 8.5% operating profit margin, when others in the sector struggle to make any profit at all? It could only mean that they have some particularly lucrative contracts, almost certainly the DX Exchange (used by lawyers, and similar, but it's in long-term structural decline as email increasingly replaces it for sending documents).
The slashing of the dividend by more than half removes a key support for the shares, and personally I remain reluctant to get involved in what seems to be a declining business. Bear in mind also that there is very heavy capex in the pipeline of £35m, as a new Midlands 44 acre distribution site is opened. So it looks like the company is conserving cash for that, by reducing the divis.
Overall, I think it's wise to value this company by theoretically reducing its margin from 8.5% to say 3.0%, which is probably a more sensible, sustainable level of profitability. For now though, with the shares in freefall, it's probably best for me to sit on the sidelines and wait a few weeks to see where the price settles.
Bad luck to holders here. As always though, if it looks too good to be true, then there's probably something wrong, lurking underneath. In this case, the problem is clearly that profits were unsustainably high. Reasonableness-checking a company's profit margin against the sector is always a good idea.
EDIT: I couldn't resist the falling knife at 36p, and have bought a few, about 20 minutes after writing the above article. I didn't expect it to fall this low, and think there might be an opportunity for a trade, on a bounce to say 50p, possibly?
EDIT2: Just doubled up at 31p. Fingers crossed. I don't think it's anywhere near going bust, so the fall this morning looks overdone now.
EDIT3: Hmmm, well as usual, my falling knife catching has not gone well, so far. What has been staggering, with DX Group now closing down 73% on the day, at 23p, is the extremely high volume of shares traded. This must mean some Institution(s) are dumping at any price.
If you look at the list of Institutional shareholders for DX Group, it's like a Who's Who of small cap fund managers. Now of course everyone gets plenty of stocks wrong, it's par for the course. But I've been flagging for a long time that DX's profits looked unsustainable. How come none of these fund managers thought about that? It really makes you wonder what due diligence do they actually do?
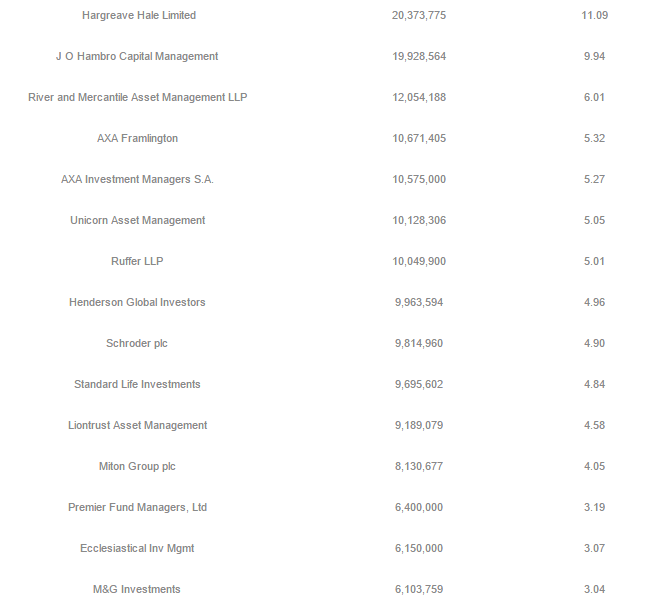
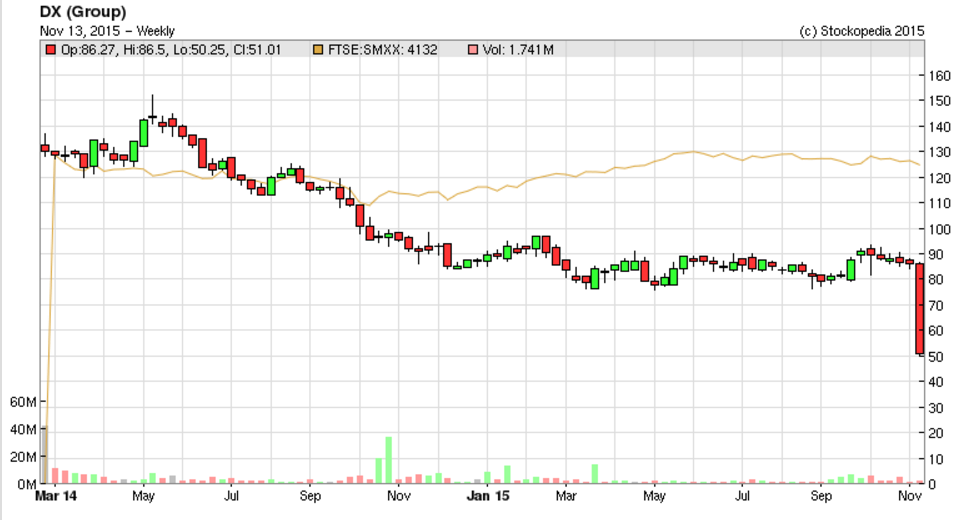
With all the excitement going on with DX (Group) (LON:DX.) I haven't even got round to looking at Stanley Gibbons (LON:SGI) next, which has been on my to do list all morning. I'm astounded that DX has fallen as much as it has - there must be Institutions dumping positions - 19m shares traded today at the time of writing, that's almost 10% of the shares in issue, and that total will go higher. So there will no doubt be some RNSs updating on >3% holder positions.
EDIT: at the close of the day, 53.4m shares had traded, of 200.5m in total issued.
DX is yet another example of Private Equity selling a pup to the stock market. Their IPOs really do have to be treated with the utmost suspicion, in my view.
Stanley Gibbons (LON:SGI)
Share price: 98.5p (down 9.6% today)
No. shares: 47.1m
Market cap: £46.4m
(at the time of writing, I hold a long position in this share - subsequently sold - as explained in the end of this section)
Interim results to 30 Sep 2015 - the market already knew that this collectibles group has been performing poorly, as there were two profit warnings in Sep & Oct. I compared the two profit warnings here on 6 Oct 2015.
Even so, these H1 figures are worse than I was expecting. On 6 Oct the company said that H1 profits would be "substantially below" H1 last year. What the company calls "trading profit" has collapsed, from £6.1m last time in H1, to just £456k this time. This measure of profit doesn't include the £1.1m costs of internet development, nor pension fund costs, or share options. Once you include those costs, the company is loss-making. So a dismal performance.
With my finger now hovering over the sell button, the only things that could stop me selling would be the balance sheet, and the outlook.
Balance sheet - net assets look good, at £81.9m, but once intangibles are written off, then NTAV is £42.8m. That supports 92% of the market cap, so it seems strongly asset backed.
Note also that the balance sheet is dominated by £54.9m of inventories (of collectibles), which are in the books at cost. The big question is, whether there is good upside on that cost, when these items are sold?
Note that there is a £6.0m pension fund deficit.
A concern is that debt has shot up - with a £6.8m bank overdraft, plus an £10.3m in loans. This concerns me. If the bank gets jittery, then they could force a fire sale of stock at below book cost. Net debt of £17.0m is therefore a worry.
Outlook - this sounds altogether more positive;
The Board expects that the Group will deliver materially higher revenue and profit in the second half of the financial year than in the first half, partially assisted by this year's auction calendar being more heavily weighted towards the second half. The Group also continues to work on a number of initiatives with the aim of delivering substantial sales from our sizeable stockholding of rare collectibles, particularly philatelic.
Following the completion of the integration and rationalisation of recent acquisitions, the Group expects to benefit from a reduced fixed cost base and better cross selling of products and services across our customer base in the second half.
My opinion - this is a finely balanced situation. I can see how, with patience, the shares might recover. Set against that, H1 was a lot worse than I expected, and questions have to be asked about management competence here.
Support from divis is falling away, as the interim divi has been passed.
Overall, I'm not comfortable with this one any more, so have decided to ditch my small position for a small loss (it was a recent purchase). I can see the case for holding on, but there are other fish to fry, so it's not for me any more.
Castings (LON:CGS)
Share price: 460p (down 2.6% today)
No. shares: 43.6m
Market cap: £200.6m
Interim results to 30 Sep 2015 - it's always such a pleasure, and so quick, to review results from this UK engineering company. No adjustments, no highlighted items, just crystal clear numbers.
Also, the narrative is just a few bullet points. This is the full narrative (excluding legal disclaimers) below;
Sales for the six months ended 30 September 2015 were £65.0m (2014 - £63.6m) with profit before tax of £9.51m (2014 - £8.34m). Sales revenue has been affected by the general reduction in raw material prices during the period making it difficult to directly compare to the previous year.
It was reported at the Annual General Meeting in August that sales volumes were maintaining at reasonable levels. It appears for the next three months that orders and schedules will remain at a similar level. It is anticipated that the profits for the full year will meet market expectations, unless there is a sudden and unexpected change in the economic climate that would affect the outcome.
An interim dividend of 3.38 pence per share has been declared and will be paid on 4 January 2016 to shareholders who are on the register at 27 November 2015.
Balance sheet - just fantastic! Net assets are £122.5m, all of which are tangible.
Working capital is very strong, with net current assets of £54.7m, and a current ratio of a very strong 3.6 (anything over about 1.5 is good).
There is cash of £31.9m, and no debt.
Overall then, I would say there is at least £40m of surplus capital on the balance sheet, so that's about 20% of the market cap. That provides a big safety buffer, and provides firepower for potential acquisitions.
This is one of the balance sheets out there.
Valuation - in my view, this looks a quality business, at a reasonable price.
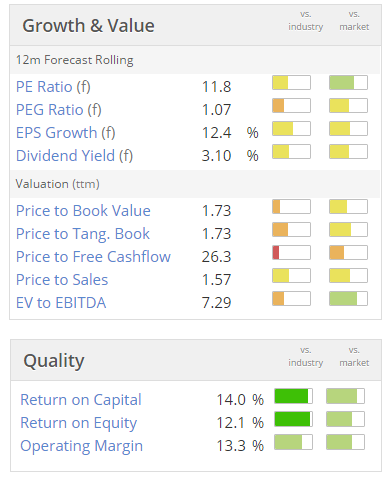
My opinion - I probably should have been buying some of these today, instead of catching falling knives!
My main reservations with Castings is that its profits have been somewhat unpredictable in the past. However, it looks a really solid, traditional company, performing well, with a great balance sheet, at a reasonable price.
Providing profits are sustainable, then it looks a nice company to research and maybe take a position in. There is some exposure to automotive, they make turbochargers I think, so that would need checking. Also currencies might be an issue too.
Well, what an exciting, if rather unprofitable, day!
I hope you enjoy the weekend, and see you back here on Monday.
Regards, Paul.
(of the companies mentioned today, I have a long position in DX., and no short positions.
A fund management company with which I am associated may also hold positions in companies mentioned.
I get so sick of repeating this, but it STILL doesn't seem to sink in with a few people - read my lips - I DO NOT GIVE ADVICE OR RECOMMENDATIONS ON STOCKS! The whole point is that readers are meant to make up your own minds! These reports are purely my personal opinions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

71 comments
Hi Paul, how did you manage the DX. knife in the end? Are you still holding?
Hi Lavinit.
I concur with your assessment. It's as much about psychology as fundamentals at the moment, although the problem with taking the kitchen sink approach is that in the short term the damage done to the company's reputation might be fatal.
I also think that there may be a big overhang in the market of sellers - either original IPO buyers who feel burned who simply want out or short term speculators who expected an immediate bounce and will skip on to the next car crash if they can't make a quick buck here. Accordingly, I think we will see selling into any share price rise for a period of time until the froth has cleared. That seems to have been the pattern over the last couple of days.
As ever, hopefully patience will earn its reward provided we live that long.
Good points gus 1065! I am sounding very spivvy in my comment. Patience is the best thing.
I reactively bought without doing full work but I had done quite a bit of reading in the past so do know the company, along with some comparison to competitors. There seems to have been a lot of selling already and my guess is that the stock should come up quite quickly as the negativity needs to keep up momentum to keep it down here. All this is being said on a small-ish position without proper work! I will try do some soon as might be a chance I should invest properly but my instinct is that I will not be able to work that out without more progress on re-org and understanding of position of document exchange business (which seems as if it can adapt and retain a nice niche market share with decent margin)
I started reading the listing docs for this stock a couple of months ago. I was in no hurry as hunch was that it was likely to drift down and suspicious of PE sellers (looking at other PE seller stocks and waiting for some bad news there too!). The listing docs are pretty clear about the risks - the company has disclosed that document exchange was under pressure and this high margin business likely to erode. Disclosures are also very clear that this is an ongoing turnaround business with quite a lot of work for management to do in terms of integrating acquired businesses and clearing out bits of dead wood.
Sudden erosion and problem is surprising. This leads me to wonder...
...have management kitchen sinked this profit warning? It is known that the industry has driver supply issues so was there really a need to throw in that comment too. Have they just decided to skip the death by a thousand cuts and denial approach? (Note to self look at options and share vesting). Announcing expected 2.5p dividend is a drastic cut...but if its really bad why even bother with that? Either they are rebasing for cash-flow management purposes or they really dumb.
Getting the bad news in aggressively may make sense from a project management perspective with the planned new hub investment. Get the negative vibe in and then out of the way to get round to planning for the future.
My guess is that current stock price reflects a fear of how to finance the new hub and that if they can't then they are forced sellers of the business or they need to scrap new hub (I do not know enough about the business to know whether they can scrap the new hub and have a sensible business.
I bought at 27p and so already feeling some burn. But I think that the balance of probability is a pop up at some point as the news is unlikely to get bad enough quick enough (ie the news needs to be that they can't survive to keep the price down here - its either going much lower or higher).
The interesting thing about DX. is its chart: barring the events of Friday, its share price has been almost completely flat. It has traded in the 80-90p range. Odd, to say they least.
Looking at ADVFN's boards (yes, sometimes they are useful), there's mention of the fact that there is substantial capital spending planned to the tune of £35m. DX has a market cap of £46m and a PE of 2.
Where's the money going to come from? The market? That would be difficult, because the share price is flat on its back. Unless the project can give a return on capital over 50% (1 / PE), which is impossible, that rules out an equity fund-raising. If it does go ahead at current levels, value destruction is pretty much guaranteed.
That leaves bank finance. Will the banks be keen?
It seems it will be an expensive mistake if the whole project is cancelled.
Interesting.
DX does not have a PE of 2x as the level of earnings is precisely what is now in question following the Trading Update on Friday. The 2016 forecast dividend per share was 6.1p according to the consensus data and the Trading Update stated a management expectation of 2.5p - this is a c.60% reduction. However, by itself this may or may not mean that the company sees an earnings reduction of this magnitude given that from the outside it is not possible to gauge what assumptions have been made in the re-basing of the dividend to 2.5p
Naturally a great deal of resentment about yet another PE IPO dropping like a stone within months of being dressed up for sale. In fairness to Stockpedia, their favourable analysis metrics were presumably in good company given the A-list of institutional shareholders that bought and continued to hold the stock until Friday.
Given the huge volume of shares put into play on Friday, it seems clear that many of these same institutions seem to be dumping the stock at any price - hubris perhaps at a profit warning sent out just before a Friday lunchtime at the end of pretty bad week for investors. Together with this huge overhang of shares and the likely (hopefully short term) knee jerk reaction in the wider markets following the terrible events in Paris on Friday, Monday could see this stock tank further..
This said, could it be a good opportunity for new money? Running the various valuation metrics with pretty brutal assumptions, the stock seems well oversold. For example, I ran the DCF model from a base FCF of £18m assuming 0% growth and a 15% discount rate and derived a fair value of just under 60p a share. Looked at another way, the 23p CSP is consistent with a c.40% discount rate. A lot can go wrong with the company as they deal with lower margins and a significant Capex requirement and they've clearly upset a lot of people.
I've taken a small punt late Friday at 24p. May end up looking silly - certainly in the short term - but you've got to kiss a lot of frogs to find your prince/ess.
I think that the stock ranks do pretty much all they can be expected to do, given the circumstances. It seems that bad scores should be heeded. If there's a low Quality score, then you can be pretty sure it's a bad quality business.
I think the same, possibly, with momentum. Although bounces are always possible, terrible momentum is a sign trouble.
Why all the surprise about DX?
The RNS states that it will be reporting reduced profits. That's better than it has done in 3 out of the last 4 years.
...............................................
The surprise is that it had such a high StockRank of 99 when the Stockopedia front page contained red flags such as working capital, current ratio, P/TB, and Altman Z score.
Dendyver,
You might want to read Ed's blog on How to think about high StockRank stocks and specifically the section entitled "Understanding the distress zone"
I hope that helps
Phil
Why all the surprise about DX?
The RNS states that it will be reporting reduced profits. That's better than it has done in 3 out of the last 4 years.
The Stockopedia rankings and screens are simply mechanistic tools, produced through applying determined algorithms to published information. They aren't intended to, they don't (and perhaps can't) second-guess the figures that companies put out, nor can they identify accounting sleight of hand or possible fraud They are simply a starting point to evaluate possible investments and for about only four pounds a week are pretty good value for that purpose, imo. They will almost always need to be complemented with further personal research, Paul Scott's daily reports being a very valuable element in that but even that, also imo, needing to be amplified before an investment decision is made. These mechanistic Stock Ranks perhaps work fine for nine companies out of ten but may sometimes give high readings for dud companies. As one member has posted above, "The annoying thing is if you do research on these shares after the event the blogosphere has pointed out the weakness months before". Yes, of course, that's why the SR fulfil their purpose but are simply a starting point; with respect, the complementary research needs to be done before the event, not afterwards.
Given the amount of debt that DX was carrying for several years under Arle Capital's ownership one can only speculate whether the way the business was being run during this time was for the long term or designed to generate a private equity return through financial engineering. Prior to the IPO management were largely compensated on the basis of a "cash bonus plan created by DX in connection with the improvement of its overall capital structure" i.e. use cash to pay down debt (and there was a lot of it). It seems unlikely that the proposed £35 million new hub would have ever got the go ahead if DX had remained as a private concern.
Arle's total exit at IPO may have signalled something.
I agree with a lot of what the community has posted re the SR format. Quite a number of high SR rated stock have disappeared, gone bust or become disasters lately. The annoying thing is if you do research on these shares after the event the blogosphere has pointed out the weakness months before. Perhaps we should have a blogosphere index? That having been said imagine what is going to happen when the markets collapse! Most of the Aim market will go down down down and if you currently hold one stock that has just bitten back and that is representative of your portfolio you are going to feel a great deal of pain. Might be time to think of real quality unless you are rich and can afford the loss.
I think railing against the failure of SR to pick up what was going to happen at DX is to miss the point. SR's are a pure mechanical system, there's no pretence that they pick up every flaw, or make any guarantee of future performance. All we do know is that portfolios chosen using them have performed well over a fairly short period (2-3 years) and there is apparently a reasonable academic basis for them. But that means that to make specific demands in relation to a single stock is pointless. If you are going to use and mechanical system, such as SRs, (or for that matter any system at all) then you have to use a portfolio approach and accept that the only metric that matters is the overall performance.
That's not to say that we shouldn't all try to learn as much as possible from stocks such as DX that dramatically disappoint, doing so may improve overall performance. However, it must be born in mind that may not follow - changes to screens that eliminate stocks such as DX could also eliminate winners too - quite possibly leaving you with lower overall returns!
Peter
Peter, I think that stockranks is an excellent concept, but any high-ranking companies should also be subject to a common-sense screening:
Will the company be able to grow?
Are its markets in growth or decline?
How much competition is there?
Is the business sustainable in a downturn?
Can margins hold up, and grow?
What issues impact their market and what's the probability of a black swan event in such market?
This is over and above any financial analysis, focusing on the balance sheet etc.
I think that a quick review of DX against these criteria would have warded off most investors from buying. Tbh I haven't really appraised my holdings against such a list. But I'm going to now.
I bought in based on similar criteria: the business plan seems fair enough, even at last week's (already discounted) price. They can grow by being successful in their chosen niche of custom deliveries. This is potentially a growth market, with subdued competition as the other parcel companies concentrate on standard parcels. In the meantime managed decline on the lawyer docs thing provides investment cash flow. Legacy margins probably can't hold up but they don't need to, a say halving of margins being already priced in. There has been no black swan event to speak of at the business level.
Opinions will be divided among value investors on whether it's a good prospect or not, but as such a value methodology will provide no immunity to such price events.
It might turn up to be a great opportunity: after all whatever the fundamental value of the business is, it did not change between 9AM and lunchtime. Only Mr Market's estimate for it moved, and it could well be a tantrum. Looking at the reported trades, it seems the bulk of the price move (from 85 to 50 or so) was based on a post-news auction with a minuscule £30k worth of shares being traded. Then once you get a -30% print, it's quite possible the follow up moves get dominated by non fundamental trading (e.g. stop losses getting triggered, day traders joining in, etc).
Hi all
I hold some DX stock and now have a hole in my trousers, which given what i have since found out rather peeves me.
Two things:
1. How Has SP managed to give this stock a 99 in StockRanks? Of course caveat emptor, Sgt Schultz and all that..... But how the hell has this managed to be an SP 99-er. Problem with the metrics, Ed? I didn't manage to read Paul's earlier health warning before i bought about a month ago. Until today things looked stable and positive. Plus I was out from around 1100 until 1630 when the price cull took place. I am now looking to hire a second brain, or maybe become a split-personality in the afternoons purely for investment purposes
2. Has anyone noted that Ian Pain, CFO of DX diverted just short of a million shares into his wife's name just over a week ago (sorry transferred them for 'nil consideration' -- see company news releases - value c. £576,000). Presumably like Sgt Schultz aka in-the-know-CFO 'he knew nushing'. His LinkedIn profile is quite interesting. Is there a hint of serious accounting manipulation here, as perhaps Paul muses upon? Should the authorities be looking into this further? So in an insolvency and potential company officer enquiry situation, said Mr Pain doesn't own them. Pourquoi?
Answers on a postcard.
Commiserations to all who've suffered as a result of this stock.
To answer your question globetrotter, perhaps rewind 48 hours ...
What issues were there with this stock that one might consider may reduce it's Stockrank ...
1) Balance sheet strength
The stock report has been showing P/TB < 0 for ages and the current ratio has been low too.
However Stockopedia is based on academic research and (I'm sure Ed will correct me on this) perhaps there is no research that supports the argument that balance sheet weakness reduces returns?
2) Quality of management
The metrics used are pulling details from the accounts and if the data is good the score will good.
If 1) is correct and there is no academic research to back up weak balance sheet = negative returns then I have to accept that I can take a huge tumble on any stock regardless of stock rank.
In his SCVR Paul highlighted that the balance was weak ...
"The current ratio of 0.74 looks weak, but that is largely because customers are paying up-front, so it's skewed by deferred income - again, not a concern for such a strongly profitable company with minimal net debt."
Well clearly it's not as profitable as one would have hoped and so that underlying balance sheet weakness has been exposed and the management has been called into question.
Ed has repeatedly stated that high StockRank doesn't equate to cast iron safe investment but rather that research suggests that a basket of high rank QVM stocks will outperform.
For those who want to mitigate balance sheet risk the parameters are there for you ...
Price to Tangible Book (P/TB)
Current Ratio
Altman Score
Now a question for you ... how you measure the trustworthiness of a companies press releases in an objective manner?
Hmmm, just wondering to myself ... what if we could harness the power of the community? What if everyone who has a paid subscription to Stockopedia can upvote or downvote the trustworthiness of a stock. This could help us to highlight stocks such as Naibu, Camkids, Quindell, etc. We could even include a qualitative one-liner from each voter, e.g. CEO has a track record of dubious companies or rock solid balance sheet, strong margins and increasing sales. Perhaps we could choose to make our StockReport 'notes' available for consolidation (not sure whether this should be named or anonymous). This information might be easier to access and be more pithy than trawling though the discussion threads.
Could it be manipulated by an influx of new members upvoting a particular company? I guess that could be monitored?
For me the essence of all of this is either ...
1) Just purely use StockRank to build a basket of high stock rank selections with no extra checks accepting that there is a tradeoff between increased returns and potential losses on an individual stock (however evidence seems to suggest this is greatly reduced with high stockrank)
2) Add (edit) ... [your own] extra checks to StockRank to reduce the risk of losses to an individual stock accepting that this may actually reduce the improved performance of a pure StockRank approach
Best of luck
Phil
DX have an annual subscription model for lawyers and accountants etc. They set an annual charge based on a sample of volumes. They were ramping up the charges each year despite the volumes dropping - email, drop in the housing market after the crash, etc. Eventually practice managers have been catching up with them and getting control of the charges, but there was a lag effect that flattered their revenue line for a while.
Reminds me about my facetiousnees with co-workers about courier services. I sent stuff by DHL when it actually needed to get there, and UPS if I just wanted cheap, and didn't actually care what happened to it. I sometimes sent faulty hardware back to central office, and always used UPS to send it. I didn't care whether they kicked the package all thw way to the destination. In fact, I found the idea of the hardware being irreparably damaged to be a net positive.
A lass at the office said that in a former job she often saw UPS vans unloading the packages. Boxes marked "fragile" often fell off the back, as they shifted during transit.
And don't get my started on City Link, with their fake delivery attempts, and all. Biggest bunch of monkeys imaginable.
DX Group - belongs on the bargepole list. I have a UK Mail holding which has been a disaster although compared to DX Group its now a roaring success. DX Group margin is 8.5% and return on capital 12.3%. UK Mail margin is 4.14% (closer to the norm for this industry) and return on capital is 29%. How are DX getting two and a half times less return on twice the margin? either their assets aren't worth what the balance sheet says they are or they're not being used efficiently. Also, I'm a lawyer. Ten years ago I sent at least twenty items daily via DX. Now I send about five items a year. E-mail has demolished their business.
Recently wanted to buy a portable shaver and walked 2 mins down the road to Argos. Their website / intranet is kind of OK but I didn't manage to make up my mind and buy. Later, at home, I logged onto Amazon and was happy to buy within a couple of minutes. A subjective thing but I doubt the superior physical presence of Argos is enough to compete with the generally slicker presentation of Amazon. We also know Amazon will do anything to get market share so are formidable competitors (so long as their shareholders permit). Possibly Amazon should bid for Home Retail.
Being a Grammar Nazi (and bloody grumpy these days) I always shout at the annoying Argos advert on TV - GO ARGOS.
It should be GO TO ARGOS!!!!
A small thing but it really annoys me
Paul, I think your sentiments are correct - i.e. castings might be a better home for your money than Stanley G or DX - actually the only Stanley that was home for my cash was when there was a casino group called Stanley's in the 1990s!
I've been using the Stocko bubble charts a lot more - as others have said here, a high stocko rank is no guarantee, but it does seem that a lot of my lower quality holdings have been dropping more than the quality stuff.
As for Stanley Gibbons (LON:SGI), as someone said their inventory is worth whatever they say it is - so I would be suspect of their valuation of it and their ability to shift it in any quick time. As for the rest of the business, it's dependent on people selling and buying non-essential luxury items - just maybe we're coming to the end of the cycle when such expenditure is prevalent. if they can't make money in these times, when can they?
I'm having a bad day so I'm going to have a rant!
The CEO of DX (Group) (LON:DX.) stated on the 21st of September : Trading conditions continue to be tough but we are well placed to take advantage of any improvement and we have started the year in a positive manner.
They spoke of efficiency gains and their OneDx programme - They should rename this to the OnePenceDx programme. They seem to be overseeing a massive decimation in the value of the company.
Why release a statement at 10.51 - this is a disgrace. Their AGM was on Monday! What has changed since the board met then and what about those poor people who bought this morning before the announcement. The Aim market is becoming a complete and utter joke in my opinion and it needs cleaning up ASAP - it is unacceptable.
DX (Group) (LON:DX.) /My phone smashed/ and still unemployed...
Pub must be the solution.
Ben
Ben,
I think we can all agree that the way the news was released mid-morning is a total and utter disgrace. These people haven't got a clue how to treat shareholders and so it's no wonder the sell off has been so brutal. It's almost like institutions are getting out at any price and with 25% of the companies shares changing hands in one trading session there should be some interesting holding announcements on Monday. It's been a while since I've seen such a large volume sell off without the whiff of fraud being involved.
All the best, get yourself down the pub! Si
On Stanley Gibbons I would suggest you need to be careful about the valuation of their stock of collectibles, particularly stamps, as the world authority on stamp valuations is -- Stanley Gibbons! I am a sole trader who deals in collectibles and the valuation of stamps can be pretty subjective. I regularly see moderately good stamps selling for 10 to 20% of the SG valuation. This is why I am also wary of their "stamps as investments" part of the business. Ask any professional stamp dealer (other than SG) what they think about collecting stamps for investment purposes and you will see why - but it's a good, educational hobby!
£DX (Group). Not a holder fortunately but does the Stock Rank system need a bit more sophistication as this stock had a very high stock rank (95+) for a number of months and yet falls by 68% (so far today!). I recognise that DYOR is the key but surely there must be some way of flagging up potential danger from the quantitative data - or is just completely unexpected and therefore impossible to predict?
"£DX (Group). Not a holder fortunately but does the Stock Rank system need a bit more sophistication as this stock had a very high stock rank (95+) for a number of months and yet falls by 68% (so far today!). I recognise that DYOR is the key but surely there must be some way of flagging up potential danger from the quantitative data - or is just completely unexpected and therefore impossible to predict?"
At no point have Stockopedia claimed that a high stockrank will prevent you from experiencing significant losses in a share however they do suggest that given a basket of high stock ranks shares you should expect improved returns.
If you want to weed out duffers you could have applied either of Paul Scott's balance sheet checks :
P/TB > 0
Current Ratio > 1.2
DX failed both of these tests.
Caveat emptor
Phil
You said to another poster:
""If you want to weed out duffers you could have applied either of Paul Scott's balance sheet checks :
P/TB > 0
Current Ratio > 1.2
DX failed both of these tests.""
Which misses the point being made. How can this POS still have a quality rank of 86 AFTER close of business today.
The stock reports are computed overnight. In any case quality is a long term backward looking metric which is unlikely to be affected much by a plain profit warning.
"In any case quality is a long term backward looking metric which is unlikely to be affected much by a plain profit warning."
This isn't strictly true
I you read the Stockopedia definition of 'Quality':
"It should be noted that the QualityRank is very specifically designed to be 'predictive' rather than 'descriptive' of future returns."
http://help.stockopedia.com/knowledgebase/articles/182926-how-do-you-calculate-the-quality-rank
Dendyver,
It doesn't miss the point being made. When purchased before today's announcement those screening criteria were correct (as far as the underlying data was correct) as was the StockRank.
The Stockopedia system as a whole is not real time and the data aggregation takes place over night. So tomorrow the ranks will have been adjusted accordingly given the availability of the data. Over the following days as broker estimates feed in to the system the ranks will degrade once again.
So as expected there is a lag in the StockReport. Not ideal but one I accept.
Once again StockRank does in no way indicate the reliability of the future of a particular stock. Ed keeps telling people this but they don't seem to want to listen to it.
I hope that helps
Phil
Because the collapse in SP will be reflected in the stockrank tomorrow, and the change in earnings will filter thorugh once entered by Thompson Reuters.
So, the DX yield is about 7% again! That didn't take long :-)
On SGI, my big concern is that their inventory is not a goldmine of undervalued nuggets which will yield big cash returns, but piles of old tat that isn't worth anything like what they paid for it. If it wasn't, surely they would have turned the stock over by now?
If they can't sell the stuff now, what is it going to be like when the next downturn comes? I can't invest in a business as a value play based on a balance sheet like that.
Divi's approaching 10% based on the current share price.
You got some stick for saying this:
" "£DX (Group). Not a holder fortunately but does the Stock Rank system need a bit more sophistication as this stock had a very high stock rank (95+) for a number of months and yet falls by 68% (so far today!).""
It puzzles me that AFTER the markets closed today The StockRank system has given this POS a 99 out of 100 score
I don't think you were referring to my post Dendyver - as that wasn't what I said in #32.
Paul - in addition to your analysis the Stanley Gibbons (LON:SGI) results are also flattered by a £1.5m credit for Exceptional operating income, the bulk of which is related to a positive legal claim against professional advisers in relation to the defined benefit pension scheme.
Without this, and combined with the other costs they've ignored performance is even worse.
I've taken a small spread bet long on DX (Group) (LON:DX.) Not high conviction but the fall does seem overdone. Lets hope it doesn't turn into another City Link.
Well they did acquire some of the City Link assets...
Re. DX (Group) (LON:DX.) catching a falling knife for any stock is risky enough, but when it is also an AIM stock it borders on lunacy.
No lunacy required to catch falling knives, only padded gloves (aka position limits, diversification).
On Stanley Gibbons I think you made the right call - inventory according to company reports is over 70% in philatelic material they are struggling to sell. Stock always looked overvalued to me and when combined with trading issues - it all looks very messy. I have been a bit of a serial misery on this stock but I know the philatelic market well and have been unconvinced by Gibbons diversification plan.
Paul, I've been inside a private equity being prepared to float. Not a nice experience, lots of skills driven out of the company, strange deals done with distributors/suppliers/customers to offload technical skills which look good in the short term but limit growth opportunities in the future, while the debt leverage is taken to silly level. I watched massive core skills dumped out of our business, the business was finally bought back into an industrial conglomerate who were amazed at how backward and unskilled the business was.
AVOID private equity floats.
The old adage comes to mind to not buy something just because it's cheap.
If the basic product was good and long-term prospects positive, then taking advantage of a collapse in price makes sense. Or if the sum-of-parts valuation is far higher than the share price then it also makes sense.
However the opinion of people who have used the DX (Group) (LON:DX.) product seems to be that it's awful. And terrible service.
There are plenty of other bargains out there...
Hi Paul
If time permits, I'd appreciate any comments about the Stanley Gibbons (LON:SGI) results issued this morning.
Best wishes,
Imran.
From the Trading Update:
"The balance sheet remains robust, with low levels of net debt (30 June 2015: £1.8m)"
I would add about £8m to the net debt figure as the final dividend of 4p per share is payable next Monday (16 November 2015)
Just had a small nibble at DX (Group) (LON:DX.) at 29.64p. Falling knife? Who needs fingers these days anyway? :-)
Best of luck Steve (and Paul). Fall looks overdone, but I'm wary of catching falling knives!
Can I sell you mine? :)
My OH has occasional dealings with DX as she does some work for the Parliamentary and Health Service Ombudsman and the docs (usually a couple of large cardboard boxes) are confidential.
They are pretty useless. - they don't deliver or collect in a timeframe, don't have a web thing that says where the driver is, not responsive on the phone, in fact just did not turn up at all on the arranged day.
As PS said, this is probably a fat margin govt contract, but it will end.
Paul,
Good luck with your trade! Hopefully you'll be every bit as lucky as the person that sold 250,000 a whole 7 minutes before the announcement was released. And it's Friday the 13th... so clearly they didn't walk under any ladders or cross a black cat this morning :-)
Si
A coincidence I am sure...
Yes, must be a coincidence.
As for the fund managers, I looked at that list and thought Paul is spot on with the who's who of Small Cap fund managers.
However, for some companies like Standard Life, we presumably don't know if the holding was by the outstanding Standard Life Smaller Companies trust managed by Harry Nimmo, or if it was held by one of their much more run of the mill funds. Looking at the valuation sheet published by that trust on 30-9-15, DX does not appear.
So I guess it would have been held by another Standard Life manager.
Why do these companies pop out profit warning trading updates during market hours? I feel sorry for anyone who bought in prior to 10.50am and then watched in horror as their holdings plummeted just minutes later.
Paul,
You mentioned on 9th October that you had taken a position in Home Retail (LON:HOME) based on the newly launched same day delivery service and analysis that the shares looked potentially cheap. The shareprice is now a third lower. Do you consider the shares over-sold now or that this price is a buying opportunity based on pre-seasonal nerves in the market on account of the lack of sales visibility?
James
Hi james1n,
Home Retail (LON:HOME) has been my biggest loss this year to date. I've taken a nasty hit on it. I bought a few at around the 150p level, but loaded up much more heavily at 130p, and 110p, so with it now at 98p, it's been a painful loss.
There again, my reason for buying (upside from same day delivery), and the bulletproof balance sheet, where if you treat consumer debt owed to HOME as cash, results in an Enterprise Value of about nil!
So rock solid Bal Sheet underpinnings, but wobbly current trading. So it's definitely one I am sticking with, albeit having timed my entry extremely badly! Such is life.
I'm bracing myself for another profit warning with HOME, as clearly the market thinks that's coming. It's more a medium term thing for me, based on a unique balance sheet that could easily attract a takeover bid, since you could finance a bid for the whole company just by securitising its own consumer credit book, and putting in say £200m of bank loans.
The city forgets about its balance sheet strength every now and then, thus providing good potential upside.
Regards, Paul.
Thanks Paul and Imran for your comments on Home Retail (LON:HOME).
It will be interesting to see how this performs over the all-important Christmas period and given the macro situation should bode well this year with higher employment, salaries increasing faster than inflation at last, continued low fuel prices and falling prices in some retail areas. That said, there are always winners and losers over the Christmas period - it will be interesting to see if Home Retail (LON:HOME) is among those doing well.
I have taken a small position today, but am cautious on it. I think the stock is well underpinned as Paul describes, so lets see!
Good luck James and hope Home Retail (LON:HOME) are able to perform well this xmas.
Hi James
I have a long position and bought in after the interims were published. In hindsight a little too soon, as the price has continued to fall. My rationale for buying in, was the relatively good balance sheet, and their debtor book which they own - so this largely underpins the current valuation. As you say this could be a buying opportunity if they can execute well over Black Friday and the Xmas period.
Just my two cents worth, and Paul may well give you his thoughts.
Regards,
Imran.
I wanted to look at Argos laptops online last Sunday. First I was held in a queue. Then the website became inaccessible for the rest of the afternoon.
What's the use of same day delivery if you cannot take orders?
OUCH!
Indeed! DX was of course an IPO last year by yet another private equity owner. 100p IPO price.
The private equity owners (Arle Capital) seemed to have seen this coming at some point and bailed out totally on the IPO - aggressive IPO structure in terms of the effective sell down (new money to pay off shareholder loans, mezz loans etc to Arle) . Case of buyer beware as Arle had no skin left in the game at that point.
From the Admission Document:
"DX’s existing private equity and institutional shareholders have indicated their desire to exit their investment in the Company
The Company is proposing to raise £185 million by way of a conditional placing by the Company with investors of the Placing Shares at the Placing Price. The Placing Shares will represent approximately 92.26 per cent. of the Enlarged Ordinary Share Capital at Admission. Under the Vendor Placing, the Selling Shareholder has agreed to sell 15,525,300 Vendor Placing Shares at the Placing Price and these shall be placed with investors by Zeus Capital.
The estimated net proceeds of the Placing are approximately £177.25 million and will be used by the Company to repay senior and shareholder debt.
The estimated net proceeds of the Vendor Placing are approximately £15 million, none of which will be payable to the Company."
Company has also not helped itself by not putting this out at 7am - they knew it was coming so should have worked through the night if necessary to have a final version ready to go out first thing.
Hi Paul
my notes from an earlier posting (21/9) of yours:
PS 21/9 a PER of 7.4 and divi yield of 7.4% are very attractive, especially as these results show profits were fairly resilient, and the outlook sounds reasonable. So I'm quite tempted to have a dabble here (81)
Did you dabble?
Thanks Paul. I had a look at this one after your audioboom with David Stredder December last year. You both thought that it would face structural decline. Yes, if all there was to value investing was picking stocks with high dividends and/or high margins, then it would be easy!
Many of the others stocks you talked about on that Podcast have had a much better 12 Months
https://audioboom.com/boos/2749699-part-1-david-stredder-paul-scott-21-dec-2014
Paul,
was waiting for your comment for DX (Group) (LON:DX.) - "Stockopedia computers like it though its at 99!" Goes to show manual intervention is needed
Amen to that!
DX. was on my radar awhile ago, and no doubt on a lot of other people's radar too, given its high stock ranking. I avoided. There was no great insight on my part; after having been slapped by Shoe Zone (LON:SHOE) I decided that companies with less than 5 years listing (esp. on AIM) should be given a miss.
And here we are today.
I've said it before, and I'll say it again: AIM companies need particular caution. Quality scores are open to manipulation.
Another AIM company for the reject pile.
Yes, I have been burned by Shoe and DX, so a proper sucker :). I take as a lesson, not to touch any AIM IPO.
What sort of manual intervention could predict a market tantrum following modestly bad news released mid-morning on a Friday?
(Joined the knife collectors: tripled my existing position at 28.2p)