Small Cap Value Report (14 Apr 2016) - NXR, MTC, LVD, MTEC, RNO, EPWN

Good morning!
In case you haven't seen it, I updated yesterday's report in the evening to look at results from Walker Greenbank (LON:WGB) - an interesting one, as the company was affected by flooding. The insurance payouts look to have comfortably covered all the costs, including business interruption.
I read a fascinating research note from Peel Hunt yesterday, on retailing. Their analysis on that sector in particular is utterly brilliant. Their argument is that there is no such thing as a retailing sector. There are actually diverse businesses at different stages of life. The established businesses are telling us that consumer confidence is weak, demand is low, etc. Yet the economic data says the opposite - consumers are enjoying good increases in disposable income in fact.
So why the disconnect? It's all down to competition - relatively new entrants are eating the lunch of the established players, if they don't keep up with a strong online offering, and constant innovation with products & services.
So you hardly ever see any retailer comment that their products weren't good enough, and that the competition are doing a better job than themselves! Instead they moan about demand being weak, Brexit causing uncertainty (please! How ridiculous), and of course that good old catch all - the weather hasn't been right.
It's all mostly nonsense. The best retailers will do well, regardless of the weather, the economy, or the competition. (e.g. results from Debenhams (LON:DEB) today (at the time of writing, I hold a long position in this share) weren't bad at all - despite them being old school they're just executing well, which is what's needed - "retail is detail").
With living wage set to eat into operating margins as a constant headwind over the next 4 years, it's vital that retailers manage to eke out positive sales momentum, and strong margins. Mind you, over the long-term, rents are likely to absorb some of the pain, but that's a slow process, due to the archaic 5-year upward-only rent review process.
I think there are some stand-out bargains in the sector right now. Being able to buy high quality businesses which generate tons of cash, on PERs of 10-12 is a rare opportunity, in my view. So I reckon the retail sector is a great place to go looking for bargains right now. Although as always, one has to be selective, and put in the hours doing the homework to make sure you pick the right ones.
Norcros (LON:NXR)
Share price: 176.5p (up 3.2% today)
No. shares: 61.0m
Market cap: £107.7m
(at the time of writing, I hold a long position in this share)
Trading update - which covers the year ended 31 Mar 2016.
The key part says:
Group underlying operating profit1 for the year is expected to be marginally ahead of market expectations.
To quantify this, the figure showing on Stockopedia is for normalised EPS of 21.4p - giving a PER of 8.2.
Why so cheap? There are various factors, but the main one seems to be that: it's always been cheap! When a share never seems to gather upward momentum for long, people become bored, and drift away, thus perpetuating the low price with a constant stream of bored sellers.
Net debt really isn't a problem. It has risen to £33m (from £14.2m a year ago), due to acquisition-related payments. I don't see this as an issue, given that it's a relatively modest multiple of EBITDA. Also, Norcros has freehold property, which personally I net off against debt, since if needs be, debt can be de-risked & shunted off balance sheet (for now) by doing a sale & leaseback on freeholds.
South Africa - some shareholders were worried about Norcros's S.African operations, which are material to the group overall. However, today's statement shows them in good health - with LFL sales growth of 15%. This is offset by an equivalent drop in currency, so flat in sterling terms. That's fine, and much better than it could have been.
UK - this is the biggest part of the business, and seems to be struggling a little still - with LFL sales down 2.2% for the year, that's not great.
Acquisitions - several excellent acquisitions have been made - in each case I have checked out the company accounts at Companies House, which now offers this service free.
Norcros has a buy & build strategy, to acquire complementary bathroom fittings companies, then drive sales through its existing international distribution network. This seems to be working well, e.g.
Croydex continued to perform strongly in line with the Board's expectations.
Pension deficit - one of the reasons that Norcros shares remain cheap on a PER basis, is probably due to investor aversion to large pension deficits.
In this case, the pension schemes' gross assets and liabilities are very large - something like 4 times the market cap of the group. So even minor changes in actuarial assumptions can cause big movements in the deficit.
My main worry with this share, was that the pension fund trustees would demand unrealistically high over-payments, thus draining cashflow, and stunting the growth of the host company.
Therefore today's news of a 10-year agreement with the trustees as follows, is reassuring:
The March 2015 triennial actuarial valuation process for the Group's UK defined benefit pension scheme has now been agreed with the Scheme Trustee, and shows a deficit of £73.5m (2012: £61.9m) representing an 84% funding level (2012: 85%). The increased deficit is driven predominantly by historically low gilt yields.
A revised deficit recovery plan has been agreed with the Scheme Trustee, with a cash contribution of £2.5m per annum starting in April 2016, and increasing with CPI, payable over the next 10 years. This compares to a deficit recovery payment of £2.1m in the year to 31 March 2016 under the previous plan.
So a relatively modest increase in payments (up by £0.4m), then inflation increases. That's well within the company's ability to pay, from profits. It should not interfere with dividend payments, nor expansion either. So a good balance looks to have been struck, and we can stop worrying about the pension schemes for the time being.
Actuarial deficits look scary, but they're worked out more conservatively than the usually smaller accounting deficit. The key figure is the cash overpayment, the way I look at things - that's money going out of the door that could otherwise have been paid in divis. So it's c.£2.5m p.a. + CPI here, which is annoying, but not a deal-breaker.
Dividends - nothing is said about divis today, but given that earnings are marginally ahead of expectations, and the pension fund agreement is satisfactory, then the dividend yield of about 3.8% looks safe, and is nice to have whilst we wait seemingly an eternity for the shares to re-rate.
My opinion - if I had known it was going to take so long for this share to go anywhere, then I'd have deployed the funds elsewhere. That said, it's impossible to second-guess these things. Everything seems on track overall, and the buy & build strategy seems to be going well. Therefore EPS will rise, even without any organic growth. This should drag the share price up eventually.
Two worries are removed today - over S.African performance (which we now know is going well), and the pension deficit, where agreement has been reached. So I shall sleep a little sounder knowing this.
Mothercare (LON:MTC)
Share price: 154.5p (down 18.0% today)
No. shares: 170.9m
Market cap: £264.0m
Q4 trading update - the commentary from the CEO doesn't sound too bad at first glance:
"Overall Group underlying profit for FY2016 is within the range of current market expectations. The UK is responding well to our strategy with continued sales growth and improved margins. International continues to be impacted by adverse currency and weakening consumer confidence in some key markets as economic headwinds persist."
The trouble is that Q4 sales in the problematic (and historically most profitable) division seem to have fallen off a cliff, although up against what looks like the last quarter of strong comparatives in the prior year.
Some geographies, e.g. China & Middle East seem to be struggling. The trouble is, this now throws into question the turnaround strategy. In particular, analysts currently forecast a 54% increase in EPS from 2015/16 to 2016/17, which looks questionable now.
Therefore if forecasts are going to be lowered for the new year, then the valuation comes into question - it gets de-rated, hence the 18% fall today.
My Achilles Heel is buying too soon after profit warnings. I had lunch this week with an old friend who pointed out some academic research on profit warnings. It said that you should always sell after a profit warning, because statistically the shares are far more likely to continue falling after the initial fall (notwithstanding a short-term bounce).
The research suggested that we should wait at least 2 weeks before considering a purchase after a profit warning. That rings true to me. So I'm going to take my time on MTC, and do some more detailed work on it over the next few weeks, if I can find the time.
One broker has reduced their FY2017 forecast by 12%, but is saying they see today's weakness as a buying opportunity.
UK trading is doing alright, and it's striking that 35% of UK business is now online.
A few snippets now, as I have to nip back to Hove from London, as I forgot my passport (am off to Warsaw first thing in the morning)
Lavendon (LON:LVD)
(at the time of writing, I hold a long position in this share)
A solid update today. Although note that the hire fleet was increased last year, so increased revenue is to be expected. Lots of detail is given, but overall this is key section:
"Building on the momentum established towards the end of 2015, we have seen an encouraging start to the year with our continued focus on revenue growth delivering results. This growth reflects the benefits of the strategic investment programme we undertook in 2015, to strengthen our market positions across all our regions. Whilst recognising some uncertainty in the economic outlook, the Board remains confident of making further progress during the year and delivering on its expectations for 2016."
That sounds fine to me, especially considering what a low rating this share is on.
It's good to see that the M.East division is holding up - with other countries making up for softening trading in the high margin Saudi Arabian market. Worries about the M.East are probably the main reason that this share is on such a low rating.
It has a very solid balance sheet too - vastly better than say HSS Hire (LON:HSS) .
Matchtech (LON:MTEC)
(at the time of writing, I hold a long position in this share)
I've not had time to go through all the detail, but when time is short, all you really need to do is check that the company says its trading in line with expectations. That's the crux of it all:
Whilst the Board is mindful of the increased caution in economic forecasts in recent months, based on opportunities won, trading in the two months since the half year and continued close cost management the Board anticipates the Group's operational results for the year to 31 July 2016 will be in line with management's expectations.
A bit annoying that they say "management's" instead of "market". I cannot see the reason for this, given that there are market forecasts out there.
This share looks terrific value in my view:
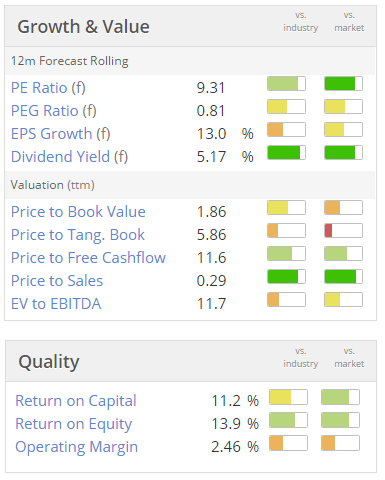
Balance sheet - I was expecting this to look stretched, after taking on debt to acquire Networkers Intl. So what a pleasant surprise to see that it's actually fine - no issues there at all, for me.
The current ratio is strong, and long-term debt looks perfectly manageable.
This share is arguably similar to Norcros - in that it always looks great value, but sellers snuff out any decent rise in share price. Mind you, who cares, if we're collecting in a 5% dividend income whilst we wait for the overhang to clear?
Renold (LON:RNO)
(at the time of writing, I hold a long position in this share)
I reported here on 10 Feb 2016 about Renold's profit warning, concluding that the shares looked good value at 30p.
An update today has given things a boost, with the company seemingly coping well with lower demand:
As a result of the slightly better than expected sales and ongoing cost reductions, the Board now expects that the Group's underlying Adjusted2 Return on Sales3 will be maintained at 8.6%, the same level as the prior year. Adjusted operating profit will therefore be ahead of current market expectations of £13.5m. The benefit to Adjusted Earnings Per Share will be further enhanced by savings in financing costs and the estimated tax rate applicable in the year.
I've commented before how this company seems good at managing investor expectations. So rather than dribbling out bad news, it seems to have cleared the decks in Feb 2016, and is now out-performing against lowered expectations.
I particularly like that the company has maintained profit margins, despite lower sales.
Epwin (LON:EPWN)
Results for 2015, out today, look solid.
Big increase in the divi, up 50%.
It's on a PER of about 12 times 2015 earnings - probably about the right price, I'd say.
Current trading - in line, so that's fine.
Balance sheet - OK-ish. There's a bit more gross debt than I'd like to see, but this seems to be funding quite large fixed assets.
EDIT: an adviser to Epwin has just emailed me to say that debt is high because they made 2 acquisitions late last year for £24m cash.
Sorry, I've run out of time for today, have to jump on a train now to grab my passport from home.
My flight to Poland is first thing tomorrow morning, so my plan is to write tomorrow's report from my hotel room, so you shouldn't notice any difference from usual, assuming my flight is not delayed.
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

49 comments
Worth remembering that Epwin (LON:EPWN) is the main supplier to Entu (UK) (LON:ENTU) so potentially some read-across there (Entu (UK) (LON:ENTU) remains very cheap imo).
I used to hold Entu (UK) (LON:ENTU), yes they look cheap but they have had some problems and profit warnings. I got out because I did not trust the management, just as well because the shares have fallen 43% since I sold. Also Entu (UK) (LON:ENTU) is different from Epwin (LON:EPWN) which I do hold, Entu (UK) (LON:ENTU) is made up of a lot of businesses that were in liquidation or loss making, they bought a large loss maker last year I believe, so the question is can they turn these companies around?
STM.....a big thank you to my various corresponders....much to think about....all very interesting.
Michael.
Re: STM
As I understand it….
QROPS are the only choice some people have when it comes to pension arrangements. They are meant to satisfy the legal requirements of different regulatory systems, which is important for dual nationals, anyone earning in a foreign country and anyone moving permanently to a country with conflicting transfer and taxation arrangements. QROPS were launched as a result of human rights legislation in 2006. The increasing demands of cross border compliance are one of the drivers of STM’s business.
An example: A dual US/UK national living in Britain
Pension providers in the US will not usually open a pension account for a person not living in the US because new regulations require that the provider knows their customer. This is considered too difficult from a regulatory perspective. US citizens living all over the world have found their pensions closed and cashed, with the tax liability this creates immediately payable, unless the scheme is transferable elsewhere.
There are very few onshore banks and almost no onshore brokerages in the UK that will accept US citizens as customers, because of the new FATCA compliance regulations. Onshore pensions providers are not set up for these new and changing matters of compliance.
STM is seeing a huge growth in desperate folk who have suddenly found themselves on the wrong side of changing compliance regimes. It is the reason why STM can charge so much for setting up and administering pension schemes. It is undoubtedly a growth area as more regulations are put in place around the world, although the US is probably driving the increase in STM’s business.
The moral concern relating to the charging of out sized fees for this line of work needs to be tempered by an appreciation for the amount of work needed to harmonize the needs of differing regulatory systems and pure gratefulness that a legal way to hold a pension is provided by for those who find themselves in an awkward position.
As far as the sustainability of profits is concerned, this depends on the ability of various countries to respect the laws and regulations of other countries, and the human rights of individuals.
There are, as always, company specific risks.
I have a modest holding in STM.
That's what the QROPS sellers want people to believe. In practice (I'm in the target demographic) you often have a range of better options (stay put, transfer onshore-to-onshore, and now cash out early). In addition to outsized costs, the punter is also pretty vulnerable with offshore schemes where there's low regulation within the offshore locations, and nobody who cares if your money is lost/stolen. Maybe there are some customers of STM for whom a QROPS is indeed the best solution, but I'd bet most of their customers would be better off without them.
I lived overseas for a good number of years and as I have mentioned before on a previous post, DeVere (who 'sell' the QROPS on behalf of STM (LON:STM) as I understand it) had an awful reputation to the point where the company I worked for (a big international blue chip) banned them from calling and hassling staff although that was more related to them peddling savings plans. Whether DeVere have cleaned up their act in the last few years I don't know but that along is the reason I am staying well clear.
Ah yes, DeVere partners - they had a really bad reputation for a reason. I speak from personally experience of their "services" in Hong Kong.
Atrocious. Putting you into a completely unsuitable product despite specifically saying what you wanted - grace period came and went before I was able to see what they'd put me into. And when I complained I was told it was the equivalent of what I asked for. When clearly it wasn't as having "Cash units" in a Fund, certificated, with withdrawal restrictions, isn't anywhere close to having cash in the bank - available without notice or restriction.
They also failed to mention that their commission was charged on basis on "introductory capital amount" and wouldn't change with the value of the fund. ie If you were going to take withdrawals(and I specified I would be as I was leaving Hong Kong within 6months) then your annual fee would still be same no matter how much your fund reduced in value. You also couldnt close the fund within 7 years of opening, without a 20% penalty, despite my saying I'd be looking to buy a house within 6 months of leaving.
Atrociously dishonest advice.
Wont touch anything from DeVere ever again.
Hi Paul, can you please comment on GYM group since IPO stocks have performed well but, their revenue recognition policy seem to be aggressive please write comment if possible thanks.
What's your view? I took a quick look and it seemed very expensive to me. I like their business though.
They mention number of members 376000 and no of gyms are 74 if you divide that number that means roughly around 5000 member per gym enough to fill and music concert then if you multiply 376 to 16 pounds a month times 12 give me around 72 million and their revenue is around 60 million this year see to me like every one joined gym paying money on time and not cancelling their membership ever. I could be wrong but if you have any justification please tell me.
Thanks
One more thing16 pounds a month is their monthly fee with no contract and as promotion in my area they are giving it for 12 pounds a month.
Thank you, Paul (your note 30 re STM).
What an interesting, no sorry challenging, game we play each day. We DYOR in depth as is necessary, come up with ticks in all the right places and still get shot down with a contrary market sentiment which we neither understand, nor often agree with.
I suppose this is why we continue to sit in front of our screen each day looking forward to your SCVR.
I shall persevere with STM and hope to see a turn for the better - at least for a while.
Re STM
Did you read the letter from the chairman of the remuneration committee (hinted at in the RNS)?
A Value Creation Plan (VCP) is being proposed - this is `new' news (as opposed to general offshore tax haven newsflow, which has been around for a week or two) so perhaps this prompted the selling?
The performance threshold is 60p, which is lower than the price has been this year, though higher than the 30.5p in March 2015 (cited in the chairman's letter)
Interesting comments, thanks.
Another thing to consider with Next (LON:NXT) is that the company had a rather, in my view, manipulative policy of managing up the share price with share buybacks, and publishing a range of prices they would buy at.
OK, it's hindsight, but that policy was likely to take the shares to an over-valuation, and then when it broke, it's a bit like a currency devaluation, once the central bank can't stop the tide any more - a big gap down.
That's fine for me - I don't care what shenanigans went on in the past, I just look at the shares now, and think - hmmm that's good enough value to tempt me to buy.
I'd much rather buy them now at £55 than at £80 a few months ago when everyone was complacent.
Regards, Paul.
Thank you, Herbie 47 (Post 21).Yes, the fall is 8%, cruel isn't it.. One trade alone around 4pm was for 60,000 shares.
I wonder what's going on.
Michael.
Paul, good evening. You reported on STM on the 1st March and were impressed with their balance sheet and the return of the dividend. Their results were published yesterday confirming your view on the accounts.
I was surprised therefore to see heavy trading in the shares today, particularly late afternoon, culminating in a 4% drop to 46.8p.
Are any of your correspondents able to throw light on the continuing fall in the share price. I have held shares for some time now and have been reluctant to sell hoping that the results would encourage a re-rating.
Michael
I was wondering the same. Think you will find they are down 8% not 4%. Had a look on a bulliten board but can't see anything. I think its a very illiquid share so a few sales and the price will drop considerably, I know its very hard to buy and sell shares in it.
Could it be that STM are associated with Offshore Pensions and that the word Offshore has become a dirty word associated with fear that there will be some undefined clampdown on companies involved in the offshore sector? Just a thought - I too am holding and scratching my head.
Maybe their offshore focus has given rise to some irrational selling. Perhaps throwing up a buying opportunity?
Could it be that pension freedoms make (some? most?) QROPS obsolete? Also more people might find that the career/reputational risk of offshore arrangements are not worth the often meagre benefits. The push towards stricter compliance may increase their costs (if so, will they be able to pass them to existing customers?).
Incorrect posting
Shareholdings were different
CF Miton UK Smaller Companies and Miton UK Microcap Trust
Forgive the error.
Hi Michael,
I assume that STM (LON:STM) has probably been dropping on sentiment connected with the whole offshore, tax haven stuff going on at the moment?
QROPs are not really related to that particularly, but people sell first & ask questions later.
Overall, even though I hold some STM, it's not one that I have any real conviction on, and I won't be increasing my existing small position in it. Something doesn't feel right about it.
Regards, Paul.
I quite liked the look of STM as I thought they were purely in the business of administration. Then I looked at the annual report and in note 9 they have their own life assurance business where they are writing £130M odd of premiums and mention assets of £160m odd and the corresponding liabilities.
I would have a stab at valuing the company based on the admin side but I would not have a clue where to start with these sorts of numbers and whether they are in a healthy position or otherwise so I have walked away.
http://www.stmgroupplc.com/annual_report/2015/pdf/2015ar.pdf
Hi Paul
Re NXR, I still wonder if the pension is a massive potential black hole. Obviously, as you describe, NXR have come to an arrangement with the trustees that both parties to the deal can live with in terms of ongoing contrbutions. However, is the pension situation accurately described in the accounts or not?
When Ensor (ESR) wanted to buy an insurance policy to cover their pension obligations as part of their efforts to liquidate all the companies within the group, it ended up costing them about twice the deficit that was quoted in the accounts. I also understand that had they waited to buy the insurance policy at a later date, legal changes would have made it significantly more expensive. I do wonder what the equivalent situation would be at NXR albeit I have no knowledge of the detail.
Disclosure: I am still holding ESR but have not had a position in NXR for the last couple of years.
Regards, Martin
Paul,
I like Lavendon (LON:LVD) too and there was a positive write up about their business in Sunday's Midas Daily Mail prior to today's update. The article addressed the M. East situation saying.......
...And in the Middle East, Lavendon increased its revenues by 7%, with growth in the UAE, Kuwait, Qatar and Oman offsetting a decline in Saudi Arabia. The Middle East is extremely profitable for Lavendon, too, and the long-term outlook is good. Qatar alone has a £95 billion infrastructure programme over the next few years, of which the World Cup accounts for just £2 billion. Across the region, there are extensive construction plans and a growing realisation that powered access equipment can be safer and more productive than ladders and scaffolding
I believe its good value even after today's rise and I hold a small long position. Ian
http://www.dailymail.co.uk/money/investing/article...
The issue for retailers is not simply competition with newer retailers. In my local high street many of the retailers are being replaced by providers of services for whom retail premises are a cheaper alternative to their (often) traditional residential property-based locations eg chiropractors, barbers, beauticians, showroom-based furiture suppliers etc. In addition more money and time is going on online purchases both experiential (such as gaming) as well as retail. People spending time online (or watching sports) aren't in shops. Women's sports are growing fast and must be competing with retailers for customers attention.
Absolutely. And mass uncontrolled migration certainly isn't helping
Well I am quite surprised that anyone in this country thought that we would be unaffected by rising world population just because our own fertility was falling. This growth is occurring largely in dysfunctional states which cannot give any viable future to their populations. What did we think these people were going to do ? - sit at home and quietly wait for an early death or get up and go to those places that they see on the internet (yep - the internet is everywhere ) or hear rumours about. This is just another facet of Globalisation surely ? I defy any government to slow the steady stream.
My point is that downward pressure on real wages and standards of living will be with us for generations.
Matchtech do make you want to yawn though dont they? Instead of one boring company they now have two steady and boring companies wrapped into one. I understand all the plus points, but the IT section does really seem to be a bummer at the moment and dragging down the rest. I hadn't understood that the IT section of other providers was slowing or down? Have I missed something and this section is in the doldrums or is the comment in today's report correct in that the difference between engineering and IT is becoming blurred (if I read it correctly?)
Ridavies
the IT sector is doing well, but I spoke to the directors of SCISYS (LON:SSY) recently and they said that recruitment is difficult because there is a serious shortage of experienced IT staff (especially in hot areas such as cybersecurity). The gap is filled by bringing staff from other EU countries, so let's hope that this remains an easy option.
To be fair, there is a growing 5%+ yield and they also paid down the debt pile by £8m. Carry on like that and they'll be net cash in under 3 years. That's a good corporate performance.
No idea when but this will shoot up at some point (or get taken out).
Hello Paul from a firm supporter and avid reader of yours.
You say there are lots of bargain retailers out there. Would you care to comment on which, though some we could guess. I am not asking for recommendations you understand, just opinions on the stocks you would be likely to look very closely at at the moment, and perhaps even buy or add to your current holdings?
"There's a massive divide between the say over-50s, who are mostly sitting pretty, and younger people who are in a hopeless position - saddled with student debt, lowish wages, and unable to ever afford to buy a house, until their 50's, once they inherit parental wealth. Something has gone badly wrong."
Absolutely. And mass uncontrolled migration certainly isn't helping.
The old contract of "Work hard,get paid a reasonable amount, save, and you'll be able to buy your house in 30's" has been well and truly broken. Hollowing out of middle Class,much as a result of technology advances, and, in general compression of wages for most means many will never be able to afford their own house. This is morally wrong in my opinion. No wonder so many despair and don;t bother saving - what's the point - Renters are in such a difficult position but what to do.
Mass migratory flows of 330,000 per annum simply isn't sustainable and merely compounds the problem.
The waning of PPI(Didn't realise it had been that significant to be honest), the increasing use of Credit card debt,and early use of pensions certainly bodes ill. It's not as if we can fall back on country;s finances - they're in equally dire straits. all rather depressing for those sub 40,unless they're in a high paid job - City, Law, Doctor, or Politician.
Certainly is time for a change on many fronts.
Paul, thanks for your extremely helpful articles.
You say that those established retailers complaining about weak consumer confidence are really just suffering from competition. Next made a comment in their recent results that "In addition to our generally more cautious outlook for the economy, we also believe that there may be a cyclical move away from spending on clothing ...". The share price collapsed and hasn't recovered, presumably because of these comments. Yet you have mentioned that you are very positive on Next and have bought heavily. Are you still of this view and if so how does that tally with your comments today? I would appreciate your comments..
Hi dgold,
I do indeed hold Next (LON:NXT), having bought at about £56 after the profit warning.
In my view, the narrative from Next was unduly negative, and the shares look smashing value now - on a PER basis, but also on a yield + buybacks basis.
There is this argument whether we have reached "peak stuff", and that possibly people want to spend more on experiences, eating out, pubs, holidays, etc.
My view is there could be some merit in it. Although I also remember patches in my days at Pilot where there just weren't any major fashion trends. This led to a fallow period where sales were down.
Then some new trend would emerge, and sales went back up to normal.
For this reason, I'm banking on this spring/summer season being potentially quite a good one for fashion retailers. I firmly feel that the gloom is overdone, and being able to buy some great companies at a 30% or more discount to where the shares were 4 or 5 months ago, could be a really good opportunity.
Regards, Paul.
I don't think it was a profit warning, just a negative outlook, which they have seem to have done before. If Next (LON:NXT) have bad sales then that will go for most other high street retailers, so why have NXT gone down so much and others have not? Actually looking at NXT figures they did come in at the top the forecast. I agree the outlook seems overdone but better than promising too much. I don't feel the high street is anything like 2008, yes its competitive and some are not doing so well. But who knows with women.
Paul. thanks for your reply. I am wondering though - why in the case of Next do you give them the benefit of the doubt whereas in your original comments you are very cynical about retailers who try to blame problems on external factors?
Hi dgold,
I suppose it'e because Next (LON:NXT) has a history of gloomy outlook comments, and then doing better than people expect. It's all really down to valuation. The numbers look so attractive to me with Next, and the quality of the business so good (look at the operating margin!), that it just works for me as an investment, at this level. It's not something I want to hold forever - more of a trade on it looking oversold. Same with a couple of the others below.
Other retailers I'm currently in: Debenhams (LON:DEB) , Poundland (LON:PLND), French Connection (LON:FCCN), Boohoo.Com (LON:BOO), Laura Ashley Holdings (LON:ALY), Restaurant (LON:RTN), Enterprise Inns (LON:ETI), MySale (LON:MYSL)
I might possibly buy some Mothercare (LON:MTC) at some point, but no rush there. Carpetright (LON:CPR) is also on my possibles list. There are plenty of reasonably-priced retailers to choose from right now. Potentially rich pickings, if we select the right ones!
Regards, Paul.
Paul, thanks for clarifying. Your comments are always interesting and helpful.
Best wishes
Another one to consider is Ted Baker (LON:TED), shares are down about 30% from peak, profits were good, up 20% and forecasts are quite positive, its similar to Next (LON:NXT), quality, well managed. Its on my radar now.
I'm a holder of Next. Retailers like to blame the weather for underperformance. Fine, but when the weather was good for retailers, what happened? Every other retailer said it was their genius that caused bumper profits. Next said the weather was incredibly helpful and next year's comparables would be difficult. They still managed to beat them, while others fell by the wayside.
Honesty and transparency works in good times and bad.
"The established businesses are telling us that consumer confidence is weak, demand is low, etc.Yet the economic data says the opposite - consumers are enjoying good increases in disposable income in fact."
Interesting conundrum.
I'd say Consumer confidence is weak due to wages going nowhere over the last 5 years+ in conjunction with far lower job security( much down to the import of mass cheap labour)
People can't spend if they aren't earning, or see their pay fall - wages have been compressed considerably over the period such that any recent rises in disposable income being trumpeted have made little dent currently in people's lower standards of living.
Middle Class has been hollowed out as well...
Presumably much "spending" is debt financed which is hardly sustainable.
Brexit will indeed be used as an excuse for any slow down..disingenuously so.
Great commentary on Norcros btw
Thanks Fangorn.
Another interesting point from the Peel Hunt note, is that PPI payments have given consumer spending a considerable boost in recent years - something like 1.5% of discretionary spending has been financed by them, and whilst now on the wane, it's still a useful boost to consumer spending.
Also, pension drawdown is reckoned to have helped somewhat - mainly for big ticket items like holidays & home improvements.
The disposable income figures in the Peel Hunt note are quite striking actually - the average household has actually seen decent increases over the last few years. Although they base that on people with mortgages. I think renters are having a much harder time, as it's generally a much bigger proportion of their salary than people who are established with a relatively small mortgage on a very low interest rate. Who of course are enjoying wonderful disposable incomes right now.
There's a massive divide between the say over-50s, who are mostly sitting pretty, and younger people who are in a hopeless position - saddled with student debt, lowish wages, and unable to ever afford to buy a house, until their 50's, once they inherit parental wealth. Something has gone badly wrong. Mind you, people adapt.
Regards, Paul.
Yes but they choose to go to university, so they can earn more money, or just to have a great time not working? Years ago less people went to university, those that did often worked part time or in holidays. I blame Labour for a lot of this encouraging them to go to university and giving them all night drinking. Wages are low but tax now is lower, is it £11,000 now before you pay any income tax plus £5,000 tax free for savings. Its always been hard buying a house I remember in the 80s, interest rates went up from 10% to 15% soon after I bought my first house.
I'd prefer to pay much higher interest rates on a much smaller loan. Yes interest rates are low now, but house prices are such that there is no chance of the principal ever being paid off.
About 10 days before Labour came to power in 1997, I as a single, recent grad, bought a reasonable 2 bed house in the South of England for less than 3x my salary.
There are very few places in the UK where that is even remotely possible now. Neither can you expect to take out a mortgage and expect wage inflation to eat away at it.
The idea that the young today are feckless idiots and the older generation were hard working, driven go-getters just ignores how much the older generation are completely screwing their kids and grandchildrens generations.
You must have been on a good salary, average UK house price was about £60k. When I bought mine in 1984 it was about 5x my salary. You were lucky as house prices had not gone up in real terms for the previous 10 years. Problem is there is too much credit now.
I did not say that about young but I know quite a few students I know what they get upto and things have changed. How are the older generation screwing their kids?
It wasn't a particularly good salary, no. In fact it was quite poor in comparison to graduate salaries at other companies, which was why I was offered £5K extra to stay when I resigned just over a year later. Average price might have been 60K, but 2 bed terraces are usually a bit below average. I wouldn't describe my situation as lucky. I'd say it's a damning indictment of our society that being able to secure modest shelter without being in hock to banks for the rest of your life is seen as being somehow unusual. Of course I've also been screwed over by rising house prices as the rungs of the "ladder" moved further and further apart.
As for the older generation screwing their kids. One look at the national debt ought to do that. Who ran it up? Who is going to be paying it off? You can also look at pension provision, job security, student debt and of course house prices.
I see. I thought as in South East of England house prices would be higher than national average but depends where you live, even moving 1 mile can make a massive difference as I know. By lucky I meant you were buying at the end of a 10 year period when prices had not risen in real terms. I see now that houses are still some way below the 2007 prices in real terms.
I really don't think you can blame the older generation for what a Labour party did to this country, yes we will all have to pay, and was it not them that wrecked pensions. A lot of debt was also due to lack government over investing by banks in US bonds, I don't think that has anything to do with the average person. House prices are down to supply and demand and interest rates. I can't really see what it has to do with the over 50s?
Good morning Paul, I think you will cover Epwin (LON:EPWN) later but their results today don't look good to me, EPS forecast was +20%, actual is negative, maybe theres a reason?
Matchtech (LON:MTEC) is looking good, hopefully share price will return to last years level soon.
Lavendon (LON:LVD) look ok but debt has gone up, not keen on their exposure to any downturn.
Paul, any views on Poundland? A retailer, perhaps slightly bigger than the market caps your normally deal with. There's been large director buys over recent months, with a possibility of recovery in the business after a poorly executed takeover of a competitor at higher prices. Since then a new CEO in place too. Todays update was taken positively by the market initially before going negative - using 'broadly in line' in their update probably doesn't give much assurance, but can't help feeling that the worst may be behind them.
Why did Norcros (LON:NXR) waste money on a pointless share consolidation that has seemingly brought no benefit?
I'm bored with waiting for this to re-rate too, but at least there's the decent dividend.