Small Cap Value Report (14 Dec 2016 - Part 1) - BOO, LVD, PUB, VCP, TPG

Good morning!
I'm back from my holiday, suitably refreshed. A big thanks to Graham for covering for me whilst I was away. It's worked so well, that we've asked Graham to join the editorial team. So he and I will be working together, to provide better coverage - 5 days per week, all year round (except bank holidays obviously) - and covering more companies too. Plus we'll be able to discuss each other's views too, giving additional thought on many stocks.
Please note that Graham and I are both writing today, so there will be 2 articles, marked Part 1 and Part 2. I will be covering BOO, LVD, VCP, and possibly more.
Graham is covering in Part 2 the following companies - IQE, IDOX, and BOOM.
Here is the link to Graham's article today.
Boohoo.Com (LON:BOO)
Share price: 118.25p
No. shares: 1,123.3m
Market cap: £1,328.3m
(I only hold a tiny, residual long position in BOO, having previously sold nearly all my shares)
Trading update & acquisition - it's a positive trading update. Key points;
- Continuing to trade well
- Revenue growth of between 38% and 42% in FY 17, against previous guidance of between 30% and 35%
- EBITDA margin of between 11% and 12% in FY 17, against previous guidance of around 11%
Therefore, we should expect to see further increases in broker forecasts, continuing a pattern of increases - something you often see with very highly rated shares. It's so helpful when companies give specific numerical guidance like this, rather than generalised text waffle.
All companies should give specific guidance like this. Although I accept that it's easier for retailers, as the figures are easy to predict. Whereas businesses which rely on large contract wins will struggle to give reliable guidance.
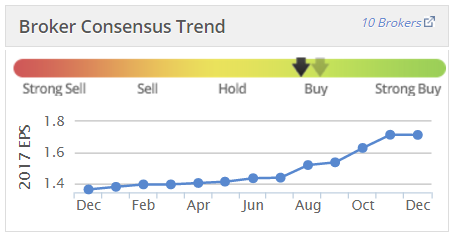
Acquisition of PrettyLittleThing - it's good to see the uncertainty & conflict of interest here has been resolved. PLT is a competing company, set up & run by the son of BOO's CEO. It's been clear for a while that PLT is an exciting growth company in its own right. However, that obviously creates a conflict of interest - not a problem when BOO was a private company, but a very serious problem once BOO is a listed company. You can't have the CEO's son running a very similar business on the side. Hence why a call option was included as part of BOO's float.
The call option gave BOO the right to acquire PLT for £5m, by Mar 2017. So clearly a decision had to be made, and there was only one possible outcome - BOO had to exercise the option, even though PLT is probably now worth multiples of the £5m agreed price.
The deal that's been done is a bit of a fudge. BOO is acquiring 66% of PLT, with founder management retaining the other 34%, providing they meet performance targets (undisclosed), and stay in place for 5 years.
As regards the 34% management stake;
At 28 February 2022, the boohoo Group will have the option to acquire this remaining 34% at market value3
Market value is to be determined this way in 2022;
3. The market value for the remaining 34% will be determined by a Big Four accounting firm. The consideration will be satisfied in cash and/or boohoo Group shares at the discretion of the Group Board.
A reduced consideration will be payable if Umar and the management team do not meet the necessary retention and performance criteria. If the boohoo Group does not exercise the option to acquire the remaining 34% of PLT by 28 February 2022, a dividend of up to all of the PLT distributable reserves at that time will be payable to all PLT shareholders including boohoo, pro rata to their shareholdings.
UPDATE: Broker forecasts - I've just seen some updated forecasts for BOO, as follows;
- y/e 02/2017: 1.9p EPS
- y/e 02/2018: 2.3p EPS (PER 55.7, based on 128p share price)
- y/e 02/2019: 2.8p EPS (PER 45.7, based on 128p share price)
As it's a Feb year end, the current year is nearly finished, so we should be valuing the company on the 02/2018 forecasts. A PER of 55.7 is certainly very rich, but it drops significantly down to 45.7 on the following year's forecasts.
If PLT kicks in decent profits from that point onwards, then there's scope for forecasts to keep rising strongly. The valuation is certainly high, but it's not bonkers, given the company's excellent track record, and ongoing international growth too.
My opinion - I think opinions will differ on this! My view is that it's probably a necessary way to lock in the PLT management - who have demonstrated that they are capable of largely replicating what BOO did in its early years.
So if BOO had bought 100% of PLT, as originally planned, then there's little doubt PLT management would have walked out, and set up their own, private firm to compete with the combined BOO/PLT group.
Therefore, my view is that I'd rather have them within the BOO group, properly incentivised to make PLT work well, than outside the group as another competitor.
Nobody bought BOO shares on the float because of the PLT call option. It was an aside, to deal with a conflict of interest. So in a way, this is a nice problem to have - PLT has done so well, that it is now a serious issue.
Some figures are given on PLT's performance to date, note the very rapid revenue growth;
PLT is expected to achieve revenue growth in excess of 150% in the financial year ending 28 February 2017 ("FY 17"), while being broadly breakeven at EBITDA level.
In FY 18, the Group plans to review and invest in PLT's operations, including its warehousing, to ensure the Company is well positioned for the future. Accordingly, PLT's revenue is expected to grow at a similar rate to boohoo's in FY 18
I don't understand the last sentence. Surely if BOO is going to invest in PLT, then its revenue growth should be maintained at a very high level?
UPDATE: I've queried the PLT growth rate with the company's advisers. The feeling is that, having achieved explosive growth to date, that it's prudent to plan for a pause for breath in PLT's growth rate, as it is assimilated into the group.
Customer service is paramount, so they don't want to drive the top line so hard that support functions are overwhelmed.
Also I think they want to pre-empt analysts getting too excited, and keep expectations grounded.
Overall, I think this deal will probably ruffle some feathers - i.e. people may say that BOO should have bought 100% of PLT, as it was entitled to. However, that misses the point that doing so would effectively destroy PLT, as its management would walk out.
In the circumstances this outcome isn't ideal, but I think it's probably a sensible compromise in order to retain talented management at PLT.
It will of course mean a further rise in forecasts, to reflect consolidation of PLT's results into the BOO Group from 3 Jan 2017.
UPDATE: the market seems to have seen the positive sides of today's announcement, with BOO shares currently up 6.5% to 126p. I'm sure that a rising share price will neutralise any complaints people might have about the terms of the PLT deal.
Lavendon (LON:LVD)
Update - things are getting more interesting here by the day. Shareholders are in the enviable position of having 2 competing suitors, who both wish to buy Lavendon.
Recommended offer - at 220p per share in cash, announced this morning, from Loxam. This trumps the previous, hostile bid from TVH at 205p per share.
Lavendon's Directors have recommended this deal, but as they hold only 0.55% of the company, their votes carry little sway. I presume that the Board would have consulted the big shareholders, and got their agreement before recommending the deal, but you never know.
I've searched today's announcement for the word "irrevocable", to see what level of institutional support there is for this offer. It appears 13 times, but only relating to the 0.55% Director holdings. There's no mention that I can see of any institutional shareholders having given any irrevocable undertakings to support the deal.
So it will be interesting to see if this 220p cash offer is the end of the matter. I suspect it probably won't be, because TVH are still very much in the running, having issued this update today;
TVH sets aside no increase statement - following hot on the heels of Loxam's recommended cash offer at 220p, TVH has this morning informed the market that it is considering its options. Its original statement that 205p was the highest price it was prepared to pay, has therefore been withdrawn.
Clearly then TVH is considering whether to submit a higher offer. Even if they do, who's to say that's the end of the matter?! Exciting stuff. Well done to people who held on.
My opinion - two or more competing bidders is a dream scenario for shareholders, as it makes it very likely that one or other bid will go ahead. Also it's more likely to maximise the price, given that the company is now really being auctioned off.
At 231p per share, the market is pricing in an increased offer.
In my view neither offer is generous. The stock market fundamentally mis-priced Lavendon, as I have said before these bids emerged. So the forward PER is still quite modest at 11.7. I don't think that's really much of a bid premium at all. It's more the case that the starting price was completely wrong, at about 130-135p level.
That said, if the recommended bid is rejected, the share price is likely to just slide back down. Therefore, if I still held, I'd be keen to exit if a higher bid, perhaps around 250p, is forthcoming.
Personally I sold out at 190-195, because I had no idea a competing bidder was lurking. Never mind, nobody ever went bust banking a decent profit!
Punch Taverns (LON:PUB)
(at the time of writing, I hold a long position in this share)
Takeover speculation - I noticed that the share price here had shot up this morning, so called my broker to ask if they had seen any information to explain it (no RNS, at the time of writing). He advised me that apparently Sky news is reporting that Heineken may be interested in buying Punch. He then quipped "Britain up for sale, with sterling at this level". Quite. Exciting times for investors though.
With the share price now up 21% to 156p, the company will have to issue an RNS to confirm or deny the press rumour.
I shall report back once we have some news.
We had a discussion at Mello Beckenham recently, looking at potential takeover bids. I mentioned Punch Taverns (LON:PUB) and Enterprise Inns (LON:ETI) (I hold long positions in both) as both being special situations, where a bidder might see an opportunity to restructure their debt onto lower interest rates. That would transform their profitability - as both are currently loaded with expensive borrowings.
I've topped up my holding in ETI this morning, as if a bid does appear for PUB, then I see obvious read-across which should boost ETI's share price too. Both have heaps of freeholds on their balance sheets, although it's questionable whether book value is realistic or not. Although bear in mind that plenty of pubs have good alternative use values - I looked at a boarded-up pub in Cheshire, which some friends were hoping to buy for c.£300k. The agent told us that a supermarket had bid over £600k for it. So don't assume that failing pubs are necessarily a liability, in some cases they could be a windfall asset.
UPDATE: Here's the RNS - Possible offer for Punch Taverns - Punch has received TWO takeover approaches.
Patron Capital Advisers LLP/ Heineken - Punch is in "advanced discussions" regarding a possible cash offer at 174p per share. It is conditional on the Board recommending it.
Emerald Investment Partners Ltd - this sounds like an earlier stage approach, but is for a possible higher cash offer, of 185p.
The Emerald Proposal is conditional on, amongst other things, arranging committed financing, confirmatory due diligence, and the recommendation of the Board. The Board is in discussions with Emerald regarding the Emerald Proposal.
My opinion - this is turning out much like Lavendon, with 2 competing potential bidders. Hence I'm sitting tight, indeed have bought some more today at 170p. I wonder if we might see the competing bidders raise their price to 200p+? That's what I'm hoping. What an exciting year this is turning out to be!
A couple of quick comments before I finish.
Victoria (LON:VCP) (at the time of writing, I hold a long position in this company) - Acquisition - this buy & build group is picking up another acquisition in Australia, a manufacturer & distributor of underlay and hardwood flooring.
The acquisition is costing £20m, funded from existing debt facilities, so will be earnings enhancing. The multiple being paid is a fairly modest 5.7x EBITDA.
Post-acquisition, the key measure of group net debt : EBITDA multiple will be less than 2x, which seems OK to me.
My opinion - I was late to the party here, but very much like the strategy. The charismatic Chairman, Geoff Wilding, has already transformed the group, and doesn't seem to have put a foot wrong with a series of excellent acquisitions.
So expect further forecast increases, following this latest acquisition. As long as the debt doesn't get out of hand, then it's difficult to see much downside here. Remember that VCP's UK operations are a big beneficiary of weaker sterling too, as it makes them more competitive versus competition mainly from Benelux.
TP (LON:TPG) - this share is up 21% today to 6.1p. I've never heard of this company, but discover that it used to be called Corac, and has a fairly dismal history as a listed company. Note that the chart is characterised by large spikes up, followed by disappointments.
Nevertheless, the company has issued a bullish update for both 2016 and 2017, based on a strong order book & improving margins.
The TP Group Board is pleased to announce that the business performance in FY16, in terms of EBITDA, is likely to significantly exceed current market expectations.
In addition, subject to the receipt of expected payments, the Group's year-end cash position is also likely to exceed expectations. The Company expects to make a further update in January 2017 and to announce audited results for the year ending 31 December 2016 in April 2017.
In addition, due primarily to recent contract wins and a strong order pipeline (including the two sole source MoD contracts announced in July and August 2016) the TP Group Board is pleased to confirm that it expects the outturn for the 2017 financial year, in terms of EBITDA, will be materially ahead of current market expectations.
Sounds interesting. Maybe this share is worth a fresh look?
That's me done for today!
I think it will probably be both me & Graham reporting again tomorrow (Thu). Then just Graham on Friday, as I have a bit of a monster Xmas party to go to tomorrow evening, so am planning a lie-in on Friday morning.
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
Good to see you back Paul. Excellent insight :D
"I only hold a tiny, residual long position in BOO, having previously sold nearly all my shares"
Paul - think this is exactly what you did with ASC. Given your passion for BOO, I am a bit surprised .... so far I have resisted the temptation to cash out meaning it is my biggest holding now.. Good luck to all holders.
.
Paul - looked back at post 40 and it was a rubbish post by me. Sorry. There was genuine surprise that you had reduced your holding as you are so passionate about BOO .....but as you say it looks like I am crowing over this which was not the intention and is unnecessary. Please accept my apologies.
Paul delighted you are back, hope you had a great break, and delighted that you have "allowed" Graham to enter your space, says a lot I believe. I know you welcome sensible polite challenge and debate so having the two of you comment and may be sometimes taking a different view or even the same, will be just fantastic. I have renewed for another three years so don't go away :)
I have held Boohoo for 12 months now and do thank you repeatedly, Paul, for the initial lead..
I see that Panmure Gordon issued a research note this morning. They have raised, somewhat optimistically, their target price to 170p.
Do we have have another ASOS on the books?
Re Boo
"Customer service is paramount, so they don't want to drive the top line so hard that support functions are overwhelmed."
Customer service and warehousing is already provided by Boo for PLT so that should not cause many integration issues. Seems sensible to provide "conservative" guidance for PLT, as management have learnt to do for Boo itself.
Paul, I notice that Marshall Wace have a short on Boohoo. Coming down a bit but 0.69% of the share capital. My question is more general than Boohoo. Do you ever take much notice of short positions?
Hi doublelutz,
I review the list of most shorted stocks every few months, and if there's anything on there that I own then I'll sit up & take notice, and have a think about things.
I like to think about the bear case of every share I own. It's a very good discipline. Often you find that shorters are just latching on to a toppy valuation. Sometimes though, they find something seriously wrong with a company, so it's worth considering the opposite view quite carefully.
Regards, Paul.
Yes some shorts can show up the problems in a company, Globo would be a good example. They are not always right but they are worth looking into.
@ Paul: Welcome back and thanks for the efforts so far.
Any chance you could share the presentation you did last month on your thought process behind AVS and thus, potential takeover targets?
Thanks..
http://www.piworld.co.uk/mello/2016/11/22/mello-20th-november-2016-paul-scott-avesco-avs-presentation
I think the £BOO update today was spectacular. Revenue growth significantly in advance of expectations (ironically as somewhat expected, especially by Peel Hunt whose research on BOO is worth getting hold of if you can) and improved margins too.
I like the PLT solution - it gets the full results consolidated in the group so we can see what's going on, but still allows the undoubtedly talented Kamani sons to be incentivised for continuing with their success. It's a golden goose problem to me - BOO management could have taken the short term greedy option and acquired 100% "on the cheap" for £5m. But my view is that it's a much more finely balanced question as to whether 100% of PLT without the Kamani's in five years time would be worth more than taking 66% now whilst keeping the Kamani sons interested and engaged in growing the business and then acquire the 34% at market value in 5 years time. Better to let the goose continue laying golden eggs rather than taking a knife to it IMO.
As regards forecasts, I still think they are very much living in the shadow of the Jan 2015 profit warning and will continue to under promise and over deliver. PLT revenues will surely grow more than 25% next year, as will BOO's revenue and profits as a whole. It's a firm hold for me, as it has been since around 40p.
A massive thanks to Paul for all his insight, research and, frankly, hard work.
BOO
I understand the rationale behind keeping PLT management on board but have I got this right- BOO invest money in PLT and then give 1/3 of the increase in value thereby created, including presumably the capital introduced, to son? Sounds like the 21st century equivalent of a sinecure to me!
Paul may wish to ask if any capital introduced by BOO is excluded from the deal?
I only had a relatively small position in boohoo, and I've still got most of it though I'll be top slicing today I suspect.
I have no problem with incentivising the management of plt, and tying them in, but perhaps a big chunk of shares should have been the reward, not given up front, even though there is a tie in.
And did they still get the full £5m for 66% of the company ?
This doesn't seem that different to the value generation deals that management sometimes give themselves and we here complain about, except this time the father has given it to his son's company.
However hard to complain when the share price shoots up, doesn't change the fact that it doesn't really seem right and fair.
I would rather have the founders in than out, for sure, and incentivised, I'm not sure giving a third of the company up front for free is either necessary or the best way to achieve this. However if it was my son then I would see things differently no doubt. Will this mixed ownership make it harder to integrate the operations behind the two brands ? might a complete take over and options in boohoo based on results of the plt unit have been more appropriate ?
K
No, they paid pro-rata, £3.3m for two thirds.
I agree better to keep them in the business than outside competing. I also think PLT would have a market value well above £5m so on this occasion I am content with the distribution of the spoils and continue with my modest holding.
Ref Boohoo
If current management can run Boohoo surely they could run PLT too, i just don't see the Logic that the current management and needed in any respects. In some respects morphing into the exact same strategy as used by Boohoo to me is more likely to work and cope with expansion issues. In my mind this would been much better sorted via offering some decent options/salary to Bods running PLT to onboard them via any normal type agreement that would have been demanded had this not been associated Bods.
Delighted to read that Paul and Graham will both be writing.
Are there any guidelines over the types of company that either will cover?
Hi troytea,
Delighted to read that Paul and Graham will both be writing.
Are there any guidelines over the types of company that either will cover?
Pretty much the same as now - so small caps usually from £10m to c.£400m.
Usually we won't cover anything from the following sectors:
resources, financials, property & other investment companies, biotech/pharma, blue sky, also we'll rarely cover overseas AIM stocks because most are complete rubbish!
We might occasionally stray into mid to large caps (especially with retailers, my specialist sector). Also, I like to focus on big market movers each day - so takeover bids, or profit warnings.
Basically if anything is topical & we can add value commenting on it, then we will! But overwhelmingly small caps.
Regards, Paul.
I suppose by the time of the January trading statement we might hear news of £BOO "stalking horse” offer for Nasty Gal.
Nasty Gal is an American retailer that specialises in fashion for young women. The company has more than 550,000 customers in over 60 countries but filed for bankruptcy a few weeks ago.
Carcosa
You've gone and done it again, Punch Taverns (LON:PUB) soaring. Makes up for the mess with Fairpoint a little?
Hope you had a nice holiday Paul. Any thoughts on TPG? Their trading statement today is very positive.
Welcome,back,Paul.Any thoughts on TUNG - are they making progress ?
Hi AlanJenkins2,
I have a quick look at Tungsten (LON:TUNG) results today, but wasn't impressed. It's still all jam tomorrow. Whilst as things stand currently, the company is a long way from being viable. Although with the sale of the bank due to happen in a week's time, that should give it enough headroom on cash to survive for several more years.
There's lots of talk about improving performance, etc, but why pay up-front for a company which has performed so dismally in the past, in the hope that things are going to get better?
Also the amounts of invoices financed for early payment is absolutely tiny.
I'm not at all tempted to buy back into this one. Why waste time on over-hyped loss-making companies, in the hope that they might be able to turn a profit one day?
Regards, Paul.
Thanks,Paul.Cheers,Alan
Hi Paul and welcome back!
A couple of companies.
1: Zytronic - I thought the results were decent, the action on the distributable reserves and the dividend encouraging, and that the valuation remains attractive, especially when you strip out the cash. However the shares were down. Am I missing something apart from the recent price move up?
2: Bioventix: Did you attend the meeting last night? I wanted to go but am immobile due to recovering from a minor operation. If so was the revenue replacement story still on plan?
Regards, Peter
Welcome back Paul. So pleased there are now two of you in harness. I hope my taking out a years subscription helps pay for the increase. Lavendon and Tristel are two pointers from you that make it worthwhile. Very rare in investment circles to find such good quality research I've found.
Paul - from your lack of disclosure, do I take it that you have sold out of Boohoo?
Ah, sorry I forgot to put in the disclosure actually.
But I only hold a tiny residual position in BOO, via my local share club. I'll update the article to clarify this.
Thanks for the prompt.
Regards, Paul.
If you don't mind the question - why did you sell? I think you said you considered Boohoo.Com (LON:BOO) as your highest conviction hold? I'm guessing it'll be due to the valuation being too high now? I used to hold, but like you, sold out recently.
Hi sptmjdr,
Re Boohoo.Com (LON:BOO) you asked,
If you don't mind the question - why did you sell? I think you said you considered Boohoo.Com (LON:BOO) as your highest conviction hold? I'm guessing it'll be due to the valuation being too high now? I used to hold, but like you, sold out recently.
I sold BOO purely on valuation grounds, far too early, as it now transpires.
BOO is a fabulous company, but everything has a price, and I just thought the valuation was looking too full for me to continue holding. I freely admit to having sold too early, so obviously wish I'd continued to hold.
My background is very much as a value investor, so I find growth company investing very difficult, as it's going against the grain. The reason I've branched out into growth company investing, as well as value investing, is because growth companies is where the biggest gains are to be made - at the moment anyway.
Value investing is out of fashion at the moment, although as proven by Lavendon (LON:LVD) (and today Punch Taverns (LON:PUB) ) they can get exciting when they attract takeover bids.
Also, I think with BOO it's down to percentages. With the valuation now very high, what are the chances of BOO doubling again any time soon? Pretty slim, I'd say. Mind you, I thought that at 60p too, and it has very quickly doubled from there lol!
It's very difficult to predict what the market will do. So deciding when to sell is always the most difficult question of all, and it's not something I'm at all good at, I'm afraid.
Regards, Paul.
Hi Paul any chance of having your thoughts on Paysafe are you backing the truck up again ? (love that quote) looks a similar issue to about 18 months ago when there was hoo ha about the chairman's shares on loan from memory.
Looks a buying opportunity to me unless the board are telling fibs but would appreciate your thoughts as always.
Cheers Andy
Hi clarea,
I'm steering well clear of Paysafe (LON:PAYS) - I've always thought that company had a bad smell about it.
Its profit margins are too high, and there seems to me little reason for the company to exist, other than to disguise dodgy transactions. Same with Wirecard (where I have had a short position for quite some time).
So I wouldn't touch either with a bargepole.
Regards, Paul.
Paysafe (LON:PAYS) 's market cap £1.5bn . Not exactly one for Paul's SCVR?
Indeed a large market cap Ram however it was one Paul was keen on when it was involved in volatility 18 months ago that time he was a believer in the company and bought heavily and came out the right side of the trade, Interesting that he;s moved to the bear side since then,
Paul
Welcome back.
Burford Capital (LON:BUR) have done an acquisition and Air Partner (LON:AIR) did one yesterday. Comments from you or Graham would be appreciated. The market seemed to like both.
Regards
Howard
I was delighted with the Burford Capital (LON:BUR) RNS. Really clear and thorough explanation and a clear rationale behind the deal. Also very encouraging that it is being funded in large part from this year's cashflow. Has the potential to take things to the next level if they execute the takeover well.
Welcome back Paul.
Perhaps you or Graham could also cover Victoria (LON:VCP) 's acquisition of Australian co. Dunlop Flooring. It looks like an attractive bolt-on at a EBITDA multiple of 8.6 . The one nervousness I have is that the carpet flooring sector is perhaps not a good place to be with inflation looming and consumer spending likely to be squeezed.
Hi Ramridge,
Yes, VCP is already on the list - as mentioned in the preamble to today's article!
Regards, Paul.
D'oh!
Welcome back Paul.
I am also puzzled by that same sentence as you in the Boohoo.Com (LON:BOO) update
PLT revenue grew by over 400% to £17.0m (FY16)
PLT forecast growth in excess of 150% (FY17)
So you would think continual growth would be 75-100+% since they are still coming from a relatively low base but they say..
PLT's growth will be at a similar rate to boohoo's in FY 18
Well, BooHoo would reasonably expect to grow at 30-40% again (a guess) but would that not imply PLT's growth rate would have the brakes applied to it. ? Why? Physical constraints?
Of course the alternative is that BOO would be growing much more than 30-40% and around 70%+ but that seems fanciful to me.
Carcosa
You got this out early, Paul. Thanks, great work. Boohoo.Com (LON:BOO)
Hi StandardModel,
You got this out early, Paul...
I'm still on Abu Dhabi time (4 hours ahead). Give it a few days, and things will rapidly deteriorate, I'm sure!
Regards, Paul.
Welcome back, how was Abu Dhabi ?
Recomended as a winder sun destination ? is there much to do there ?
veg out ?
would it be good for kids ?
K