Small Cap Value Report (14 Dec 2016, Part 2) - BOOM, IDOX, IQE

Paul and I are going to try having two separate articles, on days when we are both writing.
Here is the link to Part 1, where Paul covers BOO, VCP, LVD, PUB
Audioboom (LON:BOOM)
Share price: 2p (-6%)
No. shares: 638m
Market cap: £12.7m
Key points from this podcasting platform's Q4 update:
- Unique file requests (i.e. how many times people listened to something on the platform) are up by 42% to 145 million, compared to Q3.
- Number of unique users has doubled compared to a year ago, now at 58.6 million
On the financial side:
Overall 2016 revenues are expected to exceed £1.3 million, an increase of more than six fold compared to last year, and ahead of market expectations. The rate of growth in 2016 has continued to accelerate from H1 to H2, with Q4 revenues of more than £630,000. This rate of revenue growth has continued post year end, with over £1.1 million already booked for advertising campaigns in 2017.
When something is starting from a very low base like this, the fact that the growth rates are explosive is not too important me - there is no alternative, or the company won't go anywhere!
However, I must admit that the operational metrics sound quite good. The others, less so:
Due to acceleration in audience
acquisition costs and higher recruitment fees to acquire USA commercial
head count, the Company expects its EBITDA loss for the full year to be
greater than market expectations. The Company has taken steps to reduce
costs through new ad-serving and bandwidth partnerships which it expects
could achieve cost savings of approximately 40% for 2017 over 2016 in
this area. Additionally, UK annual headcount has been reduced by
£465,000 to allow the Company to focus on its growth opportunities in
the USA.
The year-end cash balance was c. £710,000.
Clearly, then, this is not an instance of self-funding growth, since growing the audience base is increasing the rate of losses.
Slashing UK headcount sounds worrying - is the company caught between two stools, the US and the UK? It's never very encouraging to see a company spreading to a new jurisdiction, without having first achieved success at home.
Also, the funding discussions with the Chinese fund (for an injection of up to $8 million) have ceased. Audioboom's cash balance is now £710k.
My opinion:
I'm not very happy with the wording of the RNS. Consider this:
Further to the announcement dated 3 October 2016, the Audioboom Board has ceased to seek investment from the Chinese fund and rather focus on its core business.
That would lead you to believe that missing out on the Chinese investment is no big deal, because the funds were going to be applied to non-core activities. But the potential investment was initially described in this way (5 August):
The funds received from the strategic investment are to be applied towards accelerating the growth of the Company and not for working capital purposes.
How is accelerating the growth of the company not part of its core business? I can't find any previous suggestion that the Chinese funds were to be used on non-core business.
Looking forward, it's hard to imagine that the latest cash balance of £710k is going to be sufficient for terribly long.
At the interims, the company had £0.9 million, at which point it raised £2.55 million at 2.5p/share.
With all of those funds used up, and more, and with the share price now at 2p, more dilution is in store.
What more can I say? This is highly speculative. Considering that over £7 million was racked up in costs last year, I don't see how it can possibly get to breakeven quickly enough to spare investors from suffering a lot more dilution. And that would be the best-case scenario. A nice app, but I'd steer well clear of these shares.
Share price: 63.9p (-9%)
No. shares: 361m
Market cap: £231m
Final Results (year ended 31 October 2016)
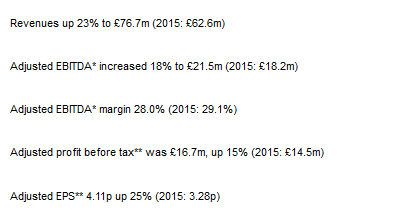
The headline numbers look quite encouraging here, as do the statutory figures. Net income improved from £7.8 million to £11.8 million. Quite a nice result for a business which specialises in support services and software for the public sector. Most (82%) of its revenue is on a recurring basis, giving it fantastic visibility.
It's on quite a high earnings multiple, which can make it easier to disappoint some investors and produce a sell-off such as we've see this morning.
The overview mentions "generally stable markets" and "challenges in some of our smaller markets", but the outlook is very positive and it remains ambitious to grow:
The Board remains confident that the Group is well positioned in its markets and will continue to perform well in 2017 given its strong revenue visibility, order book and pipeline. The Group remains on track to achieve its target of £100m of revenues at sustainable margins in the short to medium term, through a combination of organic growth and acquisitions.
Overall, the outlook for Idox in the coming years is therefore very positive and our expectations for the Group's financial performance are unchanged.
The company remains on the acquisition trail, and is raising gross £20.5 million to buy the next target, as described in a separate RNS:
6PM Group, founded in 2004, delivers software and solutions, principally to the UK NHS.
The Acquisition offers Idox the opportunity to expand significantly its presence in the health and social care market whilst playing to the public sector efficiency and cost saving agenda.
My opinion: Looking into the footnotes, I think Idox might be paying a full price for this company. Including its debt and working capital needs, the deal values 6PM at c. £35 million. Its estimated EBITDA for 2016 is £2.9 million - I wonder what the net income might be?
Overall, I have a fairly positive view on Idox. Recurring public sector software sales are probably very dependable! It's carrying £25 million of net debt, which does not appear excessive - though I'd note the company says that if the Placing does not succeed, it will use some more debt to get the purchase of 6PM through!
Overall, it strikes me as worth looking into some more.
Share price: 37.75p (+8%)
No. shares: 675m
Market cap: £257m
Excellent update from this manufacturer of semiconductor wafers:
Since the announcement of its interim results on 13 September 2016, IQE's trading has continued to be strong across multiple markets, particularly in the photonics business. As a consequence, the Group announces that it is on track to deliver FY 2016 revenue and adjusted1 operating profit ahead of expectations. It is anticipated that revenues will reflect a double digit rate of growth year on year, and that H2 revenues will be up sequentially over H1.
In the above-mentioned interim results, revenues were up 18% and adjusted operating profit up 61%, and clearly the momentum is continuing.
The company notes that results will be boosted by the GBPUSD exchange rate, while also noting that the impact is "presentational" (since both its revenues and costs are denominated in USD).
The shares have more than doubled since the summer, and brokers are forecasting adjusted EPS for calendar 2016 and 2017 both at 2.9p.
My opinion:
There are probably not too many experts in photonics among the investor community (I am not one of them, either), but it seems like a great place to be at the moment.
In H1, the photonics segment generated a 45% growth, and IQE said that the relevant technologies "are now hitting the performance and cost points necessary for mass market adoption."
Even taking into account the debt/deferred consideration on the balance sheet (£35 million in June), the 12x PE ratio on this is looking a bit stingy to me.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

31 comments
I was expecting a review article from Graham after the final results.
Idox (LON:IDOX) are presenting next Tuesday 21st February 2017, in the afternoon, in Central London. Contact piworld.co.uk if you'd like to attend.
Tamzin
IDOX figures OK, not clear how the acquisition fits into their current market focus though. Also really don't like the fact there will be no Open Offer alongside the placing. I am going to get diluted. Smaller shareholders should object and there will be a vote, so vote against the placing.
I would except my modest holding is in a SIPP which makes it all hard work. I doubt that there is a realistic chance of successfully voting it down.
To me the best likelihood of stopping this abuse is maximum publicity - starting with the excellent ShareSoc, social media, letters and emails to the board etc. Anything that pricks the conscience and draws it to the eye of the FCA, the Stock Exchange and the popular press.
Am certainly planning to get some publicity on IDOX.
Roger Lawson
Graham,
IQE (LON:IQE) was a story share when I bought in at 14.08p in 2008 (new plant in Singapore, 35% utilization, profit straight to bottom line, from FT, mid noughties) I held until the "de-stocking crisis" and sold at 30p. They then took over three competitors one of which at no cost just a, well below commercial, discount for an agreed period (not disclosed). All results from 2013 are adjusted to assume the product was sold at the non-discounted price. They make a profit. They have no cash flow. Smoke and Mirrors and I have reservations about the joint venture with Cardiff University, assets have been transferred to P&L as profit in relation to the venture and now boost the balance sheet. As far as I can see "real" cash flow has ben negative for years but the increase in "adjusted profit" has funded huge benefits to directors. Was Ponzi the director of any firms other than his own?
Just saying,
Caveat emptor, regards, Seadoc
Hi seadoc
The history is interesting and complicated but I'm interested in the present;
http://www.investegate.co.uk/iqe-plc--iqe-/gnw/iqe-plc---interim-statement/20160913070101H1668/
"Strong financial performance with double digit growth in revenues, profits and cash generation
Revenues up 18% reflecting increasing revenues in all markets
Adjusted fully diluted EPS up 62% with the benefit of the Groups highly geared business model
Increased profitability converted into 176% increase in cash generated from operations
Balance sheet leverage reduced by 28% to £35.4m
Kopin deferred consideration balance of £10.7m settled in full in January 2016
Remaining balance of deferred consideration will be settled in full by the end of this month (September 16)."
So £12.4m in cashflow in H1 and Net cash generated from operating activities increased more than threefold from £3.5m to £11.0m.
So profits are real and turning into cash.
I hold a lot of IQE and the history you allude to is one of the reasons it popped up as a value play and I'm sure it'll take time to rerate to reflect more about its future than its past.
Cheers
Rhomboid,
I am sure you are right, as per your evidence, witnessed by investigate. I bought into the rise from the last trough on the basis of FT (not Sir John Lee but one of other excellent columnists in weekend FT). I doubled my money, may you do the same or even better. Clearly had I not sold on the way down from 60p and held on for another few years and through the next trough I would have got a few pence more for my shares but nothing in dividends for 6 or probably a few more years to come. I hold a bus pass and look for income in my remaining years and value this above the promise of jam tomorrow.
As I said, I await the results March 2017 with forensic interest and accept I may well be wrong but for me this is not the one.
Regards,
Seadoc
Hi Seadoc - would be interested in a write up of your thoughts on the results in March if you would be so kind!
Is2g08,
Yes, I tend to spend (waste?) my time fussing over what I still hold but probably I, and indeed we all, should spend a bit more time on near miss shares, whether that be one already sold that bombed or perhaps worse ones we nearly held or nearly bought that went stratospheric.
It is one of the reasons I look forward daily to read comments from Paul, and now Graham. The ones Paul got wrong have been more "educational" than those (?the majority) he got right. I confess that I hold a couple he would prefer to avoid, and one of those is my best performer of 2016. And I still have high hopes for the other.
Write up on IQE, late March, is on my to do list. Will be on here if the grime reaper spares me, this site and IQE.
Seadoc. Did you ever find time to look again at IQE (LON:IQE) ?
FREng,
Yes, spared by the grim reaper and got to read the annual report, but see numbers do not appear until page 74:
http://www.iqep.com/media/149511/2016AnnualReportWEB.pdf
and ten of the preceding pages explaining the ridiculous pay for directors. In the days of paper reports any company who had an AR weighing more than the market cap was a sell. My summary: Profit £24m, divs nil, cash up £300,000. Who got all the pies?
I sold out at 30p having doubled my money, perhaps I should have taken a valium, a big spliff, put a clothes peg on my nose and held on, would have doubled my money, actually in last few days potentially trebled my money, but hopefully whoever took my shares has already passed them on. I still see (OK imagine?) a big crash. And your reading of the annual report?
Regards, Seadoc
Graham
Congratulations, on the news your joining the excellent Stockopedia team ..... well deserved.
Thanks Oscar, it's great to be here. Thanks for your support.
First time results from recent IPO FreeAgent Holdings (LON:FREE). It provides accounting software to micro businesses. It sells direct and through accountancy practices and a bank. It's still loss making at the moment. These types of businesses tend to attract very high multiples owing to the the very sticky customer relationships and subscription model. Can't see any forecast at the moment to see when a profit is projected.
Ref Free
I use most of the online book-keeping offerings and FreeAgent is a class above most of rest with regard to the Simplicity of Use and the Logical Layout and customer Support. It does cost more than the other competitors though so its tricky so say whether they will be able to hold their own with the Onslaught from Sage/Xero/Kashflow/Quickbooks et al. It should be down to subscriber numbers though as their product is fairly complete so double the sales and the extra costs shouldn't be much. I would have confidence that their customers and nice and sticky once signed up so perhaps i need to have a look at this one.
N+1 Singer has an excellent summary on the Burford acquisition this morning headed.....'A gorilla is born'.....worth a read.
IDOX (I'm long) has demonstrated excellent growth in EPS, turnover and of course share its price has doubled over the last three years. During this time I understand it will have widened its target market from local authorities to the oil sector, which might be a big driver going forward if recent recoveries in price hold.
In the valuation of 6PM Group they say that it will be earnings enhancing from 2017, so should produce a PE of at least 17X earnings. On their value of £35M that would be about a £2M net post tax profit. It would be nice if they would just say so, I agree.
To me the price vs earnings growth looks fine and should not have precipitated a 9% fall. I have not seen the figures for the accelerated book building and placing yet but if I am allowed a wild guess we will see shares issued at a 10% discount to last night's closing price. The institutions privileged with the discounted placing offer will then sell their holding down until the price is just above the cost of their placing, realising a quick profit at the cost of other less privileged shareholders. This whole practice is a disgrace IMO and companies should be forced to compensate those shareholders who are not invited to participate.
IDOX No surprise here - Placing at 60p. If I am not invited to take part I recon they should pay me something like 7p per share to compensate.
Hi Graham - I had a good look at Idox (LON:IDOX) this morning and generally agree with your assessment.
Worth mentioning that it has a very healthy FCF as well.
However at the current valuation, I reckon it is fully priced and it appears they are also paying a full price for the acquisition. I am always suspicious when an RNS doesn't mention an acquisition's net profits.
On balance a good company, but IMO upside is limited on current valuation
Thanks for the feedback Ramridge, you may be right on valuation.
Good points by monty too... I've just retweeted an IDOX shareholder (carmensfella) who has expressed disappointment at the lack of an open offer.
Graham, do you know Burford Capital (LON:BUR),? They have just announced acquisition Of Gerchen Keller Capital which has gone down well with the market shares are up 13% today. Any views would be welcome.
Hi Herbie
I asked the same question about Burford Capital (LON:BUR) in Paul's Part 1 posting today. Also, Air Partner (LON:AIR) announced an acquisition yesterday that seemed to be acceptable to Mr Market, in case you are holding/following that share.
Regards
Howard
Yes but Burford Capital (LON:BUR) is too large for Paul and he does not cover financials. That's why I'm asking here. No I don't hold Air Partner (LON:AIR) at the moment.
Hi herbie/howard, it's too late in the day for me to start doing a writeup on Burford Capital (LON:BUR) but it does look very interesting alright - and I like midcaps and financials! If I can figure out a way to make time for it somewhere then I will.
Any thoughts on TUNG, Graham ?
Hi Alan, sorry I've got nothing to add on TUNG at the moment - but I'm glad to see that Paul has answered you! Cheers for making the request.
Thanks,Graham.Cheers.
Can't find Paul's post....where to look?
DPO, just hover over the Home menu and select 'Small Cap Value Report', it's the article timed 7.16am below this article in the list.
Two separate articles, that'd be great, I have very much enjoyed reading your posts on here... although of course I like Paul's posts too :-)