Small Cap Value Report (14 Oct 2014) - BOO, SPGH, DGB, ALL

Good morning! I'll rattle through today's report asap, as I have to prepare a 10 minute talk about shareholder rights at a ShareSoc seminar later today. Should be an interesting event - I'm really pleased that ShareSoc has decided to tackle the issue of nominee accounts, and will be lobbying to have the system reformed so that shareholder democracy is brought back. I feel that shareholders being disenfranchised by the nominee system is the root cause of many issues in corporate UK - excessive remuneration for Directors, rewards for failure, etc. If you have an absentee ownership class, then the managerial class will run riot - which is exactly what the situation is today! That needs to change. Right, on with today's results & trading statements.
Boohoo.Com (LON:BOO)
Share price: 43.25p
No. shares: 1,120m
Market Cap: £484.4m
With a market cap just under £500m, this is really moving into the foothills of mid cap territory, but being a rapid growth etailer of clothing, it interests me due to my background in this sector.
The shares look expensive at first sight, but when you dig deeper, it starts to look potentially interesting. BooHoo is based in Manchester, and was set up by experienced rag traders, who have been suppliers to retail chains of mainly budget ladieswear for many years. They came up with the idea of cutting out the retailers, and supplying customers direct via a website, and it's going rather well! Whether a wobbly stock market such as we have at the moment is ready to take the shares any higher, is a good question - possibly not, in the short term anyway.
Interim results - to 31 Aug 2014 are issued today. Turnover is up 31% to £67.2m, but the company has an H2-weighted year, so broker Zeus is forecasting full year turnover of £160m (vs. £109.8m last year), so note the very strong, and all organic growth. The market pays up for rapid organic growth, so this share should be on a high PER, which it is.
Pre-exceptional profit before tax was £5.7m for the six months, a little lower than I was expecting, but this is probably due to the rapid expansion of the business - note that their warehouse was enlarged with a mezzanine floor, which must have caused considerable disruption. Although the company now has enough warehouse capacity to handle much larger volumes.
Outlook - the company today says;
Our focus remains on further expanding our international footprint while growing sales in the UK. During the current quarter we have managed our marketing spend and growth during the implementation of the warehouse management system and the launch of the fully responsive mobile website. Following the successful execution of these key initiatives, our marketing spend has again increased in line with our targets and we continue to trade in line with market expectations for the full year.
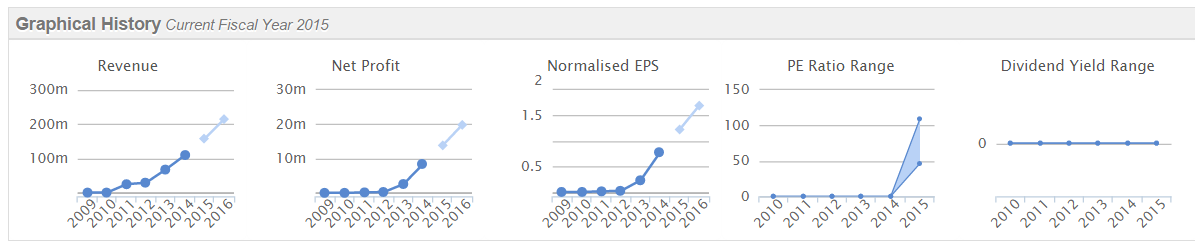
Valuation - full year forecasts are for 1.28p this year (ending 28 Feb 2015), and 1.92p the following year, putting the company on a PER of 33.8, falling to 22.5. Expensive yes, but look at the organic growth. On a PEG basis, you could argue that this is good value.
Balance Sheet - is very strong, with net cash of £55.7m, and a current ratio of a very strong 3.35. So no doubt the company will be using its strong finances to secure prompt payment discounts from suppliers.
Dividends - none as yet, but these will start once the rapid growth is behind them.
My opinion - this is a very impressive organic growth company. It achieves a higher operating profit margin than Asos, and is growing faster than them too, so its lower rating looks a far more appealing proposition to me than Asos, even after it has collapsed from £70 to £20 per share.
At some point, I can foresee BOO shares significantly rising, but perhaps not for the time being in the current more sceptical market, where people are throwing out their highly rated shares.
Superglass Holdings (LON:SPGH)
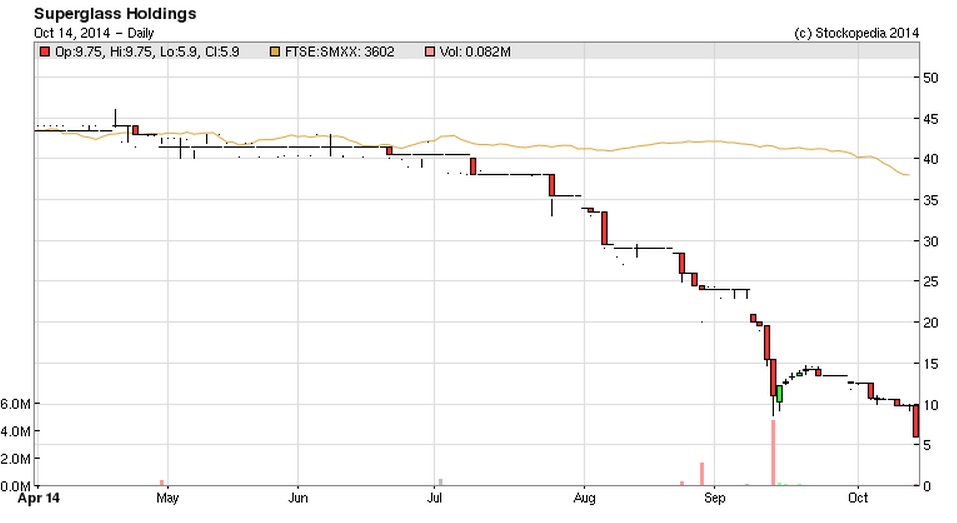
I warned readers here on 30 Apr 2014 that things were looking grim at this manufacturer of insulation material, and that the company would need to raise more equity, when the shares were 43p.
They have since slid down to 9.7p last night, and another lurch down today to 5.9p on the announcement of a 5p Placing. Oh dear. This is a very good example of why it's rarely a good idea to buy shares in a poorly performing company that has inadequate cash resources. When the Placing does happen, it will usually be at a deep discount, and of course the price will go down heavily beforehand as most Placings seem to be quite leaky - so the temptation to break the law and do a bit of insider dealing is usually too much for someone in the chain.
There really needs to be a better system, whereby shares are briefly suspended when a Placing is going on. It's a false market if shares remain traded when some people are aware that a discounted Placing is underway, and others aren't.
Anyway, there we are. The company should survive now I think. Last time I looked at it, cost-cutting was beginning to work, and you could see a just-about viable business emerge. Note that the existing bank have taken a 15% haircut to get out. A new bank is making available a new facility. So good luck to the company, it's had quite a few lifelines thrown at it now, so it really has to perform this time - I doubt any further financing will be forthcoming if it remains loss-making.
Digital Barriers (LON:DGB)
This is a share I've been bearish about here for the last 18 months, because the valuation looked nuts, and the company has performed badly - a fairly sensible couple of reasons to be bearish in my view!
Sure enough the share price has dropped heavily from 178p when I first wrote about it here on 2 April 2013, to 67p today (for a market cap of about £43m).
Trading update - today sounds a bit more promising, with a;
"much stronger contracted backlog position and sales pipeline than at the same point last year"
It's still loss-making though;
The Board expects losses for the first half of the current financial year to show a year-on-year reduction and for this reduction to accelerate through the remainder of the financial year driven by continued revenue growth alongside a successful reduction in the cost base.
Net cash as at 30 September 2014 was £7.6 million.
My opinion - I don't know anything about the company or its products to form a view really. However, I'd want to see a very clear path into profits, with a high probability of success, before considering an investment here. Also one would need to carefully check that the cash reserves are enough to get it through to profitability, as another fundraising would dilute the upside. The £43m market cap doesn't skew risk:reward favourably enough, in my opinion, to justify a further look here, as it is forecast to not quite reach breakeven next year, let alone this year.
Allocate Software (LON:ALL) - an recommended cash offer at 153.55p per share has been announced today. This is a 35% premium to last night's closing price - not particularly generous, but a bird in the hand & all that. Irrevocable undertakings to support the bid have been received from 47.1% of the shares held, so it looks close to being a done deal.
Having a quick look at the figures, it looks a fair price for a deal, so if I held the shares I'd probably accept the bid and move on, rather than try to fight it. Although if enough shareholders kick up a stink and refuse to accept the deal, it can sometimes extract a bit more money.
Right, got to dash. ShareSoc have asked me to do a 10 minute talk in a seminar this afternoon about improving shareholder rights, an issue that is close to my heart. So I need to prepare for that.
See you tomorrow!
Regards, Paul.
(of the companies mentioned today, Paul has no long or short positions.
A fund management company with which Paul is associated may hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

14 comments
If you have absentee owners, management run wild. Agree. Below is parable about Mr Demimonde that I wrote, within an article about Neil Woodford selling his HSBC shares.
"My grandfather owns a farm in the fertile East Anglia region. One day, Bob Demimonde, who has an MBA, knocks on his door and offers to professionally manage the farm for him. Mr Demimonde offers to improve the management of the farm, with new fertiliser to increase yields, sale and leaseback of farm buildings, derivative trading in the commodity markets, quarterly reporting and a complicated options scheme that rewards management. Ten years later it turns out that someone Demimonde hired has been using banned chemicals as pesticide, the sale and leaseback buildings are falling apart, the derivative trading was rigged, the quarterly reporting was misleading, yet Mr Demimonde has earned tens of millions from the incentive scheme. Meanwhile the value of the farm has fallen 70 percent because of the damage. The land will take years to recover. Bob Demimonde, who has earned staggeringly large sums of money from my grandfather, leaves the East Anglian farm to start a bank in Africa."
http://blog.lafferty.com/index.php/neil-woodford-sold-hsbc-shares/
Abolishing nominee accounts could be the way forward.
I understand the Singapore stock exchange operates some kind of electronic central repository. The shares can be bought, held electronically and then sold via a completely different broker, as chosen by the owner.
If the same central repository could manage an ISA wrapper, then the whole issue of ISA transfers is solved.
Finally, if the whole scheme was funded by a regulated & minute levy on trades, it could be quite economic.
Jeff
Couldn't agree more. Bogle (Vanguard founder / index hero) goes on about precisely this - the dual agency issue in his excellent recent book - The Clash of Cultures - these issues are a rot at the heart of capitalism. Let me know what ShareSoc propose - we will back all initiatives here.
I have accounts with Alliance Trust and Savings and Hargreaves Lansdowne, and both charge a fee for giving you permission to attend, and vote at a company AGM in your own right.
Boohoo.Com (LON:BOO) Interestingly Boohoo.Com (LON:BOO) qualifies for James Montier 'Cooking the Books' S… (in Short Selling).
View Screen on Stocko'
Paul,
I use TD and Hargreaves. The former is superb for voting as they automatically send email reminders of upcoming AGM/EGM's/, and there is the option to vote online for each company. Not checked the downloading of accounts option - but then I sue TD Pro as well so have access to Hemscott bits n pieces. Nor is there, as far as I am aware,a charge for voting in those instances where their platform doesn't support a specific company unlike many other bookies.
Hi Paul
Like jraitt I seem to get all the information I need including rights to attend AGM's and vote I think. I am with TD Waterhouse.
Is it possible that rather than the system having to change, that the system is there if one chooses the right broker? So if you want the rights maybe it is a question of choosing the right broker? So possibly it is the brokers not providing the service to cut costs?
Paul,
What rights do nominee shareholders not have?
My shares are held in nominee accounts at Barclays Sockbrokers and Halifax. Both of these send to me by post details of all Corporate activity, AGM,s and EGM's with letters of representation to attend and proxy forms should I wish to vote but not attend. Accounts etc can be downloaded from Company's website. You only have to request and to renew request every 5 years - not too onerous. What am I missing?
Best wishes - keep up the great work
John
John,
That's fairly unusual, and to obtain your shareholder rights, you have to make an effort.
It should be automatic for everyone, and quick & easy to vote electronically.
I never get any shareholder info or voting forms from my brokers, and don't have time to chase them up.
The whole system needs modernising, so that all shareholders can easily participate in shareholder democracy. I imagine that the vast majority of private shareholders are like me, and never vote on AGM resolutions, as it's too much hassle to get past the nominee system.
Regards, Paul.
John could you tell us who are your brokers?
Paul/purpleski,
purpleski - my brokers are shown above.
Paul,
You, David and Sharesoc are doing a great job for the private investor particularly in cases where the Directors are acting in a manner not in shareholders best interests. In these cases we will vote and support you. At most AGM,s there are no issues for the PI's to fight and so very few read the reports to know and understand the issues to make their votes meaningful. You are doing so much to help PI's to get interested and to learn - that is the most important thing. That will make Companies take more care.
You say I made an effort - I sent one email to each broker and it was done as part of their service.
By the way I saw you tweeted that you saw some value peeking out. Any chance of updating your GARP spreadsheet
John
"My shares are held in nominee accounts at Barclays Stockbrokers and Halifax. Both of these send to me by post details of all Corporate activity, AGM,s and EGM's with letters of representation to attend and proxy forms should I wish to vote but not attend"
His brokers would seem to be Barclays and Halifax
Thanks
Could not agree more on your point about shareholder rights (in nominee accounts).
This issue should have been addressed years ago but there is absolutely no excuse now in this day of easy electronic communication for this to remain as is.
If Scotland was given the vote, then why not shareholders within nominee accounts?