Small Cap Value Report (15 Oct 2015) - ZYT

Good morning!
The market mood certainly seems to have changed lately - small cap growth stocks are forging ahead, and it seems that investors are now prepared to pay up, often very high PERs, for growth companies.
I was discussing this with a broker friend this week over lunch, and he pointed out that a PER of 20 might seem high, but actually it's an earnings yield of 5%, which is enough to pay a twice-covered divi of 2.5%, and for a company that is growing strongly organically, those numbers will improve each year. When practically everything else is expensive, or ex-growth, then a 5%, growing return (half of which is paid out, half reinvested in growth) is actually not bad at all, in an era of ultra-low interest rates.
However, it won't look quite so good when interest rates go back to normal (if they ever do!), so it's difficult to know how to handle things.
Zytronic (LON:ZYT)
Share price: 337p (up 10.9% today)
No. shares: 15.3m
Market cap: £51.6m
(at the time of writing, I hold a long position in this share)
Trading update - there's excellent news today from this specialist manufacturer of touch screens (for things like cashpoints, vending & gaming machines);
Further to the outlook statement made with the interim results on 19 May 2015, the second half showed an improvement in revenues over that reported for the first half. This was particularly marked over the last quarter, resulting in a 13% increase in total revenues for the year above that reported for 2014.
The improvement in revenues, together with the continuing benefits of the production efficiencies and capital investments, as reported upon at the time of the interim results, have resulted in the Board expecting pre-tax profit for the full year to be materially ahead of market expectations.
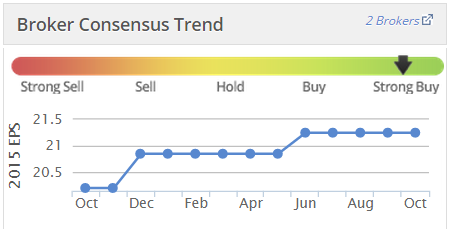
Materiality is usually described as 10% or more. It's interesting to see that broker(s) have been edging forecasts up this year, so clearly the company has been doing well for a while - this graph is often a good indicator (but not always);
My opinion - I like this company, and am pleased to continue holding. It's still good value, and there's nice growth potential from the larger, and curved screen which the company has developed. On the downside, there can occasionally be a gap in the order book - order visibility is quite limited. That's just something investors have to live with - but the dips have historically been good buying opportunities.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

10 comments
Ref Alternative Networks
You promised comment on this company earlier in the week but it seems to have slipped through the net. Can you update?
Re PE of 20x being OK.
Aren't you basically saying the worst possible phrase?...
"It's different this time"
If one needs to justify a PE of 20 by talking about 5% earnings yield, 2x divi cover of 2.5%, low interest rate world etc etc doesn't that suggest one is falling victim to a cognitive bias? The bias that makes you actively look for factors that perhaps confirm your viewpoint and make you start to ignore the obvious i.e. that the company at that level is just plain expensive. I'm probably wrong, but accepting that 20 is the new norm seems dodgy to me, whatever the supposed growth prospects.
I was also happy to read this morning's trading statement from ZYT. I first bought this company when I started using Stockopedia's ranking system as a primary sieve (it was then ranked at 98). I liked the company and its products (a dangerous thing to do with investments) and bought it together with FRP and GVC. The result so far is excellent, though GVC has yet to come right. I continue to hold all three.
Ref SMHW (WH Smiths)
They seem to be going great guns.
I am expecting to see a new Broker note something along the lines of.
Forget the internet and technology of everything for the next big thing WH Smiths have found the magic formula with Adult colouring books. We are upping our price target from 4 * earnings (400p) (terminal declining market segment) - to new super fad Sector - at 25* earnings - 2500p.We genuinely believe that if current Adult colouring sales growth rates of 6,500% managed last year is maintained for the next 25 years then the company will have sufficient reserves to buy Apple in an all cash deal. Note as part of this announcement if the share price does his 2500p we may be at that time possibly be shorting this share.
Paul,
Re your comments on a pe ratio of 20 for growth stocks, I tend to agree that they are OK provided that the Company has a competitive advantage that can be expected to continue.
I think your comment: "However, it won't look quite so good when interest rates go back to normal" is too pessimistic. Getting back to normal will surely include a degree of inflation, which tends to be associated with higher interest rates and may even be a precondition. This allows companies to raise prices to some extent "because everyone else is doing so". That means 2.5% growth in production can translate into say 4.5% growth in revenue (and so hopefully profits as well).
worries me all this talk of how a pe of 20 is reasonable !
sounds to me like people accepting that is a sign that the markets are toppy.
and while you can sell it, especially while interest rates are low, when that changes, the equation as to whether you want to risk your capital for a 2.5% return may change.
Sure if it's a growth share, and the peg is low, then it's justifiable, but we need to try to keep a cool head,
and not get carried away with soaring valuations.
There comes a time where if you buy in, you have to keep a very close eye on it, at some point the market will turn, and suddenly high pe fast growth shares might become low pe, ex growth shares, the market can be harsh on that kind of share.
K
K
first quote "worries me all this talk of how a pe of 20 is reasonable !"
second quote: "Sure if it's a growth share, and the peg is low, then it's justifiable, but we need to try to keep a cool head,"
forward PEG for ZYT is 1.03
That's fairly cheap by today's market standards.
If results will be materially ahead, we'd expect upward further upward revisions for future earnings, bringing the PEG still lower.
Therefore I think you have answered your own concerns re: valuation?
Interesting to see that MRR is added to the list of IPOs that have gone wrong. It's announced it will de-list today despite only listing at the start of the year!
Hi Paul, interested to hear how your meeting with Proactis Proactis Holdings (LON:PHD) went yesterday.