Small Cap Value Report (16 Dec 2014) - MYSL, OPAY, REDD, AVS, 888, GVC

Good morning.
I'm taken aback by just how far & fast MySale (LON:MYSL) has fallen from grace. As reported in yesterday's report here, the company issued a nasty profit warning, due to flat sales in its core market. Just look at the chart below - it's crashed from about 175p to only 73.5p in a little over 24 hours.
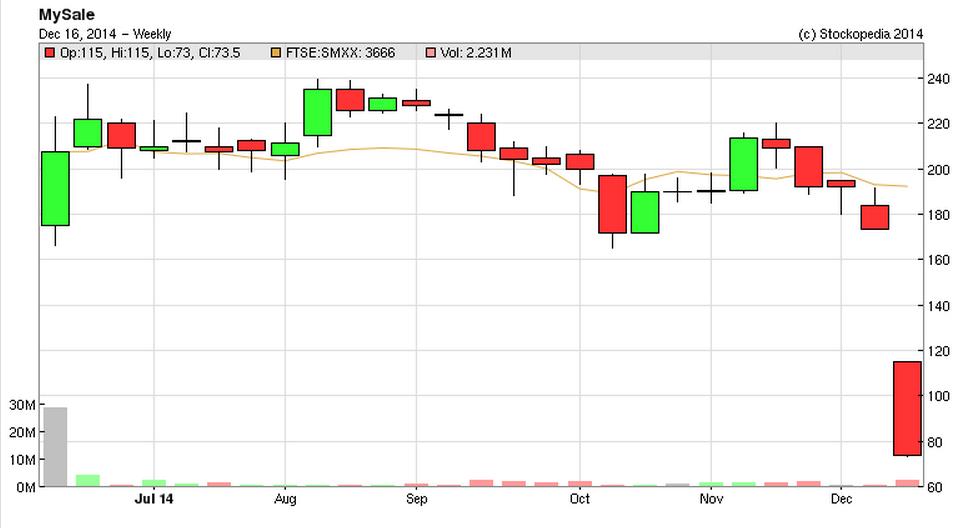
With 150.6m shares in issue, I make that a market cap of £110.7m - still hardly a bargain, although it did report cash of £33.5m yesterday. Am not sure what level I'd start to take an interest - possibly sub-40p? I'm convinced there will be plenty more large falls from over-priced early stage growth companies - it very rarely pays to chase fancy valuations in trendy sectors, especially when a lot of the hype rests on having a big name backer - that's no guarantee of commercial success.
Optimal Payments (LON:OPAY)
Share price: 324p
No. shares: 162.6m
Market Cap: £526.8m
This stock is a bit larger than the usual stuff I look at, but I must mention it as extreme volatility has once again hit the company - which could be either a worry, or a buying opportunity, depending how you look at it.
I've marked on the 6-month chart below two events which triggered a substantial fall in share price. The first one was when news broke of the CEO having used the now discredited EFH facility to sell/buy back part of his personal holding, which was dressed up to look as if it was a purchase of shares, to uproar from investors (rightly so!). There were about 5 companies where Directors did the same thing, and their share prices were whacked to varying extents.
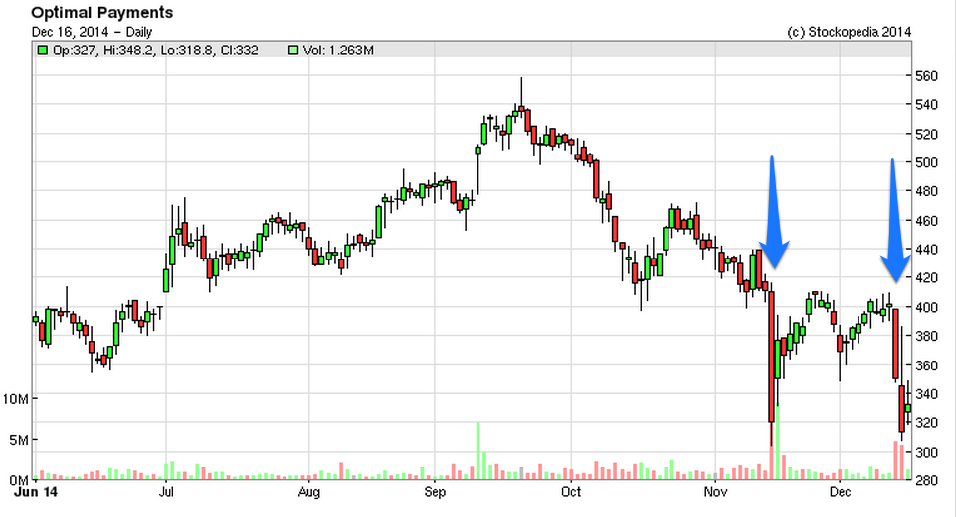
A number of people, including myself, saw this as a buying opportunity, and it was a successful trade, as the shares almost immediately recovered by about 20% over about a week, in late Nov 2014. The company issued a positive trading update at the time, which helped propel the shares back up again.
Well, a similar thing has happened again! It was announced on Friday that the CFO is leaving. That can rattle investors, especially (as in this case) where there has been some other cloud over the company. People start worrying whether there is something amiss behind the scenes which led to the CFO resigning?
Although in this case what is interesting is that a new CFO has been appointed, and the old one is staying on as a consultant until 31 Mar 2015. That suggests to me that the change was planned, rather than spontaneous, and that there probably isn't anything awry, given that the old CFO is staying on.
Trading update - furthermore, the company has again obliged with a positive trading update today, as follows;
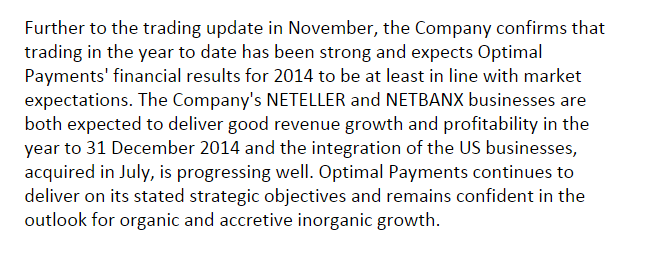
As other companies have discovered this year, when you put out a positive trading update after every wobble in share price, it does become subject to the law of diminishing returns!
However it's difficult to argue with this one, and hence I am once again leaning towards treating this as a buying opportunity. A change in the CFO surely does not justify a drop in share price from 400p to 320p?! Barring any unforeseen bad news, I suspect these shares might well recover again. We shall see.
Redde (LON:REDD)
Share price: 79.3p
No. shares: 385.3m
Market Cap: £305.5m
Trading update - very strong, see the "materially ahead" of both expectations and prior year;
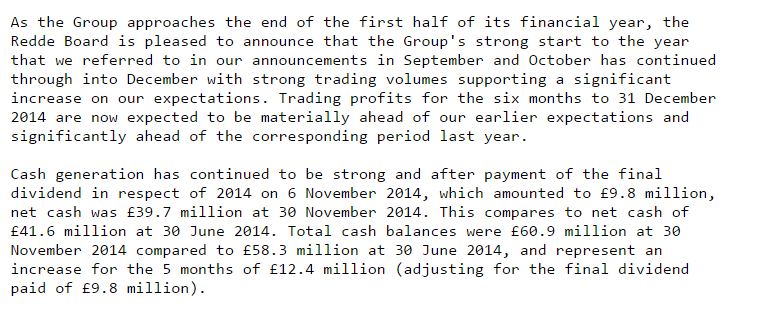
This ambulance chaser seems to have made it work, and is strongly cash generative, and paying good divis - the forward divi yield is over 7%. The Balance Sheet is strong too.
Perhaps they are picking up new business as a result of the high profile meltdown of a major competitor? Anyway, the figures all seem to stack up here very nicely, if you can cope with investing in this sector.
Avesco (LON:AVS)
Share price: 111p
No. shares: 18.9m
Market Cap: £21.0m
Trading update - announced today reads very well, with the key excerpt reproduced below;
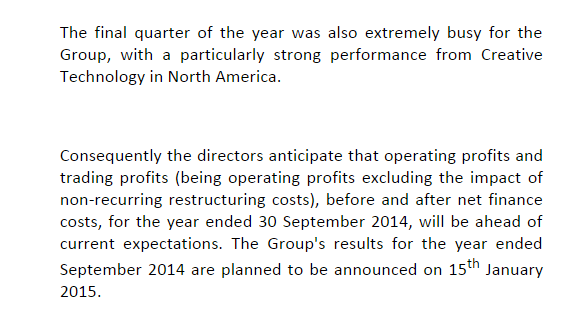
Valuation - So "ahead of current expectations" is the crux. Stockopedia shows broker consensus as being EPS of 18.3p for the year ended 30 Sep 2014, putting the shares on an extremely cheap PER of just 6.1. Before we get too excited, I should point out that the company has alternate year profit surges, due to particular events which happen every two years (the company provides staging & other equipment for outdoor events).
Dividends - note the excellent progression in divis in recent years. 6p is forecast for this year, which would put the shares on an attractive (and growing) divi yield of 5.4%.
My opinion - I hold a few of these in my long term portfolio, and like the shares for the divi yield, and the turnaround potential, which seems to be going well. Results are due out on 15 Jan 2015, so I'll report back then with more detail. The bid/offer spread here is nasty, and the shares are very illiquid unfortunately, but it looks a good company in my opinion.
888 Holdings (LON:888)
Share price: 138p
No. shares: 354.4m
Market Cap: £489.1m
Trading update - the company today says it is trading in line with expectations, for full year adjusted EBITDA. I wonder how that translates into profit?
I'm giving online gambling companies a wide berth at the moment, until the regulatory/taxation position becomes clearer for UK operations. As demonstrated in the past, there is always scope for big regulatory upsets, so this sector can be a bit of a minefield.
I note there is a 3.8% (i.e. fairly good) divi yield here.
GVC Holdings (LON:GVC)
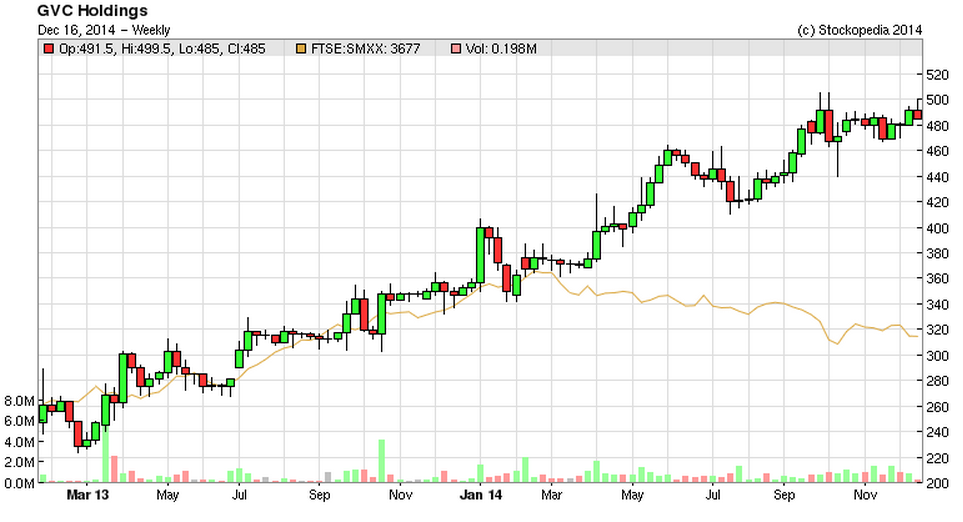
There's a positive trading update too from this online gambling company.
They expect to at least match full year expectations for 2014.
Note that there is a remarkable 8%+ yield, and the PER looks good value too.
Although the company does note the imminent "point of consumption" tax change in the UK, and the fact that 2015 lacks a major sporting event such as the World Cup, thus reducing likely bets by customers I suppose.
Interesting to note that the shares still look cheap, even after a very good run in the last two years;
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

15 comments
This is a good question - but one that the company should be able to answer quite easily? There are other issues which concern me from the "outsourced" business model. The main issue is that these companies pay a claim on behalf of the insurance Company and then proceed to work for many months in order to try and get some return?
Apart from the huge drain on cash there is an unquantified level of risk here that there might be little return. As a PI, this lack of visibility of earnings and open ended cash requirement renders these companies largely uninvestable.
If such companies do hit the jackpot and manage to find a very profitable niche, the next question is will the Insurance Companies seek to renegotiate their contract? It has to be remembered that giants like Aviva etc. are many times the size of Redde and Quindell and clearly hold the whip hand in any bargaining position.
For the same reason I don't see how a claims handler working on behalf of (and reliant on) these Insurance Companies can suddenly pop up as someone working on behalf of the claimant. How exactly do you go about claiming against a company that also might be your biggest customer? Quite bizarre.
To my mind the size and profitability of these claims handling companies depends entirely on how large and profitable the Insurance Companies are prepare to let them be. Very similar to being a supplier to Tesco. If they don't like what you are doing there are many ways to squeeze you into submission.
It would be most interesting if Redde could present at Mello and offer some clarity and reassurance on the above points.
I see OPAY is down 11% this morning - any ideas why Paul?
Questor article says 'sell'
For those of you interested in the Redde debate... (at the bottom of the RNS)
Founded in 1992 and working predominantly with insurance companies, insurance
brokers and prestige motor dealerships, the Group provides a range of accident
management and legal services. The Group also deals directly with large
national fleets providing incident management and mobility continuity. In
February 2014 the Group acquired the NewLaw group of companies, primarily based
in Cardiff and Bristol, and the Group's activities now encompass a range of
legal services designed to assist claimant parties in partnership with leading
insurance companies, brokers and other bodies.
The Redde group of companies is one of the market leaders in its fields of
business; it delivered accident management solutions to over 115,000 motorists
in 2014, ensuring that they remained mobile until their own vehicles were
repaired or until they were put in a position to obtain a replacement and it
provides legal services to over 30,000 claimants a year, ensuring they are
properly compensated for their injuries and losses.
The name Redde is associated, in Latin, with the concept of restoration.
I guess the key question is...What percentage of turnover and profit is actually derived from the proportion of the 30000 claimant cases that are due injury compensation and may be challenged rather than automatically provided for by the insurers ? In other words is the client of Redde the insurer looking for outsourced assistance or an insured individual looking for a specialist claims handler ??
The latter could take much longer to be profitable if at all...
That said I am invested in Redde but would like to meet management so I feel a Mello appearance in the early new Year would be useful.
David
Paul, thanks for explaining, I thought Redde mainly were involved in car hire and repairs, if it's personal injury claims then that is different and yes one I would avoid.
I think that there is a subtle distinction here. My own view is that any company who gets a tip off about an accident via dubious means (police backhander) can legitimately be called an ambulance chaser.
If however you own insurer instructs you to use one of these companies then I am not sure that ambulance chaser is the correct phrase to use.
Re Redde, I had a look at them used to be Helphire, provides hire car and car repairs following accident, if that is so, I think Paul's comment is a bit misleading, so I presume NARS is very similar. The rival he refers to I presume is qpp which I believe is somewhat different?
herbie47,
Nationwide Accident Repair Services (LON:NARS) is a chain of car repair workshops. So they're not ambulance chasers, they just repair cars.
Redde (formerly HelpHire), Quindell, and others, are essentially personal injury ambulance chasing firms - that's where the bulk of their profit comes from. They have various other bells & whistles, but their core business is intervening between individuals who have had accidents, and the insurance companies, and charging the insurance co for various services provided to the person involved in the accident.
I don't see why this point has been contentious, it seems pretty obvious to me what their activities are. "Ambulance chasers" is just a loose term given to any firm that involves itself into situations where there has been an accident & injury.
Regards, Paul.
AVS might be on a PE of 6.1 today, but they are forecast to be on a PE of 36 in 2015!?
Hi Paul, any thoughts on Synety's latest product announcement - Cloudcall Chrome? Seems to have been well received thus far by reviewers and investors alike.
Come on Paul,
You know perfectly well that Redde are not just 'ambulance chasers' as you so disparagingly put it.
Hi sminers,
I don't really understand the sensitivity over describing Redde (LON:REDD) as ambulance chasers? That's how I would describe the whole sector that they operate in - i.e. companies which get involved after an accident, to make money from providing various services (e.g. car hire, submitting personal injury claims - very big business in whiplash particularly) & getting payment from insurance companies.
Regards, Paul.
Paul, interesting comments re: the EFH arrangements. Fortunately never held shares in Quindell, but had a very small hoodng in IGAS which I subsequently sold. It's such a red flag - you have to question the integrity, honestly and, let's be honest, the judgement of any CEO or board member entering into such arrangements.
The market rout has served up such interesting bargains amongst quality companies that, personally, I don't see the need to trawl the bottom feeders of the stock market to get a bargain!
Re Digital Barriers. I am in principle wary of placings with the purpose of patching up balance sheets. It is the case of treating a rash and not the cause of a rash.
Paul
Interesting placement at no discount by Digital Barriers (LON:DGB) today (I'm neither long nor short), to cover current trading losses and "strengthen balance sheet" whilst delaying break even for a further year.
Throwing good money after bad, by current shareholders?