Small Cap Value Report (16 Feb 2016) - SFR, TRI, HSP, TRCS, FTC

Good morning!
Here's an interesting snippet for you - in the US, between a survey of CFOs found that they believe 20-30% of listed companies "intentionally misrepresent" earnings.
That range sounds very much in the right ballpark to me, based on my work interpreting financial results. Also bear in mind that CFOs are the guys who prepare the numbers, so they know what to look for.
So we all need to be very careful when valuing companies on a multiple of adjusted, pre-exceptional EBITDA! (not that any readers here would be so daft!) Chances are the figures have been manipulated in some way, and hence we will be led towards over-valuing the shares. Therefore it's very much worth checking all those footnotes, and valuing companies on traditional, un-manipulated figures perhaps?
Possible changes to corporation tax - interest deductions
I tend to be so busy scrutinising company results, that sometimes I miss forthcoming important changes to laws, taxes, etc. So I'm particularly grateful when people flag up important issues to ponder. Roger Lawson recently posted an excellent blog on ShareSoc's website, asking "What's spooking the commercial property market?".
In this article he outlined how changes are afoot to possibly restrict the amount of interest charges which companies can deduct against profits when calculating their corporation tax liabilities. Roger says;
According to the FT article, it is possible the Chancellor will not allow interest costs in excess of 30% of EBITDA to be allowed against corporation tax. Potentially this could affect any companies that are highly geared or have large assets which are financed via debt.
I have therefore done a quick review of my portfolio, to make sure there are not any companies that might be affected by it - by comparing the P&L interest charge with 30% of EBITDA. The only share that came close for me, is Enterprise Inns (LON:ETI).
In this case, the highly-geared pubs group last reported EBITDA at £296m (before exceptionals - it will be important to see whether or not the tax proposals allow adjustment for exceptionals?), and the P&L interest charge (before exceptionals again) was £158m. So I make that a 53% proportion - well over the likely 30% maximum - suggesting that ETI is likely to see its corporation tax bill increase significantly. This could well explain why its shares are down 30% YTD.
Overall, this proposal is an excellent idea - the morally bankrupt scourge on society that is Private Equity has been shamelessly abusing the tax system for years, creating convoluted corporate structures, loaded up with debt, in order to eliminate completely (or drastically reduce) UK Corporation Tax liabilities.
Therefore these new proposals should hopefully be creating widespread panic in PE circles, as they see their "tax planning" (i.e. ripping off society by not paying their fair share for public services) on a massive scale, hopefully collapse in ruins. I just hope that the new rules, when brought in, are not diluted through lobbying, and do not contain any fresh loopholes.
I investigated the accounts of Caffe Nero in May 2014, to (try to) get to the bottom of how they managed to avoid paying UK Corporation Tax - basically via a convoluted structure involving Isle of Man & Luxembourg companies, and tons of debt within the group.
One corporate financier commented to me recently that "every potential deal that comes to me now is structured like this" - i.e. using carefully created debt instruments to eliminate tax liabilities, by moving profits to low, or nil tax jurisdictions.
The UK Government's consultation document on this issue is simple to read, and sets out the points very well - here. Unfortunately the deadline for commenting has passed, but it's still worth a read. In particular they summarise the key principle here;
We now have a globally competitive tax system but we expect companies to pay the tax they owe, and to make a fair contribution to restoring stability to the public finances and reducing the deficit.
Overall then, the main target is tax avoidance by PE and similar financial engineers. However, it may also cause problems with highly geared companies such as Enterprise Inns (LON:ETI) mentioned above, and others, e.g. property companies.
When interest rates do eventually rise (when will that be, it seems to be pushed further & further out, as the debt bubble is pumped up more & more?), then more companies are likely to fall foul of the possible 30% rule on tax deductibility of interest payments. Although as the Govt points out, UK companies enjoy a very low corporation tax rate already, plus generous R&D credits, so really nobody can complain too much about interest payments being capped for tax purposes.
Severfield (LON:SFR)
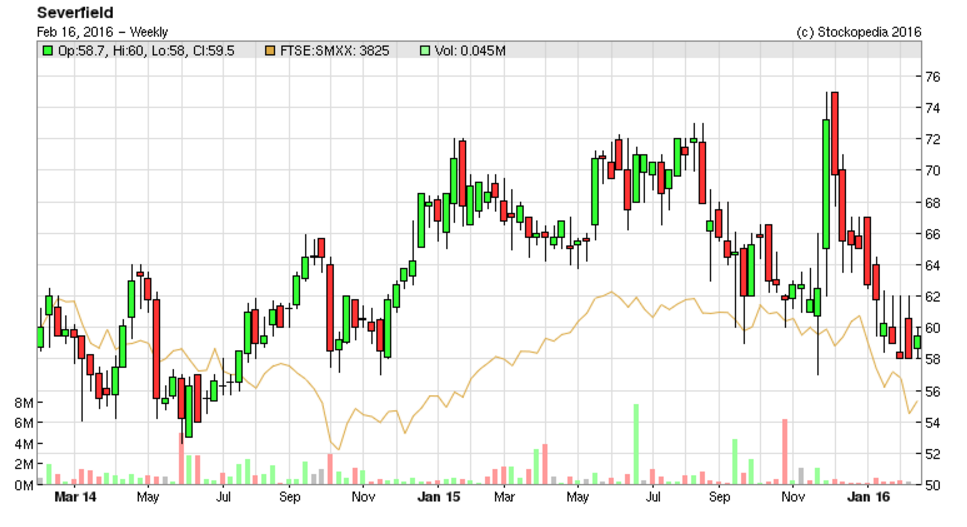
Share price: 60p (up 3.4% today)
No. shares: 297.5m
Market cap: £ 178.5m
Trading update - this looks fine, the company is trading in line with expectations;
The Group's trading performance and financial position for the year continue to be in line with management expectations.
Its year end is 31 Mar 2016, so it looks as if the numbers are probably now in the bag for this year.
Valuation - broker consensus is 3.4p EPS this year, putting the shares on a PER of 17.6, which doesn't look a particular bargain.
A 31% increase in EPS to 4.47p is forecast for next year, although given economic uncertainty, personally I'm now very wary of relying on forecasts that predict strong growth in earnings, as it may not happen. In a slowing economy, broker forecasts tend to be too optimistic.
Outlook - having said that, the outlook comments, and increased order book at Severfield do seem to support higher forecast earnings next year;
The UK business continues its good progress in a relatively stable environment and the current order book will enable continued growth in both revenue and margins. The Indian business remains steady despite a mixed economic backdrop. Overall, the group is on track to meet management expectations for the year.
UK-specific outlook comments overall sound positive, although note the caution re timescales slipping;
The UK order book of £246m (1 November 2015: £185m) reflects some significant recent contract awards from our pipeline of opportunities. Operating margin improvement is also continuing in line with management expectations, primarily from the internal efficiency benefits arising from the Group's operational improvement programme.
The market continues to present a good level of opportunities although as indicated in November's interim results, slippage in potential timescales still remains a risk as clients scrutinise forecast overall project costs with caution.
Balance sheet - this was repaired a few years ago, in a refinancing, following several years of losses & problem contracts.
Looking at the last reported balance sheet as at 30 Sep 2015, it looks alright to me. It passes my simple three tests;
1. Positive NTAV? PASS. NTAV is £83.2m, mainly fixed assets, as you would expect for this type of business, being quite capital intensive. I've checked the last Annual Report, and note that the group owned £66.0m in freehold property, so that's a hugely positive factor.
2. Current ratio over 1.2? - PASS. This was 1.32 at the last balance sheet date of 30 Sep 2015. In any case, I would be flexible on this, given the strength provided by freehold property noted above.
3. Net debt + pension deficit reasonable? PASS. There only seems to be £0.7m of interest-bearing debt (finance leases), and no bank debt at 30 Sep 2015, so absolutely fine. Note there is a £14.5m pension deficit, which does not look particularly onerous, although I would check the detail in the Annual Report before buying any shares, just to be on the safe side (that it's not an iceberg type deficit).
Overall then, I'm very happy with the balance sheet.
Dividends - not very good, it's only forecast to pay 1.0p this year, and 1.5p next year, although looking at the history of divis, it looks as if management are still being cautious following the financial difficulties and passing of the dividend a couple of years ago. So it seems to me that there's scope for divis to increase strongly over the next couple of years, especially considering the strong balance sheet now.
My opinion - I quite like it. My main reservation is whether we're getting too late in the cycle to look at investing in companies like this? Sure, it might have another couple of good years ahead of it, but what happens after that? In the next recession, this company is likely to be loss-making, so we need to be careful not to value it too highly on peak earnings.
There's a lot of activity in UK construction & infrastructure at the moment, and the next couple of years look likely to be buoyant too (based on upbeat comments made to me by the CEOs of both Waterman (LON:WTM) and T Clarke (LON:CTO) ). Therefore if the current global macro worries abate, then this share could have reasonable upside possibly?
It's not compelling enough to make me want to buy now, but with a strong balance sheet too (look at the £66m freehold property, with no associated debt - that is 37% of the market cap in owned-outright property), there's very good downside risk protection - this company probably won't need to do another equity fundraising in the next recession.
It's certainly a share which I will add to my watchlist, with a view to possibly buying some on any future plunge in price, maybe?
Trifast (LON:TRI)
Share price: 111.2p (up 1.1% today)
No. shares: 116.7m
Market cap: £129.8m
Trading update - this reads well to me. The key part says;
Overall, we are making good progress against our strategic objectives and we remain optimistic about the Group's prospects. Therefore, we remain confident of meeting our full year expectations for the year ending 31 March 2016.
It's interesting that Trifast sees the UK softening;
Whilst the UK industrial market has shown signs of some softening as we expected when we reported last November, our markets in both mainland Europe and Asia remain strong.
Other points mentioned today;
- Acquisitions are trading well
- "Sales enquiries remain brisk through our TR portal"
- "Our order pipeline remains encouraging"
- "...in negotiations with a number of multi- national OEM customers to extend the plants we service and to widen the product ranges we currently supply"
- "...continue to explore new geographic areas to broaden our reach and search for suitable acquisitions"
Outlook - overall sounds fairly upbeat to me;
Although global sentiment and the Brexit/EU debate might be influencing the current climate, and consequently impinging on economic confidence, from Trifast's own perspective, Group trading has not been unduly affected, however we remain diligent and far from complacent as we look forward.
Overall, we are making good progress against our strategic objectives and we remain optimistic about the Group's prospects. Therefore, we remain confident of meeting our full year expectations for the year ending 31 March 2016.
My opinion - the shares look reasonably-priced, and today's outlook sounds as if the business is pretty solid, and doing alright.
The balance sheet looks alright, with a bit of debt, but not excessive. There's a 2.4% dividend yield, but it's well covered (almost 4 times).
Overall, it gets a tentative thumbs up from me. Looks a good business, at a reasonable valuation. Although as with many things at the moment, macro worries are the main question mark over how we value it.
Hargreaves Services (LON:HSP)
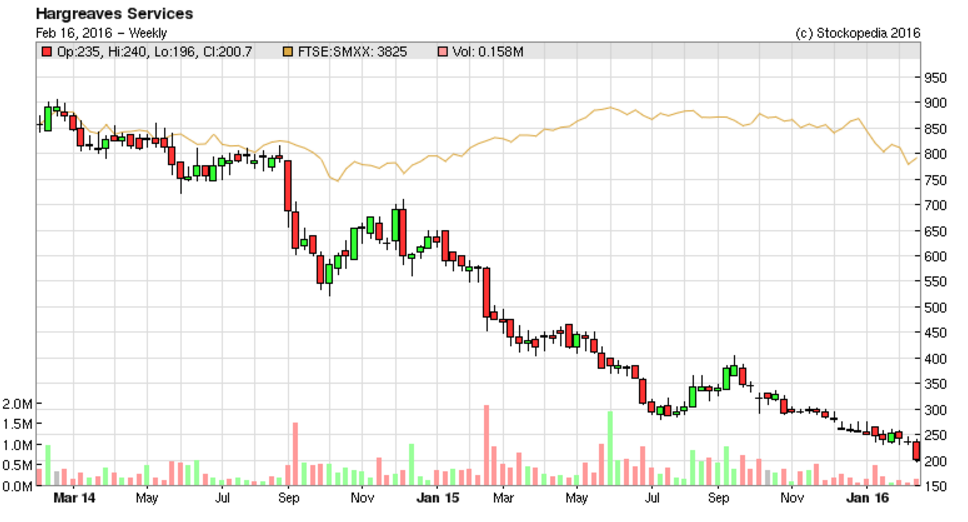
Share price: 198p (down 16.8% today)
No. shares: 31.9m
Market cap: £63.2m
Interim results - this is very much a special situation, as the core business (coal distribution) is effectively in wind-down, as coal is largely being phased out in the UK as a too-dirty source of energy.
Therefore, it's now impossible to value the company on a PER basis - good job too, as profits has collapsed. Continuing revenue dropped 50.2% to £174.8m in the 6 months to 30 Nov 2015. Underlying operating profit dropped 81.3% to £4.1m. So we can largely ignore the legacy coal business, and just hope it doesn't make too large losses in the future.
The shares are now about 3 elements;
1) remaining activities, after coal has largely disappeared
2) value on the (strong) balance sheet as working capital turns into cash
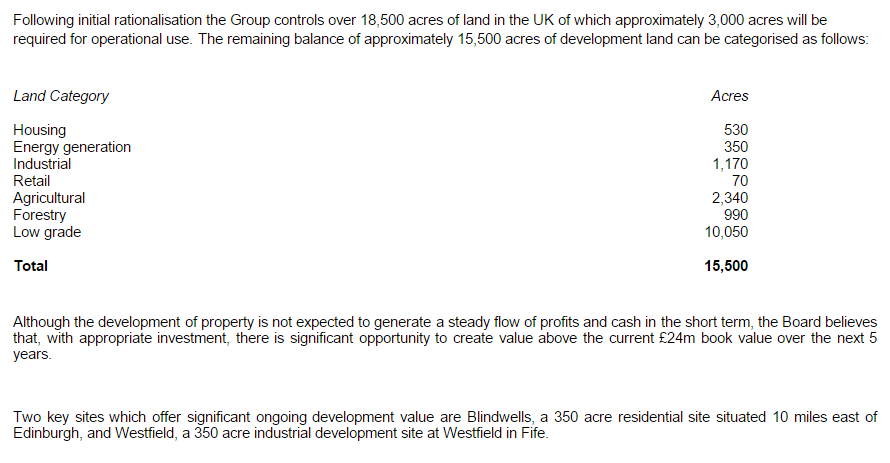
3) property development assets - HSP owns a substantial amount of land, and there is medium to longer term development upside on this;
Set against this, the downside risk is of unexpected losses from closing down its legacy operations, and any other liabilities that might come out of the woodwork - I suppose the nightmare scenario would be some kind of legislation or legal action to slap punitive damages onto Hargreaves, for environmental damage caused by the burning of coal.
My opinion - it's just a question of crunching the numbers, for all the various moving parts. My back of the envelope figures suggest that there might be some quite good (maybe 50-100%?) long term upside on the current valuation.
I've assumed that working capital turns into cash without any major problems, and that intangibles are worthless, and that fixed assets might have a realisable value of half book value. Plus a bit of potential upside from property.
Therefore, it's worth a look, if you're a special situations investor. It doesn't excite me, because there's an opportunity cost with tying up money for (say) 5 years, in the hope of getting an uncertain 50-100% return. I'd rather be recycling money into shares that can make a decent gain much more quickly.
As you can see from the 2 year chart below, people who thought there was hidden value in the shares so far, have not been well rewarded.
Note that management has quite a big stake, so interests are well aligned for them to extract value from the group. So it could be an interesting one long-term, but my instincts tell me to stay away for the time being. I'd want to see a stonking bargain, to justify tying up money for several years, and with material uncertainty over the outcome.
Tracsis (LON:TRCS)
Share price: 465p (down 5.6% today)
No. shares: 27.3m
Market cap: £126.9m
Trading update - covering the 6 months to 31 Jan 2016.
The key part looks good to me;
Given a good start to the financial year, the Board is confident the Group is well placed to deliver full year results in line with market expectations and remains vigilant to changing market conditions.
Perhaps the last five words might have spooked some investors, possibly explaining the 5.6% fall in share price today?
Net cash was £8.0m at 31 Jan 2016, still very healthy, even after acquisitions have been paid for.
A few other points are noted, including that group seasonality has changed, since the recently acquired businesses are highly geared to H2 trading (this will be the outdoor parking marshals business, I presume). I don't think there is anything at all to be concerned about there.
My opinion - Tracsis management has executed faultlessly in recent years, and it's clearly a mostly good quality group of businesses. The market has rewarded that performance with a fairly rich rating.
Overall I'd say the shares look priced about right to me - not cheap, but based on performance to date, and management quality, and the cash pile, the premium valuation seems justified.
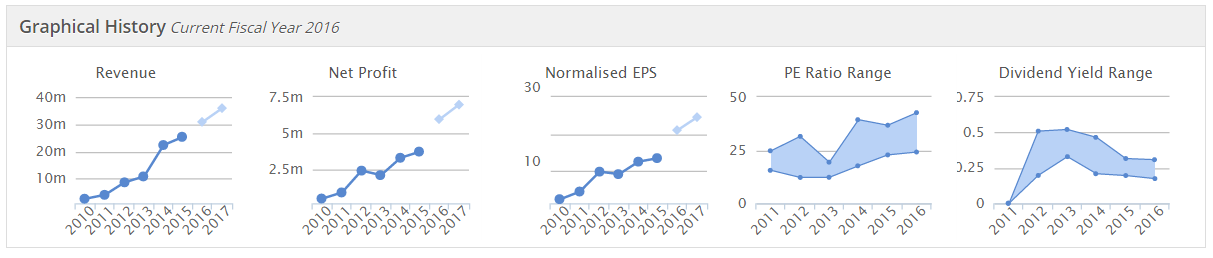
EPS forecast is for 21.1p this year, and 24.6p next year, giving a PER of 22.0 and 18.9 respectively. There's no scope for anything to go wrong at that kind of rating mind you. On the other hand, TRCS shares have always looked a bit expensive, but the company has grown into the valuation, with a very nice progression in profits over recent years:
Filtronic (LON:FTC)
Share price: 5.5p (down 6.4% today)
No. shares: 216.9m
Market cap: £11.9m
Interim results to 30 Nov 2015 - these are terrible numbers. Revenue is down 38% to only £4.5m in H1. The operating loss (before exceptionals & amortisation) was £4.1m. To my mind that just is not a viable business. Shareholders very kindly refinanced it with £5.0m fresh cash in Nov 2015, but perhaps it might have been wiser to let it go under?
My opinion - the shares are now just a complete punt on new products/orders, combined with cost cutting, being enough to turn the company around from the hopeless position reported in these interim numbers.
I can't see any reason to take the risk here. It went on my Bargepole List in Mar 2015 at 13.8p per share, and has already lost 60% in value since then. I'd say there's quite a high risk that it will lose the other 40% too, in the coming year.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

22 comments
Bizarrely the Hargreaves management spent loads of dosh on buying up coal assets at a time when many were suggesting fossil fuel would be phased out. Seems like a bonkers approach to running a business.The ceo owns loads of shares as well. Very odd.
PS to the post above, many of the coal fired stations where I talked to the coal handling managers have indeed closed as they predicted, and a few more are now winding down.
Regards.
I found your take on Hargreaves, a company that has been on my personal “bargepole list” for probably the last four years, interesting Paul.
The main justification for its “bargepole” status in my view is that I see no future for coal. Everyone knows that coal burning produces more global warming emmissions than other fossil fuels, as well as other pollutants, but its excavation and processing also releases methane which is twenty five times more damaging in this respect than carbon dioxide, a fact which you rarely see mentioned by enthusiasts of Carbon Capture projects. Nearly twenty years ago I talked to the coal handling managers of every coal fired power station in the UK about stockpile handling, and almost to a man they predicted closure of their coal fired power stations before, or around, now. Haven’t read Hargreaves recent reports, but I expect that they have a large element of coal stockpile value which may not be realiseable. But the cost of coalsite reinstatement ie. a serious liability, which was originally anticipated to be recovered in advance through profitable coal production which has now been cancelled, will still be required if the company is to survive. So I’m far from convinced that the wind down of working capital would produce a large benefit.
Also, recently HSL bought C A Blackwell, which didn’t impress me at all, as I’ve dealt with both in the past and fail to see any synergies, or much chance of the staff of the two companies integrating painlessly. It reminded me of one or two companies I’ve known in the past desperately trying to change the nature of their business, unsuccessfully.
And finally, I noticed the bit in your report about the land holdings. I’m sceptical about their potential, just as I was perhaps ten years ago when shareholders in UKCoal were enthusing about the huge (half a billion £ IIRC) potential from their vast landbank. HSP own, IIRC, loads of opencast coal sites, many of which closed perhaps fifteen to twenty years ago, which probably represents most of their landholdings. The ones I particularly remember are Dalquandy, which was the Crouch operated biggest opencast mine in Scotland, Blindwells, a Fairclough Parkinson site near Edinburgh, and Westfield which was originally a Costain site and the deepest opencast in Europe I believe. On opencast sites there are usually quite large areas reserved for offices, overburden heaps, soils heaps, coal handling etc. – perhaps as much as 30% of the overall site area. This portion of the land is clearly ideal for any type of development. But the remaining 70% or more has huge variations in the depth of backfill it contains as well as the type of backfill, method of replacement, settlement time since it was reinstated (not forgetting that many of these coal sites ran for twenty years or more), and whether or not any attempt was made to compact the backfill as it was placed ( not usual) which will have a huge bearing on the value of the land to a developer. So, have HSL actually sold any of that sort of land to developers, or are they just getting planning permissions etc. and ”hoping”.
Regards.
Re your starting comments on taxation liabilities, I find your general comments almost as interesting as your comments on individual companies. I would like to add to this particular one wiht the following comment, in my local newspaper The Isle of Man Examiner dated 9.2.16 re Cafe Nero. CN asked for a letter to be printed under the heading We Dont Have An Entity On The Island. 'CN itself has never used any overseas (nonUK) entity in the Isle of Man or anywhere else to reduce UK taxable profits, whether that be throguh any tax reduction on interest or another mechanism. All reports in the press stating otherwise are categorically inaccurate and a complete misstatement of the facts.' It does say that it has 'shareholders from many parts of the world including some of whom are based on the Isle of Man' and so presumably cannot speak for them or their actions, but it confirms that ' it does not have a corporate entity on the Isle of Man. Contrary to reports on the press, CN neither now nor in the past has any of its corpoarte structure in the Isle of Man', How you sqaure that with your comments, I leave up to you.
I pay some attention to the regular comments about the Isle of Man - I cannot speak for other offshore jurisdictions - in the UK especially. I rarely hear about the no doubt thousands of schemes operating in the City of London and elsewhere in the UK, nor about the lack of transparency in the UK in direct contrast to the recent direct actions of the Isle of Man to come up to speed with world leaders in transparency. The UK recent (and to me disgustingly inadequate) agreements with major international organisations on tax liability eg some little time ago with Goldman Sachs, more recently with Starbucks and Google, make the pursuance of smaller organisations and individuals seem trifling by comparison - but of course they are the soft underbelly and relatively easy pickings for HMRC and make good press.
However, methinks he doth protest too much. I would be interested to see how you square off your comments on your analysis on Cafe Nero and links with the Isle of Man and Luxembourg with the letter I have sent to you above.
One final point if I may. Having just been through the Isle of Man budget statement 16.2.16, the Island (and its 84k population the vast majority of whom are pretty ordinary lime anywhere else in the British Isles) the Island is still suffering from the actions of the UK Exchequer immediately post the crash in 2008/9. The first and most important was the unilateral reduction by the UK of the Manx share of the shared VAT agreement with the UK of £200m in 2 tranches - equivalent to almost 1/3 of IOM government revenue. Yes, £200m, and yes 1/3 of the annual budget! The second was much shadier. Kaupthing (Icelandic) Singer and Friedlander (British) - a bank bought by the Icelandic spending spree some years before - was stopped from sending all its assets to Iceland by the UK, using the Terrorism Act! However, the funds of the bank were protected only for UK investors, with some deal arranged with a Dutch Bank. The £600m lent by the IOM branch to the London HQ for investment purposes was deemed by Mr Darling and team to be foreign funds for which the British government was not responsibie. It took many years and a huge amount of IOM Government time for a scheme to be set up to repay all the deposit holders.
Just a few thoughts! Thanks again for all your useful contributions which I use regularly in my investment plans.
The whole debate about people & companies paying their taxes only looks at one side of the equation.
On the other side we have:
1 Governments who are notoriously poor allocators of capital. Whatever they buy or interfere with will cost much more than it should & provide less benefit that it should. e.g. HS2, the NHS, Nuclear Power stations.
2 The finance director (Mr Osborne) think's it's just OK to borrow over 5% of his budget every year. His predecessor, Mr Brown borrowed up to 11%. These idiots will bankrupt the country eventually.
The presumption always seems to be more money going to the government is good, whilst ignoring the question of whether or not they are competent to handle it.
I would argue that they are not competent to handle the money & we would be better off with lower taxes and lower spending.
Paul
Thanks for bringing the potential tax changes to our attention. And yes, good luck to George Osborne in getting the private equity boys to pay their fair share of tax, though I wouldn't put it past them to have their next wheeze ready to cheat the Revenue.
But there are some industries that need higher levels of debt. You mentioned property companies. Financial companies - banks, companies providing car purchase loans, etc. also tend to run with very high levels of gearing, making their money on the turn between the cost of borrowing and the cost of lending. Are these expected to be exempt? If not, this could kill some of them. Barclays e.g. has a net gearing of 231%
For the record I don't hold any of the banks but do hold (very successfully so far) S&U whose net gearing is a more modest 45%
Julian
I know Severfield Rowan well but not a holder currently.
I would not put too much reliance on the property aspect as two major units are in rural North Yorkshire (Dalton and Sherburn) with very large specialised buildings and probably difficult to easily be used for other activities or to get planning permission for housing on any volume..
Digital Globe Services (LON:DGS) reported "The Board is pleased to report that the strong trading in the second half of last year has continued into the first half of the current financial year, with the Company delivering year-over-year, double-digit revenue growth, gross margin in excess of 30%, and an Adjusted EBITDA* margin in the double digits. Group revenue is expected to be in the range of US$22M - US$24M, an increase of at least 13% over the same period last year (H1 2015: US$19.5M). EBITDA is expected to be between US$2.2M - US$2.4M, an increase of at least 400% (H1 2015: US$0.5M). The revenue and EBITDA achievement represents the Company's strongest H1 performance to date as the Company heads into its typically stronger second half. "
It's the dreaded "adjusted EBITDA", of course. But maybe the fall after the profit warning was overdone, and some bottom fishing might be profitable?
Trifast management is deluding itself if it thinks it has a strategy. It follows where the world's winds blow.
Filtronic has been a basket case for last few years. recent announcements of small orders are just crazy. Time to kill the horse.
Sorry to be negative, but let us be realistic.
I am no PE fanboy (generally avoid their IPOs like the plague) but it must be said that they *do* provide value when they buy up companies and successfully leverage them. Basically they provide value to company vendors by outbidding everybody else for the company, and they provide additional value by using only a small amount of equity capital to turn around and then "flip" a company. Since the equity slice is small, then a marginal improvement in the value of the business (and thus their stake in it) can generate a huge IRR for them. Using a small equity slice each time means they can work on improving the value of multiple businesses at the same time, which is actually a good thing for society.
Obviously there is a big risk to jobs and to the company itself by increased leverage, but the PE playbook is well known, it's hard for outsiders to judge how much leverage is truly appropriate, and in the end being a company owner means being able to capitalise it as you see fit.
One way of looking at it would be to say that if the PE owner chose not to get involved, then the original owner would be equally capable of decapitalising it themselves by taking out special dividends, by breaking it up, etc. It's either that or just sell the whole thing off completely. If the original owner doesn't want to continue capitalising it themselves, then ultimately nothing can force them to.
I think what contributes to most of the annoyance about PE is the feeling that their IPOs are generally overpriced, so that their financial success is far greater than the value they generate. This is almost certainly true but who's to blame? Surely the buyer who keeps falling for it bears just as much responsibility as the seller - aren't the institutional investors and the individuals who overpay supposed to be "sophisticated"!
These are likely to be unpopular views which will result in getting thumbs down! Oh well.
Ultimately though it's not an attack on private equity. It is an attack on the use of extreme levels of debt to avoid taxation.
The debt is needed to capitalise the company in the absence of equity.
Tweaking the tax treatment of various financial instruments available changes neither the total stock of capital nor the underlying investments. If interest repayments were taxed the same as dividends, and capital gains, as they should be, you'd probably just see more equity structures, plus a net gain due to some people moving from tax structuring to more productive jobs. Main issue here is it's hard to change without international coordination.
Thoughts on Hargreaves - $HSP? thoughts on blindwells valuation
Hi Paul
i hope you will have time to comment on tracsis as it is down today
I've never heard of this proposal - can anyone advise how to calculate EBITDA from the stockopedia income figures? Enterprise's £296m is in their accounts but I can't reconcile to the stocko figures...
I assume the corporation tax changes will not affect REITs as they are exempt from corporation tax on the profits and gains arising from their property investment business?
I don't disagree with the sentiment expressed regarding corporate tax so long as the companies who employ large numbers of people who in turn collectively pay substantial amounts in tax and NII are not put off from coming here and investing in the UK.
Or that they stop coming here and muscling out firms that pay their tax?
ken,
The problem with PE companies is that they buy existing UK companies, but then re-engineer their balance sheets so that they no longer pay tax. So the PE guys don't generally bring any new jobs to the UK, they just hijack existing companies, and squeeze out their corporation tax liability - so a major net loss to the UK economy.
Then there's the slightly different issue of large US corporates setting up operations in the UK, in such a way that they don't pay any UK Corp Tax.
As the UK already has pretty much the lowest Corp Tax rate in Europe (apart from Ireland?) then the UK should remain an attractive destination for inward investment. We can then argue about whether possible Brexit might be a short term problem, but a long term gain, who knows? Let's not get onto that issue, as it's too political for this site.
Regards, Paul.
Thanks Paul,
I would like to see it all come to an end but unfortunately most government interference causes untold problems down the line, when I say most government I mean all parties, If Nissan Toyota Jaguar (Tata ) and BMW along with many other household names weren't here we would be in a mess. Most of these companies were given incentives to rescue the plant, or start it up, as in the case of Nissan's phenomenal success in Sunderland. If companies are rescued and jobs are saved we should be willing to forgo the CT (if any) for a period of years as compensation for the risk taken by the investors. Tax avoidance comes from sloppy poorly thought through legislation, and lazy tax officials who always attack the low lying fruit, you and me. That's it I shall stop now as I can feel another Polish invasion coming on. Well not Poland particularly but it is time for my medication.
Paul
I hope you are planning to comment on Digital Globe Services (LON:DGS) and Tracsis (LON:TRCS) today.