Small Cap Value Report (16 Jun 2015) - FLOW, ENTU, AXS

Good morning! I'm back in the UK, but didn't get home until 4am this morning, due to a delayed flight, so might have to curtail this report a little, depending on how things go.
ED Investor Forum
A diary note for Wed 24 Jun (next week) - it's the next Equity Development private investor forum. The companies presenting are Staffline (LON:STAF) , Cranswick (LON:CWK) , and OptiBiotix Health (LON:OPTI) .
The hospitality is always good at these events, but on this occasion a little bird tells me that Cranswick will be bringing along samples of their products for investors to try.
It's the usual venue behind Oxford Street tube, in central London. The booking page is here.
The biggest faller of the day so far is;
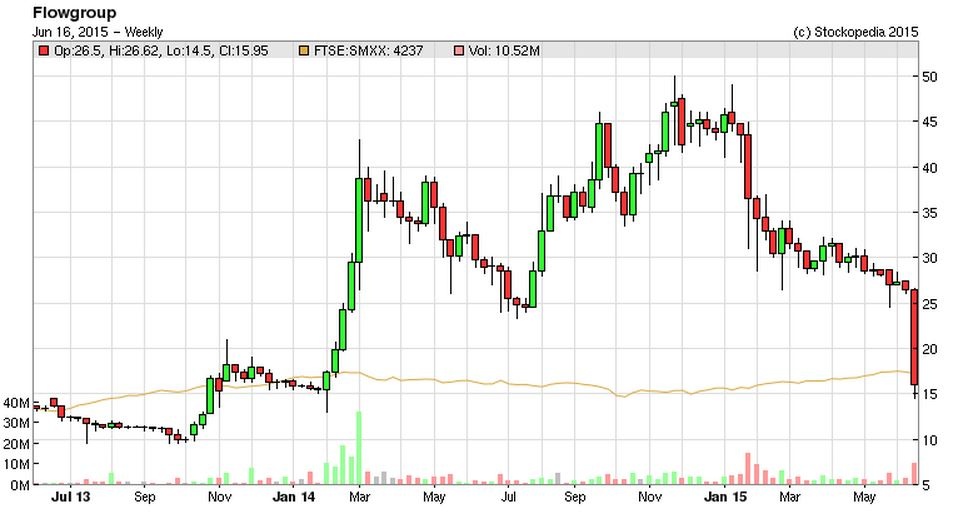
Flowgroup (LON:FLOW)
Share price: 15.4p (down 37% today)
No. shares: 317.5m
Market Cap: £48.9m
Update - this company is trying to commercialise a new type of domestic boiler, which produces electricity at the same time as heating radiators. Today's announcement is really a stroke of very bad luck for the company - the European Court of Justice has ruled that the UK's lower rate of 5% VAT for energy saving products is illegal. This seems a perplexing judgement, given that one of the EU's biggest priorities has been pushing member states to improve the environment, and reduce energy consumption.
It's surprising that the stock market had apparently not noticed this announcement, despite it being reported widely in the press on, and shortly after 4 Jun 2015. Flow today says that it will have a significant negative impact on them;
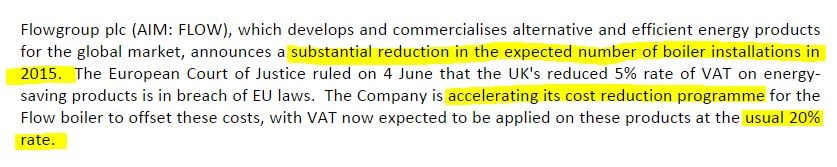
This is clearly a serious blow, as the final price to consumers will now rise by 14.3%, due to VAT being charged at 20% instead of 5%. Given that the product was already more expensive than conventional boilers, this additional cost is undoubtedly going to hit sales, as the company suggests.
Although the cynic in me thinks that the company would have struggled to commercialise this technology anyway - it's so difficult to dislodge existing, tried & tested technology in any field. So maybe this VAT bombshell provides a convenient excuse for disappointing sales?
Cost reductions - Flow says that it will accelerate its focus on driving down the cost of production with its outsourced manufacturing partner, Jabil, in an attempt to offset the VAT rise.
Government stance - doing a bit of googling, it seems that the UK Govt has not yet responded to the ECJ's ruling. There is some suggestion that the ECJ ruling could be circumvented by the UK, if the Govt reclassifies the purpose of the lower 5% VAT rate. Alternatively, the UK Govt might increase subsidies for energy efficient products, to offset some or all of the impact of higher VAT.
So it sounds as if the position is fluid, and if the UK Govt does what it should do, but so rarely does - i.e. play the game like everyone else in Europe does, and get round the EU rules, instead of slavishly following them to the letter, then maybe FLOW might possibly regain some benefit from the lower VAT rate?
Financial position - reviewing the accounts for 2013 and 2014, FLOW burned about £9-10m p.a., and had net cash of £6.2m at 31 Dec 2014. However, it raised an additional £22.2m before expenses, so perhaps £21m net of expenses, in May 2015. Timely! Therefore it looks as if the company has adequate cash resources for the next, say, two years. That should be long enough to determine whether this project is commercially viable or not.
Directorspeak - the CEO's comments today make it clear that this is a serious blow, and not something to be brushed off lightly;
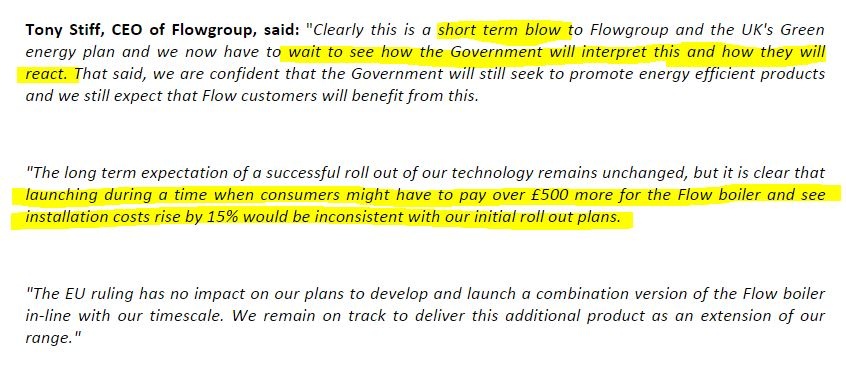
My opinion - I looked into the economics of the FLOW boiler earlier this year, and came to the conclusion that it didn't really stack up, at least not convincingly enough to make it worthwhile for owners of larger houses to take the risk of installing a completely new type of boiler. The cost savings look a bit manufactured to me - i.e. perhaps more about clever marketing, than actual savings?
To my mind, the company has invented a solution to a problem that doesn't exist, because conventional boilers are already so efficient, and relatively cheap, that it's difficult to see why anyone would seek out an alternative.
The market cap is still nearly £50m, which doesn't strike me as a bargain, given that this project is commercially unproven, and has just been dealt a hammer blow by the ECJ with this VAT ruling.
There again, people who are convinced that the product is the best thing since sliced bread, and think that the VAT issue might be circumvented, could see this as a buying opportunity perhaps?
It's another reminder though that virtually every blue sky stock that comes to AIM either ends in total failure, or at best will take years longer, and consume far more cash than originally planned, to achieve the original business plan. If investors were rational, we would just stop investing in this type of stock altogether, as risk:reward is so absolutely dire - they nearly all fail! Yet many of us love a good story, and with endless optimism we get sucked into a few of these story stocks each year, and undermine our overall investment performance accordingly.
Some of my friends are in this stock, so I'm sorry (but not surprised) to see that, so far, it hasn't worked out. Still, the company has no immediate cash worries, so it lives to fight another day.
EDIT: I see that Entu (UK) (LON:ENTU) has been marked down about 5% in sympathy with FLOW, since it is an installer, and also sells other energy saving products. However, on checking the Govt website, it transpires that Entu's main products, double glazing & conservatories, are already taxed at 20% VAT, so the impact of the VAT change on them are likely to be limited.
Accsys Technologies (LON:AXS)
Share price: 70.8p (down 5% today)
No. shares: 88.8m
Market Cap: £62.9m
(at the time of writing, I hold a long position in this company)
Results for y/e 31 Mar 2015 - this is an interesting growth company, which sells the "Accoya" and "Tricoya" wood products. The market seemed unsure how to react to the results, as there was a sharp spike down in the first hour of trading today, down to as low as 57p, but the price has since largely recouped those early losses.
The full results announcement is a whopper, and published in a frustratingly tiny font for the narrative. It's too small for me to read comfortably on the computer, so am having to print it off in landscape, which comes to 60 pages. So this afternoon will mostly be going through the detail with my highlighter.
A quick snapshot of the headline numbers though;
Revenue - up 38% to E46.1m for the year (to 31 Mar 2015). This is ahead of forecast shown on Stockopedia of E43.5m.
Underlying EBITDA - has improved from a E5.0m loss last time, to a E2.4m loss this time. More encouragingly though, note that H2 was close to breakeven, with a E0.4m loss.
Underlying loss before tax - has reduced from E7.5m to E5.0m, so some progress, but still negative.
Financial position - loss-making companies are fine, as long as they are heading towards profitability, and are not going to run out of cash before they get there!
In this case, I've reviewed the balance sheet and cashflow, and it seems to me that the company should be fine. It had E10.8m in cash at 31 Mar 2015, down from E15.2m a year earlier, but importantly, there were no equity fundraisings during that whole two year period. Therefore Accsys seems to be doing a good job in having raised the cash it needs, and operating within its budget. I like that.
A smallish top-up fundraising is a possibility, but with good growth & strong demand for the product, I reckon it would be fairly straightforward to top up the coffers with a say E5-10m placing, if needed. So that's not a worry for me. The expansion plan seems to be revolve around out-sourcing production to partners such as Solvay, which is building a manufacturing plant for Accoya in Germany. There is another deal with a large international chemicals group to build a Tricoya plant.
Outlook - all sounds upbeat. The company says it will "build towards becoming cash-flow positive in the year ahead, and longer term, achieving profitability" - cleverly worded, so it doesn't actually say they will be cashflow positive this year!
Supply constraints - what is most striking in the narrative, is the potential market size for these products, which is many times current production levels. The main issue at the moment is supply constraints. The existing Arnhem factory has a production capacity of 40,000 m3 p.a., whilst sales in 2014/15 were 33,483 m3, so there is not much additional headroom to increase sales in the short term.
However, once production by partners ramps up, then things could start to look very interesting.
My opinion - most growth companies struggle to convince people to buy their products. In this case, it's the other way around - they can't make enough of it! That's a quality problem to have, in my view, because over time it can be fixed.
Therefore this share seems to have passed from being overtly speculative, into being a play on how well management are able to manage growth. The cash burn is modest, and there doesn't seem to be any need for additional equity. Broker forecasts are for a small profit this year, but it's what happens after that which intrigues me, once the bigger third party factories come on stream.
Overall, my view is that this stock has the potential to be a multi-bagger in several years' time. In the meantime, it looks reasonably priced to me, given the potential. Certainly out of the two growth stocks I've written about today, with roughly similar market caps, I think Accsys looks a far better investing proposition than FLOW, in terms of likely risk:reward. That's just my personal opinion, and you may have a different view, which is fine - feel free to add comments in the comments below.
Trifast (LON:TRI)
Share price: 129p (up 1% today)
No. shares: 116.2m
Market Cap: £149.9m
Results for y/e 31 Mar 2015 - shares in this industrial fastenings group had been bouncing around above & below 100p over the last year, but have recently made a push higher, to 129p. That looks justified, when reading the results published today.
I've only done a quick review of the main numbers, and it looks good to me.
Underlying diluted EPS - drops out at 8.68p (up 45.9% on prior year), which looks to be ahead of analyst forecast of 8.09p, assuming that the forecasts are prepared on a comparable basis to the reported EPS. Note that there are some separately identified items, which mean that basic EPS is lower, at 7.39p.
So a really strong result, although note that the company is making acquisitions, and has taken on some debt to fund them, so that helps boost the growth figures.
Net debt - is reported at £13.4m, versus net cash of £2.0m a year earlier. This level of debt looks fine to me, and is not a worry. There doesn't seem to be a pension deficit, which is good.
Overall the balance sheet looks fine to me, no issues there.
Dividends - a 50% increase to 2.1p for the full year, but coming from a low base, so the yield is only 1.6%. The company comments that it intends paying divis that are 3 to 4 times covered, so it's effectively retaining most of its cashflow for expansion. Given that this strategy has worked well so far, then I think this policy makes sense.
Outlook - this sounds mostly upbeat, with a note of caution about macro factors, which is fair enough:
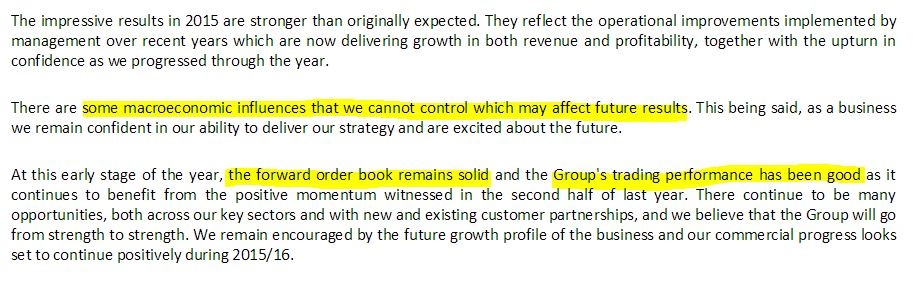
My opinion - this looks like a well-managed business, that has been performing well for several years now. I like the comments in the narrative about their customers streamlining their supplier bases, to fewer, but good quality suppliers.
The recent surge in share price looks justified in my view, and I would say that these shares look priced about right for now at 129p, which looks to be about 14 times current year earnings estimates. However, if they keep out-performing, and making sensible acquisitions, then there could be continued longer term upside in these shares.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

22 comments
Re Flow some investors are very unhappy, not about the 20% VAT but about they are now saying only 500 boilers this year when before it was 15,000, seems like they are using the VAT as an excuse.
Accsys - just looked at their web site and video. What an amazing product. I have strict filtering rules on buying stocks but might bend them for this co.
People love the look of wood for windows but it requires a lot of maintenance. Accoya has a 25 year external guarantee and a 50 year internal one. For external architecture, decking, windows - even bridges - the market is massive.
I haven't got any feel for prices from distributors though - I suspect there isn't much supply at the mo - and therefore I expect the product to initially expensive?
I must say the EU ruling on VAT does seems bizarre, they want us to cut carbon emissions but now they are saying VAT must be 20% on items like solar panels that will cut carbon emissions, baffling to say the least.
This has nothing to do with carbon emissions as such. The judgement is based on a pure technicality: EU VAT legislation does not allow reduced rates except for a specific list of things, and the UK tried to use a loophole and get away with a reduced rate for something that's not allowed by pretending it was something else that is in the list. Basically the UK broke the law and got caught.
The alternative to breaking the law is to get it changed: in this case the UK can suggest adding this to the list of exemptions (a proposal which may well be accepted, hardly any member state is against energy saving!) or maybe campaign for abandoning the aim of VAT convergence altogether. Or alternatively, subsidy energy saving kit through other means, there's plenty of legal ways to do it.
I see, thanks for explaining. Could we not just exempt it from VAT?
paul - I know it is not your brief -but as you are hearing Cranswick presenting today - I would be grateful for your thoughts- I am a very happy holder for the last 4 years.
danyou,
Cranswick are presenting at the ED Investor Forum, which is next week - on Weds. So if you can get into London, you can see them present & meet management yourself!
I've seen them before, and was impressed - seems a solid company.
Regards, Paul.
With free trade and movement of goods with in the EU, if one country could set a particularly low rate of VAT for certain products then that country could take a lot of the sales for that particular range of products and distort the market.
Not looked at flow group specifically, so I can't comment, but gas is much cheaper per kw than electricity, and the by product of generating electricity through some form of boiler/generator is heat. If there's a feed in tarrif, so you can sell excess electricity back to the grid at peak times while heating water for the next morning, that sounds like something that should stack up, all depending of course on the cost of the boiler/generator device. I also agree that there is a significant risk re a new device, Boosch periodically give 5 year warranties on their devices, plus if it fails after that, while its a supported device they do fixed fee repairs.
Not sure that's something you would get on a new and relatively untested device.
As Paul say modern boilers are pretty efficient, I wonder how efficient these things are at making electricity ?
I guess as part of a package with solar panels, where you disconnect from the electricity grid altogether, these might make sense as there would be some saving there, but from memory standing charge is 20p ish per day so it wouldn't be a big saving and it would have to be offset against the loss of any feed in benefits.
K
Hi Paul,
Hope you may have a chance to cast your eyes over results from Trifast today. Look very strong to me.
Not shocked to see that the Flowgroup boilers are not particularly energy saving - as they aren't. Like you say Paul, if the European Court rule that they do not constitute as energy saving then that surely says something given their stance on reducing carbon etc. In my view Flowgroup have marketed these boilers as something which they are not and it is very difficult to see a good economical case (especially now) for installing them in your home. I can see with the literature they produced it could be easy to be sucked in to the story, but again like you it just doesn't stack up for me.
Because the UK is part of the European Union.
Hi Stepone
I assume this was a reply to me and to some extent I get that but on that basis why does the European Union not set the rates for:
- Income Tax
- Capital Gains Tax
- Corporation Taz
- National Insurance
- Petrol duties
- Other duties
Kind regards
Michael Broom Smith
I know this is off topic so I will make it my last comment on the EU VAT debate.
In 2014, VAT receipts represented over 17% of all taxes collected by the UK Government. And what I have just found out is that this is not entirely under the control of the Chancellor of the Exchequer. It seems that Brussels rules OK, openly and covertly.
"why does the European Union not set the rates for..."
Because the EU is partly funded by a fraction of VAT receipts collected in each Member State. So if we cut VAT, we cut our EU contributions. To prevent a country deciding to cut VAT to zero on everything (and hence cutting its EU budget contributions) there are restrictions on what can be done with VAT. More detail here: http://www.parliament.uk/briefing-papers/sn02683.pdf
The same considerations don't apply to other taxes. There have been arguments about the 15% rate of Corporation Tax in Ireland (alleging that it runs counter to the single market) but the principle has prevailed that governments are free to set all other tax rates as they see fit.
Couple of things Flowgroup (LON:FLOW) has a stockrank of 6 so this would be a complete non starter for me.
Secondly slightly off topic can anybody explain why it is for the European Courts to set VAT rates in the UK? VAT is a completely internal tax.
Good question, purpleski. I got this answer from wiki:
"
The European Union value added tax (or EU VAT) is a value added tax on goods and services within the European Union (EU). The EU's institutions do not collect the tax, but EU member states are each required to adopt a value added tax that complies with the EU VAT code. Different rates of VAT apply in different EU member states, ranging from 15 to 27%. Some of the VAT collected by member states is used to fund the European Union as part of the system of "own resources".
"
So we can set our own income tax rates, etc but VAT rates need to comply with EU directives. Bonkers, if you ask me.
Thanks. I am generally a pro EU (anti Euro) but I waver and this sort of thing makes my blood boil.
No doubt the government can, if they want to, get around this with grants for energy saving products but of course would bring a whole load of extra bureaucracy.
Paul, Will this have a material impact on Entu (UK) -their shares have dropped somewhat in sympathy with Flowgroup...
Hi danyou,
Ha, we crossed in the post! I've just added a comment about Entu (UK) (LON:ENTU) in the main article, at the end of the section about FLOW - pls refresh the page. I see Epwin (LON:EPWN) is down today too.
Since Entu mainly sells double glazing, which is already rated at 20% VAT, then I imagine any impact on them is likely to be relatively minor. I've put a call in to the company's advisers to confirm, am awaiting a call back.
Regards, Paul.
Hi Paul,
Just following on from the link you have posted to the rules on reduced rate VAT - I am just trying to understand those rules to get a better idea of how this might affect ENTU's sales.
There is a line that says that to qualify for the reduced rate, you must be either over 60 or on benefits of some kind. Do you know if this relates to all of the products listed or is that specifically for the installation of heating systems?
If it does apply to all products, then it seems logical that ENTU are further mitigated from the effects of the change, as surely only a given % of sales (don't know the number but would have to guess a minority if pushed) are made to those over 60 or on benefits anyway.
Any thoughts?
Tom.
Hi Paul -
I also looked at Flowgroup (LON:FLOW) last year and concluded that the commercial proposition didn't stack up. However I must say that the VAT question wasn't even on the radar as a potential risk. Just shows that stuff comes out of the left field to knock you down, maybe not fatally this time..