Small Cap Value Report (16 Mar 2016) - ACSO, WAND, FRP

Good morning. My apologies for no reports on Mon or Tue - I'm not doing very well at the moment. Anyway, let's get this show back on the road, as there are lots of results to comment on today. I'll catch up with the backlog over the next few days.
accesso Technology (LON:ACSO)
Share price: 992p (up 3.7% today)
No. shares: 22.0m
Market cap: £ 218.2m
(at the time of writing, I hold a long position in this share)
Results y/e 31 Dec 2015 - the highlights look great - decent increases in all the main metrics. NB. remember that Accesso reports in US dollars - so it's frighteningly easy to forget that if you skim the numbers too fast, and mis-read the figures as being in sterling. I did that earlier this morning, and thought to myself, ooh it's only on a PER of just over 20. But of course once you translate 40.96c into sterling (currently £1 = $1.41) then adj.EPS is 29p, so the PER is actually very high, at 34.2.
So the main question is whether the company's growth potential justifies it being on what is undoubtedly a pretty aggressive rating. Personally I think it does, hence why I hold a long position in the company. The Merlin deal changed everything for me (that was when I bought in). There have been impressive subsequent deals announced too, e.g. with Six Flags, so there's really no doubt now that Accesso has become the most serious global player in its market. Although it's also worth bearing in mind that Disney is probably never going to become a client, as they do their own thing.
Here are the highlights from today's results announcement:
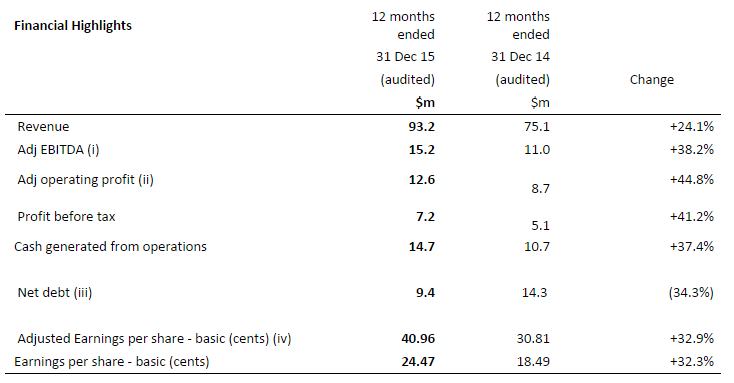
Impressive stuff. There should be plenty more growth to come, as the big Merlin deal rolls out to all their sites.
Directorspeak/Outlook - flags up impressive numbers of contract wins, and the long-term nature of the client relationships;
...92 new accounts comprising between them over 200 new venues being added to our customer base during the year.
The clearest signal of our progress lies not in the numbers, and not even in the many achievements of the year in review. Rather, I would urge people to look at the significant, long-term trust that both Merlin and Six Flags have placed in us over the last six months. To select a partner for one year, even two is a big step to take. To select a partner for seven or even ten years, however, is quite a vote of confidence in our technology and our team - and it is this which underpins my confidence in 2016 and the years ahead of us."
I think this is absolutely correct. If you look at the accounts from Merlin, there is considerable validation of ACSO in their own commentary, saying very positive things about it. So there's no doubt in my mind that ACSO is on an exciting growth path.
One broker flash note this morning comments that upgrades are now likely for 2016 & 2017 forecasts, and that the upward momentum in the share price should continue.
Dividends - there aren't any. That's fine for the time being - this is a growth stock, so people are buying the shares for capital appreciation, not income. Also the balance sheet is not strong enough yet to pay out divis.
Balance sheet - not great - I'd like to see this strengthened, to protect the downside. Although with revenue being largely recurring, over long contract lengths, then you could argue that there is little risk to the revenue/profit forecasts, so balance sheet strength isn't so important.
Net assets are $63.6m, but that's dominated by intangibles. So once the $71.9m intangibles are stripped out, NTAV is negative, at -$8.3m. Not ideal, but not a disaster either.
Bank debt is $14.7m, partially offset by cash of $5.3m, giving net debt of $9.4m. That looks manageable, given the profitability of the group.
New bank facilities - note the separate RNS yesterday, giving details of extended bank facilities, and warm words from the bank manager included in the announcement. So the bank are clearly very comfortable with things here, and in providing very cheap borrowing facilities, it looks as if the bank are very keen to be associated with this company - a nice position to be in.
For these reasons, I can live with the relatively weak balance sheet.
Development costs - note that the group seems to be capitalising a lot more in development costs - the cashflow statement shows that it capitalised $6.2m which is described as "purchase of intangible fixed assets" - I assume this is mainly development spending, i.e. internal costs.
The amortisation charge shown for development costs is much smaller, at $1.2m so the net benefit to adjusted profit is hefty, at $5.0m from this accounting treatment.
My opinion - on any conventional basis, this stock looks really expensive! So normally I'd run a mile from these sort of valuation metrics. However, in this case, I feel that ACSO is that very rare thing - a superstock - i.e. a company that is developing a unique niche, with a huge moat around it. So just looking at the PER this year & next is missing the point.
The point is that this is likely to be a very much larger business in say 5 years' time. Also, if you look at the >3% shareholder list, there are only 3 Instis in it, holding 18.8% in total. That's much too low - so I believe there is likely to be great demand for this share from Instis. This is backed up by what happened in the market sell-off we had in Jan 2016. Whilst many other small caps were tumbling, this one was remarkably solid. Why? Because Instis were hoovering up all the sellers. I watched the trades, and you could see it happening. The price should have been falling as small sells went through, but it didn't fall - as someone was in the background pleased to be buying up all the sells that came their way. This is very encouraging.
I read a book about superstocks last year, and it really opened my eyes to the potential, when you very occasionally find a genuine superstock. The trick is not to worry about valuation during the big move up. The Instis will have to bid the price up, to get hold of stock. After results like today's, I reckon this stock could have a lot further to rise, so personally it's the only stock in a virtual compartment in my portfolio marked "Ignore valuation for now. Hold".
CEO Interview - good news! Tom Burnet, the CEO of Accesso has agreed to do an interview with me on 22 Mar 2016. So please submit your questions using this link only please for me to ask Tom. I can't guarantee to ask all questions, but will do my best.
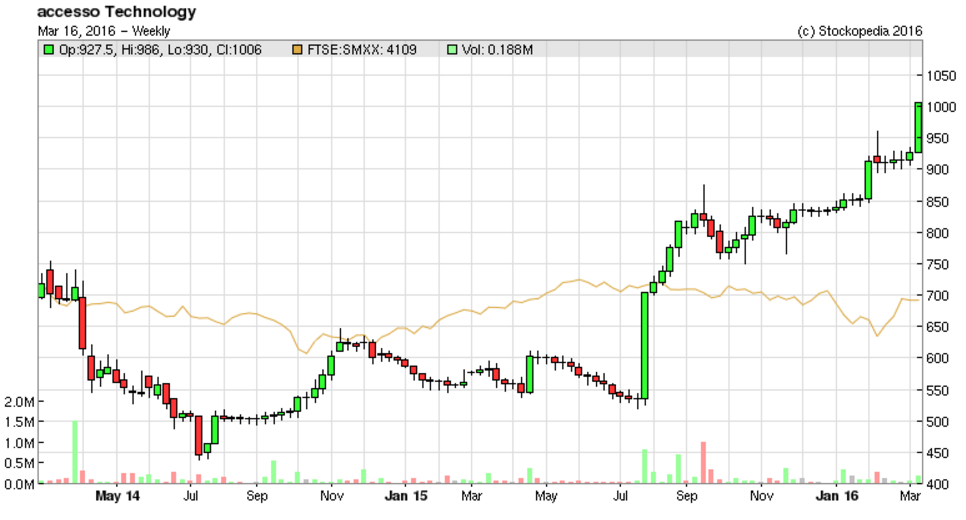
This share won't be
for everyone, and in particular, value investors will probably be taking me off
their Xmas card lists after reading the above! However, look what the share
price has done since the big contract announced with Merlin, which I flagged up
to readers as highly significant here on 30 Jul 2015;
WANdisco (LON:WAND)
Share price: 110p (down 21.4% today)
No. shares: 29.6m
Market cap: £32.6m
Let's go from the sublime to the ridiculous.
Results y/e 31 Dec 2015 - this set of results has got to be one of the worst I have ever seen.
A $30.5m operating loss, on revenues of just $11.0m. This growth stock didn't even manage any top line growth, revenue is down 1.8% against the prior year.
Worse still, it's completely out of cash - there was only net cash of $2.6m at 31 Dec 2015, so I doubt whether they will be able to make the end of March payroll. There's an undrawn borrowing facility, but I'm not sure what the terms are for the use of it.
The company says that cash overheads have been reduced to $25m p.a. at a Mar 2016 run rate, but that's nowhere near breakeven, with gross profit only running at $10m p.a..
My opinion - this is a total dog, and needs to be put down, in my opinion.
The narrative reads as completely delusional to me.
Let's see what price the next, imminent fundraising is done at. 50p? 20p? I suspect the company might get a few more months' money from investors, in return for an agreement to absolutely slash costs to the bone.
For me it's a total bargepole stock. The worst kind of story stock - which raised a ton of money, and then burned through it at a frantic pace, with nothing to show for it now, in the figures. What a terrible waste of investors's money. I'd be livid if my pension fund manager had backed this.
Fairpoint (LON:FRP)
Share price: 154p (down 5% today)
No. shares: 45.6m
Market cap: £70.2m
Results y/e 31 Dec 2015 - the figures look quite good - Stockopedia shows broker consensus of 18.4p, and the actual results today show basic adjusted EPS of 19.29p, so looks a beat against forecast. So I'm not entirely sure why the share price is down 5% today.
The outlook comments look OK - it's not news that the IVA part of the business is declining, that's been known for some time.
During 2015 we have delivered on our strategy to expand the Group`s consumer legal services (which now represents 67% of the Group`s revenue on a pro forma basis) and we continue to see this market as an area with significant growth potential in the future. 2016 will benefit from a full year contribution from the acquisition of Colemans and our integration, marketing and new product initiatives. In addition, we are targeting further value enhancing acquisitions to further consolidate our market.
We anticipate the market conditions in the IVA and DMP segments will remain challenging given the benign interest rate and employment outlook. We will therefore continue to focus on margin management and cash generation and expect these businesses to continue to make useful contributions to Group earnings.
As a result of the above factors, the Board expects to make good progress in 2016 and beyond.
On a PER basis then, the shares continue to look good value - I make the PER 8.0 times. That's perhaps the right sort of price, for businesses that don't really achieve high valuations - a declining IVA business, and legal services (which is now about two thirds of revenues, following several acquisitions).
Something always seems to go wrong with legal services businesses. Look at how Quindell imploded, but was bought out at a madly high price by Slater & Gordon, who have now themselves imploded - S&G share price has dropped in the last year from about AUS$8.00 to just AUD$0.29. The main reason seems to be that they totally screwed up the acquisition of Quindell, and overpaid by a gigantic factor, and have now been hit by Government action to clamp down on false whiplash claims - which was basically how Quindell made its profits, as I said all along.
Fairpoint reiterates today that it has only 8% of revenue exposure to whiplash claims, and that it mainly does fixed fee legal work, driving down the cost for end customers, using call centres to streamline the processes. So that kind of work doesn't sound toxic to me, indeed by doing things like divorces very much more cheaply, it might be a good thing.
Dividends - not bad, with a 6% increase to 6.8p for the full year.
Balance sheet - OK, but not brilliant.
My opinion - I'm not sure about this share. It's probably priced about right, on a PER of 8. Legal services businesses are cheap because they're not great businesses in truth. If they were, the owners wouldn't sell them cheaply, would they?
So you can't really expect an aggregator of legal services businesses to itself be on anything other than a low rating.
I've just realised the 2016 Budget is being announced now on Radio 4, so am listening to that now.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

34 comments
For ACSO Stocko was from memory showing consensus forecast EPS of 54c for 2016, now its 41c. Is this a data error or have forecasts dropped significantly?
It was 0.42 now 0.41
But 2015 came in well below the forecast of 0.35.
I do have a problem with broker forecast accuracy on some shares. They are not a bit out but miles out. Take St. Modwen Properties (LON:SMP) forecast EPS 2015 was -58%, came in at +80%.
Hi,
Sorry for any confusion over my use of the term "superstock". I was using it in the context that Mark Minervini uses it in his book - Trade Like a Stock Market Wizard. Yes, I know - the name of the book sounds ghastly, but it's a fantastic read.
He basically says that he looks for companies which exhibit qualities whereby an explosive move upwards in share price is likely, due to them having some product or service which is in great demand, and where during the take-off period the stock will look very expensive, and yet still exhibit strong price momentum. Yet this is often only at the start of another really major move upwards, because profits are set to shoot up from the rapid growth & operational gearing.
I believe that ACSO is part-way through such a move - so personally I think it's entirely possible that the stock could double again from the current level, and more, over the next say couple of years.
Maybe I won't use the term superstock again, as it has caused confusion today.
Regards, Paul.
Perhaps for this definition of Superstock we should read very high Quality and Momentum, where Value measures such as PER should be largely ignored. These are special companies with huge sales and profit growth potential with a competitive advantage which gives them a much higher than normal intrinsic Value. These are O'Neil Can-Slim type stocks that will keep going up in price over the medium term. I suggest these type of companies are maybe 0.5% of the stock market. That not to say good old Value should not be part of a portfolio mix too. I share the positive Burford Capital (LON:BUR) sentiments too. Ian
My understanding of FRP impairment charge following management's explanation this morning at the analyst results meeting is as follows.
Since 2009 the Group's IVA business has generated £28.8m of adjusted pre tax profit. Intl financial reporting standards require goodwill to be subjected to an annual test to the strength of the business, not amortised systemically. The IVA medium term outlook is challenging (inceptions in 2015 were at their lowest since 2008) and so, taking a 6 year view, the goodwill acquired with the Clear Start acquisition back in 2007 now transfers across. There is now only £2.3m IVA goodwill remaining, so a 'repeat' of this situation, would only be the tune of that amount.
If you would like to ask the management about this issue, you can do so tomorrow on a webinar which starts at 3.45. You can find further details and register at this link: http://www.equitydevelopment.co.uk/index.php?p=news Hope that helps.
I think what people mean by a "superstock" can be quite different.
Ed Croft's "Taxonomy of Stock Market Winners" uses the term "Super Stocks" to refer to stocks which score highly on all 3 dimensions of the StockRank scoring system: quality, value, and momentum. http://www.stockopedia.com/content/towards-a-taxon...
Ed wrote:
The term “Super Stock" was first used by the late, great Professor Robert Haugen in “ The Inefficient Stock Market". Haugen was the first to show that good, cheap, improving shares have a tendency to beat the market and we honour the great man by borrowing the phrase here. It can often go against one's instincts buying these kinds of shares as cheap stocks have problems, good stocks are boring, and stocks at highs are scary - this may be why they so often exceed expectations.
What Paul Scott is referring to by "superstock" is, I think, something different. It's a stock which is so good in terms of quality that it is a genuine value buy regardless of the fact that it has a poor StockRank Value Rank. The Value Rank and the ratios upon which it is based measure cheapness, not value per se; and a stock can be good value even if it is not cheap according to these ratios -- as Paul is maintaining is the case with accesso Technology (LON:ACSO).
If people can see the potential of such a stock (as Paul says the institutional buyers can see the potential of accesso Technology), it will have a high Momentum Rank. It will therefore fall into the category that Ed Croft terms "High Flyers":
These are the stock market stars, the ones that all fund managers want to be able to say they own. They tend to be very high quality growing stocks with a history of beating estimates, just don't expect this kind of stock to come cheap. Bill O'Neil's classic “ How to Make Money in Stocks" is one of my favourite books - he shows that if you want to own the really big winners in the market you'd better be willing to pay a premium P/E ratio. Amongst this category of stocks may lie some of the great multi-year compounders - just watch out, when the momentum finally turns these can easily turn into falling stars.
(Within the UK-only universe, accesso Technology (LON:ACSO) has an excellent QM Rank of 93, with a very low V Rank of 7. So the StockRanks system places it squarely in the "High Flyers" section of Ed Croft's taxonomy.)
Fairpoint have an interesting strategy and if you understand Judges Scientific -then imo this is not disimilar. Smaller law companies are often owned by a couple of partners who have no exit. They'll sell to a larger company to realise some value. They have a back book of repeat customers thats valuable but loyal.
Couple this with economies of scale and modern mangement...
Hi Paul,
Good to see you back. I have to disagree with your comments on legal services businesses, particularly the statement: "Legal services businesses are cheap because they're not great businesses in truth."
I couldn't disagree more - generally. A good legal services business is very profitable, hence why certain banks are so keen to provide loans to partner to buy into such businesses. Equally, it has only been in the last two or so years that a legal firm has been allowed to be owned by anyone other than the partners involved. As now, independent third parties can come in and invest in or buy legal services business, this is a fairly fledgling market and I would wager there isn't a 'typical' valuation for a legal services business at this point. Equally, you have legal services businesses at each end of the spectrum, some can charge what they want, some take what they can get.
Partners of law firms have now potentially got much wider access to the sort of windfall payment owners of normal companies have been able to get for years for acquisition of their business. I think some partners of law firms will see this as a chance to get a big contribution to a pension pot, without thinking if they are selling the business relatively cheaply or not.
Whether the particular businesses owned by Fairpoint (LON:FRP) are good quality or not, or as good quality as the most profitable legal services businesses, is a separate issue and Fairpoint (LON:FRP) 's valuation should only take the particular businesses into account.
I am a holder, and was actually relatively happy with the results this morning.
Ta
Chris
I agree I have always found legal services to be very expensive £ 200 per hour for very straight forward work, how much to write a letter? I only bought into Fairpoint (LON:FRP) when they changed direction last year.
Legal services are expensive, generally, although in line with similar accountancy, fiduciary services etc. I think part of the reason for the perception of the cost of legal services is (i) some hourly rates are very expensive, and (ii) a lay client thinks the work is only going to take X hours, without realising the extent of the work that is required.
If the management of Fairpoint (LON:FRP) can take good quality firms with a recurrent client base, and reduce costs, it could be a materially bigger - and good quality - company in 5 years time. Definitely one to keep a close eye on for execution risk though.
Generally, it's an interesting field to watch over the next 5-10 years, to see how it develops. Also interesting are third party funders of litigation, such as Burford Capital (LON:BUR) which also has great potential if the quality management of the cases they take on continues to be good. I've kept waiting for Burford Capital (LON:BUR) to get cheaper since around 100p, and I'm still waiting.
Ta
Chris
Thanks for that Chris. Yes I agree it could be interesting over the next 5 years or so. I do hold Burford Capital (LON:BUR) also.
Thanks for your view Chris. I have bought into Fairpoint today and it was nice to be encouraged.
32red as a superstock, has the potential for much growth
Another surprise today was the SkyePharma (LON:SKP) merger with Vectura which probably has not gone down well. Would be interested in Paul and others views on this, I'm inclined to sell.
a merger was on the cards for SkyePharma, they been having good growth and a decent balance sheet. But I don't know enough to understand where the merger will take them. Im holding tight with them for time being.
I see, I think the merger is good news for Vectura shareholders but not sure for SkyePharma who have just announced a £30m profit today. A takeover would have been better.
Hi Paul
Welcome back Would be interested on your thoughts on Stadium who had results earlier this week Shares responded well
Best wishes
Strong set of interim results from Finsbury Food (LON:FIF) posted this morning.
http://www.investegate.co.uk/finsbury-food-group--fif-/rns/interim-results/201603160700082016S/
Seems to have addressed many of the concerns raised in Paul's January SCVR about lack of detail in the Interim guidance statement given the marked increase in profitability and margins. Market seems reasonably pleased with shares marked up 5% today.
Gus.
Good to see you back Paul. Will you be commenting on Paysafes report today?
Welcome back Paul - worried about your absence this week!
Andy
As I understand it the impairment reflects negativity/uncertainty about the volume/value of IVAs in future. Volume of new IVAs fell by 23% relative to 2014. And people entering IVAs are poorer than hitherto (and so less lucrative for Fairpoint). If bank rate rises this may cause financial distress to wealthier people with mortgages, which will be good for Fairpoint, but as Fairpoint (LON:FRP) says, "there is no consensus on when such increases may occur".
"As a result of this, we have reported a non cash impairment to goodwill in the IVA segment."
Paul,
I agree with your ACSO Superstock analysis and am a holder. Another example of a Superstock although with not such rapid growth and at half the PER is AB Dynamics. Fantastic return numbers, a clear vehicle testing niche and moat with all the major car manufactures as customers. Anyone else have any Superstock contenders?
I used to hold Ab Dynamics (LON:ABDP) until recently, not sure about it going forward and the forecasts are not so good, some director selling also. As for other superstocks, there is a high flyers screen on here somewhere which I think does pick quite a few such as Domino's Pizza (LON:DOM), Quartix Holdings (LON:QTX), JD Sports Fashion (LON:JD.) Crawshaw (LON:CRAW).
I would have added Ashtead (LON:AHT) and Next (LON:NXT) but both have fallen back recently. Maybe Fevertree Drinks (LON:FEVR) is one?
herbie47 - If we are talking about Ken Fisher's Super Stock formula, then his key criterion was a PSR (Prices to Sales Ratio) of < 0.75.
I may be wrong, but all the stocks you have listed including ACSO have a PSR way over 0.75, and in some cases touching 10.
I don't know anything about Ken Fisher formula so you have lost me there.
So Dart (LON:DTG), could be one?
Maybe someone should define a Superstock?
I hold ABD for just those reasons, the niche they are in is growing fast but not really big enough for a competitor to want to muscle in , unless they buy AB Dynamics to do so..
Paul the reason why Fairpoint (LON:FRP) is down is because of "Loss before tax of £5.65m"
Now this is due mainly to "impairment of goodwill of £9.01m" which I don't really understand, maybe you could shed some light on this?
I agree. My concern is also why just a write-off this year? Could it be repeated next year? Again, I don't fully understand.
Welcome back. Yes its busy day with results from Xaar (LON:XAR), Fairpoint (LON:FRP) and Finsbury Food (LON:FIF).
Xaar is quite interesting, results did not look too bad but share price was down 15% this morning but now only down 2%. FRP was a bit of a shock and was down 8% before recovering somewhat. Finsbury Food (LON:FIF) figures look very good to me, market a bit slow to react I think.
Paul good to see you back.
"I read a book about superstocks last year,...."
Sounds an interesting book. What was the title please Paul ?
I'd assume it's Super Stocks by Ken Fisher...
I could be wrong.
I believe it was 'Trade like a stock market wizard' by Mark Minervini as mentioned by Paul in the comments section of his SCVR of 4 Sep 2015.
I also have the book and found it heavy reading - it's one to concentrate on rather than dip in and out of.
I also have the book and couldn't put it down. The book is worth the price for the last two chapters alone, how to protect ones capital and when to sell etc.