Small Cap Value Report (17 Apr 2014) - BLUR, STT, SAL

Good morning!
Blur (LON:BLUR)
The market's doing a pretty good job of scrubbing off pockets of euphoria, and this morning it is deluded shareholders in Blur Group that have had a bucket of cold water thrown over them.
I've never really understood what this company does, nor how it comes anywhere near to justifying such a high market cap, given that it is loss-making. A trading update issued this morning has clearly put a foot wrong in some way, as the shares are down 30% to 307p. Although personally I've read the statement three times now, and don't recognise any of the figures in it. I cannot see turnover or profit mentioned at all!
The RNS says they are "reinventing commerce", which sounds very grand. It just all sounds like a fantasy world to me, which I am not visiting. In fact, I'm kicking myself for not being short of this particular share, as it was pretty obviously an over-hyped story stock with poor fundamentals, in my view.
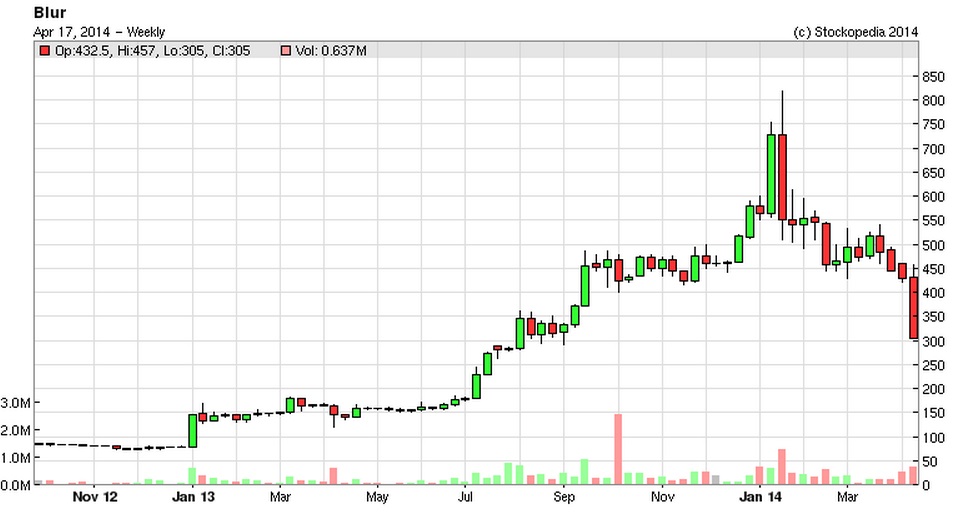
EDIT: A reader has kindly pointed out in the comments below that there are two announcements from Blur (LON:BLUR) today, one giving various business metrics (which is the one I reported on above), but also a trading update which for some reason slipped through my net.
The company seems to have changed its revenue recognition policy, with the result that some revenues have been deferred. The key section says;
As a result, recognised revenue will be lower than expected for the 2013 financial year but with a significant value of deferred revenues relating to these projects now expected to be recognised in 2014 and beyond. Recognised revenue is expected to be in the range of $5.3 million to $5.6 million for 2013 (2012: $2.8m) with total project bookings for the same period of $22.2 million (2012: $2.4m), an +825% increase year on year. Of the remaining project bookings that carry forward, we expect the majority to be recognised revenue in 2014. This is evidenced by the strong financial performance in Q1 2014.
I note that broker forecast for 2013 turnover is $9.9m, so reporting $5.6m is a good way below that, hence the sell-off in the shares today. Although the growth in deferred revenues is still pretty impressive. I've no idea how to value this share, but given that it's loss-making, the market cap of about £87m ay 290p looks rather rich still, despite being down 35% today.
Straight (LON:STT)
There's very little news today, as everyone is winding down for the Easter break I suppose. It can't come a moment too soon for me - this has been the busiest Spring I can remember for years, with a constant deluge of information piling up in my Inbox. Tonight I shall be going to see "Handbagged" at the theatre, a comedy with Mrs Thatcher and The Queen as the main characters. It's got great reviews, so that will be a real treat. Other than that I shall be going to a couple of BBQs and will no doubt find some time to catch up on researching individual companies. Although the market as a whole still looks expensive, there are still a few bargains out there, if you're prepared to dig through the data.
Turning to Straight plc, its results today seem reasonable in terms of profitability - it reports underlying profit of £0.8m. That sounds potentially interesting, given that the market cap is only £6.6m (at 56p per share). However, I have reviewed their calendar 2013 results, and it fails my Balance Sheet testing. There is net debt of £3.2m. Moreover, by the company's own admission, some creditors are stretched. Current assets are only 61% of current liabilities, which is a very weak position, that rules it out as an investment for me.
Note that the company is in talks with an Irish group over a possible bid. Also note that with a depreciation charge of £1.2m, this business has strong EBITDA. Although presumably all the machinery needed to make the kerbside plastic recycling boxes which it sells, are depreciated at the pace they wear at? That's the idea behind depreciation anyway, although I note from the cashflow statement that capex was only £308k in the year, barely a quarter of the depreciation charge, which benefits cashflow.
The outlook statement is just waffle really, but it sounds reasonably positive;
At the end of 2012 I said that the foundations of recovery had been laid. At the end of 2013 it was apparent that this statement has proved to correct as a significant improvement has been delivered. The considerable momentum created through two years of restructuring is carrying us forward with confidence.
It's not for me anyway, due to the weak Balance Sheet. Why take risk when you don't have to?
Spaceandpeople (LON:SAL)
The one stock I didn't expect to warn on profits, was this one. Results have been good for years, with rising EPS and dividends. I meet the Directors every six months, and they seemed really upbeat about the strong prospects for 2014 when I last saw them, only a few weeks ago, yet in the last few minutes they have issued a profit warning, the key part saying;
...pre-tax profits for the full year are now expected to be £1.4 million lower than previously forecast and will be £1.5 million after one off costs of £150k.
It's good that they have quantified the profit shortfall so precisely, but I am perplexed as to how profits can just suddenly halve, out of the blue, especially when the outlook was so positive only a few weeks ago.
Unusually, the company also forecasts profitability for 2015, saying;
The Board is confident that growth in revenue in the core business will resume towards the end of 2014 as new business wins gain traction and for 2015 we are forecasting modest revenue growth, along with the reorganisation and cost reduction plan that the Company has already implemented. This will deliver a forecast pre-tax profit for 2015 of £2.0 to £2.5 million.
I'll do some digging, but clearly this is a serious setback, and very disappointing indeed.
The following reasons are given for this unexpected plunge in profitability;
· UK promotions - sales traction in new venues being slower than anticipated;
· UK retail - increased restrictions on some retail categories available for us to sell;
· German promotions - delays in obtaining local authority permits to trade in new centres resulting in lost sales opportunities in this year; and
· German retail - delayed roll-out plan throughout the year and lower than expected occupancy in the first 6 months of the year.
One of the things I liked about this stock was that revenues and profitability seemed predictable, and mostly recurring in nature. Therefore it's utterly perplexing how the company can out of the blue announce a halving of profits. I shall investigate, and report back. My apologies for having got this one wrong.
The company's own broker, Cantors, has just revised its target price from 200p to 72p, and issued a Sell recommendation. Horses and stable doors spring to mind. Very unusual indeed for the house broker to put out a sell note though, so they are obviously unhappy with management here, as indeed am I. Looking back at the last trading statement, on 21 Mar 2014 (just 4 weeks ago) the company said;
The UK remains a competitive and fluid marketplace, but broadening the business through the acquisition of additional high footfall venues such as garden centres and railway stations is providing new revenue streams that offer promising prospects for the coming year. Together with the increasing contributions from the expanding overseas portfolio, they provide a platform for continued growth and we look forward to 2014 with confidence.
So how can things possibly have deteriorated in the last four weeks to such an extent that profits for this year are going to halve? It seems to me that we're possibly not being told the full picture here. Maybe a big client has been lost, or something like that? I am not a happy bunny. Not happy at all.
Well I'm sorry to break for the Easter holiday on such a negative note, and hope readers haven't been too badly burned on SAL. Just shows, we can research as much as we want, but the market can still throw totally unexpected bad news at us without warning. Such is life. Personally I shall be sitting tight on my SAL shares, as the price has now fallen to such an extent that there's really no point in selling now. It's still a profitable business, but seems to have hit a serious bump in the road. There are no issues surrounding solvency, as it has a sound Balance Sheet. Although I do feel that management will have to properly explain what has gone wrong, which today's statement fails to do, in my opinion.
Regards, Paul.
(of the companies mentioned today, Paul has a long position in SAL)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

51 comments
SAL's AGM
It appears that SAL is acting as a property manager and therefore conditions prior to letting, such as a grant of planning permission, are fundamental to forecasting future income. Current and potential income comes from let and lettable space. SAL might be unique but it is dependent on property owners and their agents for its supply of sites. If SAL can make a profit there is no reason why the original managing agents should not do it instead and some already do. Are there binding contracts securing sites for the future and if so the what is their average length? On what basis have the indicated future earnings been made? In so far as the reasons given for the PW are concerned, on further investigation, they might amount in total to gross mismanagement brought to light by the unhappy coincidence of a series of failures during Q1 of the current year. Putting the best interpretation on the situation, but never the less inexcusable, there appears to have been a lack of understanding by the management of the weaknesses in SAL's trading position leading to shareholders being misled by their failure to make a proper evaluation of the risks prior to issuing the PR on the 24th. March resulting in many shareholders losing a lot of money.
Have to agree with intuitive6191, the Spaceandpeople website is quite poor in both presentation and detail. And the headline under the name of the company is "The leading international destination media and retail solutions specialist" which to me is completely meaningless.
I've just looked at their website, and it looks fine to me.
The three large pictures with massive letters saying "Promotional Space", "Pop-Up Opportunities", and "Retail Solutions" give a blindingly obvious explanation of what the company does!!!!
Hi Paul
I will respond to your points in detail over the weekend and see what you think of my thoughts. I dont think SAL is a turkey but I cant see that it is special or unique or how it generates recurring income. I am however prepared to be convinced otherwise.
Hopefully investors check out company websites before they invest? To me this is important as the design and content of the website is quite relevant as to whether I commit. Meaningless verbage and poor presentation can reflect a company which is poorly managed.
I take the view that if the management are not managing their "shop window" then they are probably not managing other aspects of the business.
I attended the AGM yesterday. After being detained on a Victoria line tube train for 20 minutes, I missed the first 10 minutes of the meeting, and so was unable to vote for the CEO Mathew Bendings re-election. After the formal agenda there was a report on the reasons for the downturn from Bending with contributions from Gregor Dunlay the FD, interrupted and followed by a very extensive Q&A session.
Too much too report all here but some of the main points were as follows.
The Board claimed that although there had been a few 'amber' warnings before the 24th march report this was normal fluctuation in sales as divisional managers reported on their budgets and nothing to be too concerned about.. The full extent of under performance only became known after the end March figures were in. Hence the profit warning. Bending said that there had been downturns in each of their operational divisions before, but there had always been compensating good progress in other divisions to mask this. This time was exceptional as every division was hit for one reason or another.
UK Promotions.
Failure of new garden centre venues to produce revenues as forecast. Bending admitted that they had been over aggressive and optimistic on this one assuming that garden centres would develop like other retail outlets. He says this will happen but several quarters later than hoped for. This was a major shortfall.
IMO they should have done better due diligence and been more cautious in budgeting for this.
UK Retail
Problems here are to do with changing requirements of venue owners. Many different changes but e.g. gold buying & mobile phone kiosks are now seen as a bit naff, but these were very profitable in past.
IMO None of these changes should be surprising but part of the normal dynamic of a company with expertise in this sector.
German Promotion
This was a major negative as planning permission has not been given for a big roll out of juice and nail bars.
IMO They knew that this was an issue before the end of March. They were obviously gambling that planning consent would come sooner.
German Retail
Slower pace of roll outs delayed contracts, slower sales.
IMO Over agressive sales forcasts and optimism.
My overall impression is that there has been no skullduggery, but a Board that has enjoyed several years of success and has grown too complacent and carried away by their own hubris. Gregor reassured us on cash flow and estimated net cash of about £1m at 2014 year end.
IMO Still a viable business and they will now obviously trying to repair the damage. Will probably take a year or two to put things right. Mr. Bending bought 6700 shares this morning!
Many thanks for taking the trouble to report. My own thoughts were that this company had come very close to misleading the market and your report does nothing to change my view.
I thought of having a punt on SAL a while back but a few things put me off...
It seems that much of their business has very little competitive advantage. Many small marketing companies offer fairly much the same thing and I would guess that there is little scope to raise prices or grab market share.
I also had a look at their website and was quite surprised as it looked more like a local Government website - a bit drab and uninspiring with plenty of redundant words. Also the header tabs seem strangely out of sequence. If I was a client thinking of using them for presentation skills I would probably think twice after looking at the website.
This could well be a steady business in the future but it needs much better management IMO.
Hi intuitive6191,
With respect, I don't think you've fully understood the Spaceandpeople (LON:SAL) business model, if you think they have no competitive advantage. They are actually unique, there is no competitor doing what they are doing, embedded into many large UK & German shopping centres. They manage the kiosk space in those centres, and also broker one-off promotions into multiple sites. So the only real competition is the shopping centres taking this work in-house.
The risk is centres deciding not to do any of this type of work at all. That's why SAL have to get their act together in my view, but they are clearly the only significant player in this space, hence it's entirely down to how they execute. They've obviously made some big mistakes recently, but personally I think they will probably get it back on track in due course.
Regards, Paul.
Hi Ardipithecus , thanks for sharing your thoughts. It's pretty much what I was told over the phone by Matthew Bending.
It would appear that Giles Hargrave has started to reduce his position.....I thank he's sold around 200k so far. I'll be watching that space too.
I'll be sitting on this one for now - we'll see how it turns out in due course :]
Best,
Sully
Did anyone attend the Spaceandpeople (LON:SAL) AGM?
Any views or anything to report??
Best,
Sully.
Thank you Paul
Which is to say that the stocksheets (and therefore screens) can be quite out of date.
The Agriterra stocksheet took nearly three weeks to update recently. I also notice that the Quercus stocksheet seems permanently stuck in time since its profit warning in January.
Obviously if the stocksheets rely on broker upgrades - and these dont happen promptly (or at all) then relying purely on screens is very dangerous. I mention this as some posters seem to believe that the screens are the be all and end all of analysis.
Hopefully new investors will heed your good advice and make sure that they read all company announcements and manually adjust the figures on the stocksheets. I mention this as I am not sure that all investors on Stockopedia realised the time delay on stocksheets.
Quite incredibly Space and People is still listed in the Screen of Screens and both the Peter Lynch and Philip Fisher screens. After what has happened I doubt that either would have touched this company with a bargepole.
Perhaps Stockopedia need to revisit screen criteria to stop companies that have obviously stalled still being listed in growth screens.
I'm sure the screens don't update from trading statements, just from published accounts.
However, the forward PER should adjust when broker forecasts are processed, which can take Thomson Reuters a few days, especially for smaller caps. So the SAL forward estimates should adjust correctly in the next few days.
Screens are only a way of filtering for ideas, and then each idea has to be checked for the latest trading updates, etc.
P.
I was lucky to get out on 26th March. I sell when a forecast PEG is over 1. Some times this works others not. I did not like the director sell on the 24th but it was hardly a massive sale
I always thought this was a good company to invest in with good steady profits. Kept a close eye in it with a view to re-purchase if eps growth increased and in turn reduced the PEG.
How can things go so very wrong in less than 4 weeks.
Trying to see where the red flags have been on SAL. One flag may have been that the directors have been selling consistently over the last year, NEDs, COO and Chairman. We've not released our Insider analytics yet but SAL has been scoring worse than 93% of the market on this measure. I guess some of the management may have been worried about earnings sustainability. Sorry we couldn't have flagged this earlier.
I took e-mailed and have had a reply from the CEO - I'll update in due course.
Best,
Sully.
Yes, the CEO needs to explain how the fall in revenue has a direct impact on the EBIT for the same amount. No variable costs in this company??
They say emerging no/low margin activities (presumably because they are in build up phase) have helped replace (anticipated) revenue from the main profitable one, if you lose say 5m of (anticipated) revenue at 30% margin and gain 3.5m of revenue at 0% margin, you lose approx same in revenue and earnings. Looks odd but can be legit.
To me it looks like a teething issue. From their bios it seems the execs are adolescent entrepreneurs (in that it's their first real world venture, they worked in lala-land finance before) so it may simply be a case of hubris after a good start, probably squared when it started going wrong with thinking they could save the deals last minute (master of the universe syndrome) with then a cold shower when it downed on them (nomad ultimatum?) they couldn't keep waiting for miracles any longer. They'll eat some humble pie, which they can afford given they have a full fridge, probably learn from it and grow up good kids. (Just guessing here, I may be completely wrong.)
I decided to contact the company direct but not expecting a reply (I hold 2,980 shares) and have received an email from the CEO offering to call me on Tuesday or Wednesday. He has 2,092,000 (10%) so he has taken a big hit today. I will report back here what he has to say.
I personally am impressed that he has emailed back so quickly such a smaller shareholder.
Happy Easter.
Thank you to Purpleski for constructive action, rather than schimfing or flinging insults. I would be VERY GRATEFUL if you could share what the CEO has to say. Thanks again. (I hold 10k of these).
Hi P
Any contact made by the CEO? Anything you can share with us?
B
He did as promised but I was in a motorway service station an then he had the AGM and then he is traveling. He is calling next Monday. I will post back here next week.
By the way you may have noticed that Paul has taken the plunge (his words not mine) and bought some more at 70p and from what he says he has a chunky investment (15% of his portfolio?) in Spaceandpeople (LON:SAL). I have done that yet but will wait and see.
Thanks P. You are a gentleman. I must admit that I am quite impressed that he did come back to you. I would really appreciate your time (again)! when you get to talk to him again. I saw Paul's tweet, but had actually already decided to take on a few more and average down. Even with the reduced figures, the PER is about 9 and there is money in the bank and a decent profit margin.I have far too much in Spaceandpeople (LON:SAL) now, but will pare it down later (I hope!).Edisn's new note suggests the dividend will be maintained at the current level, giving a 5% yield.
On another note I see that Molins (LON:MLIN) has today announced a possible move to AIM. The reaction has not been good so far, and I can see further drops there because of that. Once it hits the 140s it will have a PER of 7, no real debt, and a pretty profitable niche business. The yield will be a nice 2.5% . Admittedly there is a massive pension defecit, but that seems to be in hand. One for the watch list? (I believe Paul took a few of these a little while back).
Thanks again
B
I was planning to attend the AGM to find out how SAL have been doing so well! Now it looks as though I will have to take a bag of rotten tomatoes with me.
Very disappointed with SAL, clearly a cock-up. The problems with the 2015 forecast are:
>> Without a credible explanation for the rapid deterioration it lacks credibility;
>> It's a hostage to fortune, what if they miss again?
>> I need to understand exactly what substantiates their confidence.
This is an 'acid test' moment for me. I like to see how a management team responds in a crisis if they handle it well from here on they they may redeem themselves.
Cheers Maddox
This has not been a good month for me Sweett (LON:CSG) and now Spaceandpeople (LON:SAL) but all part of the learning curve I suppose. I sat tight on Sweett (LON:CSG) because it did seem a bit of an over reaction and it has now recovered 38% of the fall. At some point I will have to decide whether to get out with a smaller loss.
Spaceandpeople (LON:SAL) is different. I suspect that the shares will bounce a bit but one has to question management ability when they can issue such a positive trading statement on 24th March and this one today. Something funny. I just dont understand the figures here.
Something I am learning is (as Warren Buffett always emphasise) that the management are so important regardless of the company etc.
I will try and get out when/if the stock rallies.
If SAL can't accurately predict profits from a month ago, it is pretty ludicrous for them to put out a forecast for 2015. Suggests they're making it up as they go along. The non-executive directors need to pull their trousers up and get the CEO to make a proper, detailed explanation of what has gone wrong, why, and what remedies are in place. If they're going to make 2015 forecasts, they need to put some detail around them.
Sadly can't sell Spaceandpeople (LON:SAL) at the moment. As soon as I can I will!!
SAL is a case of the 1st loss being the best loss. If you cannot trust the company management to correctly guide shareholders short term, then what hope is there in their longer term forecasts? Lost faith in this one I am afraid..Sold today at 84p
Ian
Interesting views on SAL. It is very easy to 'fall in love' with a holding. Well, maybe not love in this case but I'm surprised by the number of people still holding on after todays TS. The only question thats relevant here, in my opinion' is, if you didn't hold the shares already, would you buy them today?
The company reassured everything was going well just a few weeks ago, and now this today. Very poor indeed. From a valuation perspective they are maybe looking attractive after the big fall, but if you can't trust the management, which you clearly can't here, then for me its uninvestable.
Thankfully being an AIM stock SAL was one of my smaller investments. Things may well turn out to be reasonable a year or so down the line but the key issue for me is the credibility and potential of lack of information control and risk control exercised by top management.
In such circumstances I sell as rapidly and sensibly as I can; today I sold at 89.5p. For me it’s a question of trust in management; I am not thinking of dishonesty but more about having the “finger on the pulse”.
As Duncan would say “I am ooott”, not for me.
Forecast on top of this "unexpected" plunge is not credible.
If they cannot predict 4 weeks in the company's life then how on earth are they able to even consider a year?
Wasting time and money on travelling to an AGM seems a travesty, I would prefer a webinar event with some humility. A chance for aural questions from attendees a bonus.
I will continue to hold in the hope of a reduction in my paper loss
Edward,
Further to the Edison report, IMHO SAL management is either incompetent or untrustworthy. Whichever it is, SAL seems uninvestable to me.
All IMHO DYOR.
Edison put out a research note on SAL only 3 weeks ago "attractively valued"... http://www.stockopedia.com/research/brand-experience-82286/ Presumably the company paid for this research before they knew the quarter was looking poor, but still doesn't look good.
Quite! I will be asking (quite impolitely I might add) for the Spaceandpeople (LON:SAL) Directors to reimburse the company out of their own pockets for the cost of paying Edison to produce this research note - published just days before releasing a huge profit warning.
Anyone else who's intending to vote against resolutions 4 & 5 at the AGM, see you next Thursday.
Being devils advocate re SAL... ...would you lend a significant (or any) amount of money to somebody you viewed as completely untrustworthy? If no, which would almost certainly be the response of most people, then surely it is prudent for holders of SAL shares to exit their positions with all due haste?
SAL now at 89p. On the basis of the forecast of £2.0 to £2.5 mn pre-tax for 2015 (say £2.25 mn) that puts them on a pre-tax P/E of about 13 for 2015 by my calcs. Reading the statement does not fill me with confidence that SAL with recover, but the shares could be cheap if they can overcome their problems. Am not inclined to buy more until I know more.
Re: Spaceandpeople, I took the dive into these recently, albeit in only a small way to test the waters. Although normally a buy and hold person, I decided to sell as something feels wrong with a profit warning so soon after a trading statement. Will watch from the sidelines.
Re Blur Group you might have been looking at the Metrics Update rather than the Trading Update (they were separate announcements). In any event the Trading Update refers to recognised revenue for 2013 of a whopping $5.3 - 5.6m .... even post the share price fall today the market cap is still c.£87m
Hi Heisenberg,
Many thanks for pointing out the two separate announcements from Blur (LON:BLUR). My system only picked up one of them, so I shall now update the article accordingly.
Thanks again, Paul.
Having topped up with a few more SAL this morning at 130.90p, I'm seriously unimpressed that a Trading Statement like this is put out mid morning.
What possible reason can there be for not issuing it at 7am?
Garbetklb
I agree. It's very poor show to issue a trading statement during the day. That makes it a total lottery in terms of whoever can sell fastest gets out at a favourable price. Much fairer to issue all trading statements at 7:00 so everyone has time to digest the news, and have a level playing field.
Regards, Paul.
The AGM for Spaceandpeople (LON:SAL) is at 10am next Thursday (24th April) at the Bloomsbury Hotel in London. If anyone wants to join me to express disappointment at the management, please come along!
Deluded shareholders of SAL you mean!
Hi fek47,
Thanks for that. Unfortunately I am not able to attend the AGM next week, as I will be away visiting family. However, I think it essential that as many shareholders as possible do attend, and try to get to the bottom of what's gone wrong.
Regards, Paul.
Hi Fek47
Living in the Highlands, it's v unlikely I'll be at the AGM, much as I'd like to be. Regardless of the message, I'm v unimpressed by such a significant Trading Update to be issued mid morning - especially as I'd topped up at 130.90p!
I'd be very grateful if you could ask why it wasn't issued out of trading hours to enable all investors to digest.
Thanks
Garbetklb
It seems to me none of the reasons offered here can really cover the fall in profits at Spaceandpeople (LON:SAL). The restrictions on selling e-fags, and a slower roll out in Germany are unlikely to have such a massive impact. Something else must be going on here. I have a small holding and am very disappointed. This is another one for the bottom draw! (As Paul has now said, there seems little point in selling, as we still have a solvent and profitable business. The predicted figures are actually similar to those returned by the company a couple of years back, when the shareprice was around 75p. A couple of motns ago it changed hands at double that. All in all I will hang on,and provided there is no further bad news I will top up again if it hits 75).
Hi Paul
Further to my previous message, I have no found the reason for the Space & People price fall - that is, Space & People have issued a disappointing trading statement today. Any comments you have on this trading statement would be appreciated.
Many Thanks
Hi Paul
Do you have up to date information on one of your favourites, Space & People? The price is falling like a stone today (down over 30% as I write) but for no obvious reason I can find!
Many thanks
davidtalbo, kevanp,
They threw a quick one: http://www.investegate.co.uk/spaceandpeople-plc--sal-/rns/trading-statement/201404171200020922F/
Good grief! Can't sell Spaceandpeople (LON:SAL) — the price is dropping quicker than I can reset my limit price. I'd love to know your take on the fall Paul.
Best, Kevan
Surprise profit warning from SpaceandPeople. Would be interested in your comments!