Small Cap Value Report (17 Aug) - IDOX, MCON, ALM

Good morning!
Edit: This report is now covering Idox (LON:IDOX), Mincon (LON:MCON) and Allied Minds (LON:ALM).
Best regards,
Graham
Idox (LON:IDOX)
- Share price: 62.375p
- No. of shares: 405.2 million
- Market cap: £253 million
IDOX provides software & related services, mostly to the public sector. I covered it last in December (link).
There hasn't been any share price progress so far this year, and the dividend yield is slim, but it has been a successful holding for long-term investors.
It's attempting to grow organically and via acquisitions. The last IDOX acquisition I covered seemed to be at an aggressive valuation (EV/EBITDA 35x), which brings us to today's.
It's a £5 million deal for "a supplier of electoral back office software and services to UK local authorities".
IDOX already has an elections business unit, so this sounds like a good fit.
The valuation is also far more modest than last time: 4.5x EBITDA on a debt-free and cash-free basis, with senior management staying on for at least two years.
My opinion
I'm getting more comfortable with IDOX as a potential investment.
Public sector clients can be sticky with their software systems - there is a lot of hassle, risk and uncertainty to change, so they can stick around for many more years than might otherwise have been expected.
There does seem to be a good rationale for putting all these public sector services in the same group. At a group level, IDOX should have a very strong understanding of its clients and of each particular service type (e.g. electoral services).
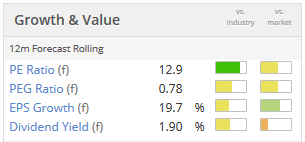
All the metrics are fairly average at the moment but let's keep it on the watchlist:
Mincon (LON:MCON)
- Share price: 98p (+9%)
- No. of shares: 210.5 million
- Market cap: £206 million (€226 million)
I commended this producer of hard rock drilling tools for playing down its success in Q1.
But now the half-year report is out, and the success has continued:
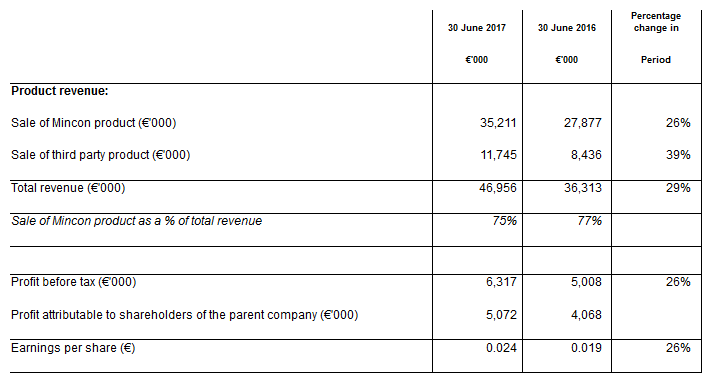
It's an Irish company, hence the €uro reporting style.
Even better, the above performance was achieved with a currency headwind (i.e. it was artificially depressed):
The underlying momentum is greater than this, since we had to absorb an FX charge of €0.5 million as the rand and dollar weakened. We will continue to seek longer term solutions that mitigate these movements.
Mincon also reminds us that its growth is "very substantially" organic.
It's refreshing to see growth that isn't manufactured by large acquisitions, and to see results which aren't complicated by reams of adjusted items.
Prospects for the next phase appear strong:
We have three very substantial projects moving into their sales and marketing phases, with the extended range of large hammers and bits, the new hammer range, and the rapid build-up of our Mincon Nordic subsidiary.
We have driven good growth in our current product ranges, and we have the new products, the new factories and the investment of the last couple of years to come on stream. We have a very strong balance sheet, adequate cash resources and an ambitious, experienced team in a sector that continues to improve.
Industries served by Mincon include many different types of drilling: foundations, exploration, mining, quarrying, etc.
The company has net cash of €32 million and no balance sheet concerns, and talks about the need to drive improvements in its return on capital employed. Stockopedia stats suggest that it has only been earning around 9% ROC.
The outlook statement is again calming:
We had sales of c. €40 million in H2 last year, and while the growth in this reported half year has been strong, we will need to keep growing to add significantly to that run rate. Having said that we have three good investment projects coming to fruition in the remainder of 2017 and 2018 and believe a reasonable strike rate will deliver meaningful growth and profitability from these for the Group.
My opinion
The only detractor for me is the weak return on capital/ return on equity rates.
I'm not sure what can be done about that though, besides perhaps stretching its balance sheet a bit via special dividends and/or borrowings.
The organic growth is excellent, however, as is the clean reporting style.
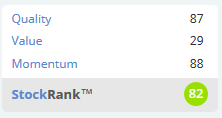
So I'm glad to see it has a strong StockRank too:
Allied Minds (LON:ALM)
- Share price: 160.9p (unch.)
- No. of shares: 237.5 million
- Market cap: £382 million ($492 million)
I've been bearish on this Boston-headquartered venture capital outfit since before it fell within our remit at the SCVR. The share price has been as high as 700p (£1.5 billion market cap!)
Its subsidiaries are very much in the early-stage category, typically developing intellectual property at spin-offs from American universities.
It has never made any money. The premise has been that the profits would eventually flow, as successful subsidiaries progressed toward commercialisation.
The rate of cash burn and losses has always looked unsustainable to me, and cannot continue for all that much longer without fresh financing:
- Net cash and investments* at 30 June 2017: $177.0 million (FY16: $226.1m), of which $113.3 million held at parent level (FY16: $136.7m)
- Revenue: $2.0 million (HY16: $1.3m)
- Loss for the period: $58.2 million (HY16: $52.2m), of which $44.6 million attributable to Allied Minds (HY16: $41.2m)
Seven subsidiaries were closed during the period.
ALM produces for investors a number which is its own best estimate of the value of its stakes in the companies it has invested in. They call this the Group Subsidiary Ownership Adjusted Value (GSOAV).
GSOAV was previously at $536 million. It was easy to call it as a short when the company's own subjective estimates of what its investments were worth, plus its cash pile, added up to something much less than the market cap.
With those seven subsidiaries having been written down to zero, the GSOAV is now $416 million.
We can then add on the $113 million in parent-level cash to get an estimate of group value: $526 million.
The actual market cap is about $490 million. It's reassuring that investors are no longer applying a premium to the company's own estimate of what it's worth!
Meanwhile, annualised losses in the region of $80 - $100 million continue to pile up. Accumulated losses are now $330 million.
One or two of the subsidiaries sound promising and its deep-pocketed investors are likely to continue funding it, but it's still extraordinarily speculative. One to avoid, in my view.
That's all for today. Let's hope Paul sends us a postcard.
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

23 comments
And I'm agonizing over whether to sell some of my position and if so how much. It comes down to a question of how likely the bid/bids is not to proceed and what would the price be then.I'm guessing 10% and 165p.
Re Fwyburd. I too have been building a health position in IQE but got very nervous and sold the lot on Monday 14th. I agree it was just getting way overvalued. Have we done the right thing? Who knows but I had a horrible feeling we could have lost a great deal if the consensus changed. hey, a profit is a profit.. I think it was thanks to Paul or Graham that I bought in the first place, so thanks guys and keep up the great work, you are both much appreciated. Charles
Problem with wide spreads is not so much buying but if everyone is selling spread will be even wider and wide spread shares tend to illiquid, I had a job to get out of some. Now I avoid them apart from Bioventix (LON:BVXP), that spread varies from about 1%-10%.
Further to last post, I mean that even since the possible offers emerged recently the order book didn't look anything like this and this suggests something new eg someone has new information.
Thanks for covering Mincon (LON:MCON) Graham and for spotting it in the first place. It's a small part of my portfolio after I did some further research and adds some resources to the mix. The SP perhaps reflects the current growth trajectory but I do like the balance sheet and its niche.
paraic84 - Out of interest how to you manage with a 10% spread - Doesn't it concern you need a 10% rise to break-even? It does me and hence I usually avoid 5%+
I have a pretty small holding (£1.25k) and managed to buy with a much narrower spread at the time. I'm not as rich as some people on here! I find with small holdings you generally don't have the same level of spread on such small caps and you can often sell quickly on profit warnings etc before others are able to.
When I first bought Creightons (LON:CRL), the published spread was 7.5p - 9p, that's 18% based on the mid-price. Actual buy price was 8.75p, so probably still greater than 10% real spread.
I sold some recently at 38.9p. That makes the spread fairly irrelevant. I'm not saying I like spread, and I'm not saying it's totally irrelevant, and I don't have an opinion on Mincon (LON:MCON) (yet), but the point I'm trying to make is that unilaterally writing off choices due to the spread seems overly restrictive to me. If I thought Mincon (LON:MCON) was likely to grow earnings 15-20% a year for a few years then I certainly wouldn't let the spread put me off.
I never put a spread constraint in any screen that I run.
Appreciate that feedback - Thoughtful - Quite fancying Severfield around these levels - Ticks a lot of my boxes except the 5% spread - Anyway feedback on spreads much appreciated and agree with much of the comment from previous experience - Cheers!
Has anyone noticed the very interesting share price movement in Revolution Bars (LON:RBG) ? In particular anyone who has access to the Level 2 order book of the LSE will see there are as I write orders to buy about 300,000 shares at within 2p of the bid price. This is EXTREMELY atypical for this share and to me strongly suggests that someone is either knowledgeable that a bid is about to be launched OR is himself a potential bidder. What do people think?
Imho the fact that someone is looking to buy an unusually large volume at 2p below the current price might be interesting, but I think that the offered conclusions are just plain wrong.
It would seem to me that it's much more likely to be one or more players trying to take advantage of any dips - it seems very unlikely to me to be any kind of signal that could be traded.
Just from a personal perspective it also seems a little odd even for a "trader" to be trying to scalp that 2p given that in the event of the existing bid coming to fruition the upside is 10p and in the event of a competitive bid then more than that. Whereas in the event of the bid failing there is a probable short term downside of at least 20p (probably more) and the likelihood that those offers would get filled (at presumably c. 188p) in the event of a no bid being announced.
It is though I think an interesting position for slightly different reasons :
For now I'm still holding onto my smallish position (on which I'm slightly ahead atm), but the predominant reason for this is the belief that with competent central management (which hopefully is forced by the interim CFO) the groups should be worth more than it is currently. I can't really work out whether the dynamics of the potential bid / counter bid / walk away provides near term value above the current price or not - but hopefully at the very least there is something to learn from this.
Thank you for your interesting comments.
I would highlight that as you yourself observe, it is odd for someone to try to buy a large amount, when the downside is potentially large and the upside small. This is itself an argument that whoever wants to buy has inside knowledge, i.e. they know there is no downside risk. On your question of why they would try to scalp a few pence as opposed to just buying, my answer is that there is not that much stock available for sale on the other side of the order book. If they were to start buying what is available it would also push up the price very fast. So they are hoping to just catch any sales from people who want to get out. Although I accept they could buy some stock from the RSPs at around the offer price, they have their sights on larger quantities.
They may also judge that even with inside knowledge that the offer will proceed, assuming the offer will be at 200p it's not worth it for them buy above the price they are offering i.e about 188p (due to delays in completion/risk of failure).
On your point of 300k being a relatively small percentage of the whole company, it still makes sense to save as much as you can. Also, it doesn't mean they are only trying to buy 300k. Maybe if those orders would be filled they would then place more orders either manually or automatically. Actually I think whoever is trying to buy and for whatever reason is being very clumsy and indiscrete by not submitting the orders as iceberg or hidden orders, or via an automatic trading program, which doesn't show the whole quantity intended to be bought.
Interesting situation, let's see how it plays out.
Actually I've found it useful to verbalise my thoughts on the current status of Revolution Bars (LON:RBG).
On reflection I've decided that the c. 5% premium to the known possible bid just isn't enough for me in this market (where I think big and better opportunities may be 'just around the corner'); so I've sold the lot of my small position this morning for a modest gain.
So one can no doubt expect the counter bid to come in early next week!
I've made up my mind. I'm not selling any. The reason is I have just spotted more interesting behaviour on the level 2 screen. Two bids went through at 190p at 11.15GMT, one for 14500 shares and one for 1225 shares.Then 25 minutes later two more bids appeared at 190p, one for 14500 shares and one for 1215 shares. So clear someone is trying to buy shares in a slightly less open way than yesterday but still noticeable! I can't believe anyone would go to such lengths to buy such a large amount at 190p without inside knowledge of a definite bid of at least 200p. It's just too suspicious. Time will tell.
I hope that works for you dgold.
I'm not a student of order book or tradewatching, but to me it feels like you are making a pretty big intuitive leap from order book and trade data to the motives, knowledge and even competence of one or more unknown market participants.
Graham, I am looking forward to your thoughts on Marshalls, personally I like it when you guys occasionally comment on bigger caps as I have often thought your small cap comment style would be useful with mid / big caps which often seem to get bland analysis in the mainstream.
(FWIW) I do not own any shares in Idox, but probably should have, because for the last 4 years I must have spent 2 hours a day on their software running our database and liked it from day one and have never had any trouble with it, but somehow managed to ignore what was right in front of me.
Hi Collector, cheers for that.
Honestly, I didn't realise the Marshalls mkt cap was quite so big, when I first thought to cover it. So I went for ALM instead.
But yes, I'm interested in some big-caps and I do study them, so I might explore some ways I can cover them too.
Interesting that you like your IDOX software too, every little bit of anecdotal evidence is good to hear!
Thanks very much,
Graham
I had a quick look at Mincon (LON:MCON) but the wide spread put me off, 10% is far too much.
Hi Graham,
I'd value your opinion about how to value IQE (LON:IQE). As I understand it, they had £133m turnover in 2016 and made £20m pretax so £16m post tax. This is a net margin of 12% of turnover.
When ARM was acquired they got 24.4 times revenue/56.8 times post tax profits but enjoyed a much healthier net margin of 44% of turnover.
If one applied these same multiples to IQE for the fun of it one would get a valuation of between £908m to £3.2bn on 2016 numbers. Now clearly this is a growth stock which means it is harder to value based on historic numbers but what multiples would you apply to reflect their much lower margins than ARM?
(I was long IQE but sold recently, concerned about the sky high SP, the volume of speculative buying and the increase in short positions).
Hey fwyburd, I appreciate the suggestion but don't feel like I have any particular insight into IQE at the moment, sorry! I'm sure one of us will cover it on results day though.
Graham
Good morning, Graham, (and Paul, if you're listening),
I have returned from holiday to read the column and find that the format has been under discussion.
My take on the blog is that it fills an essential role in my research of the smaller co's on AIM. I would far rather the opinions expressed are arrived at after due thought and consideration. I don't think the blog is of much use to anybody if the content is rushed, not that the opinions might be wrong, but the nuances may be lost, as might the benefit of the readers opinions in the feedback. Your opinions are written with longer term share-holders in mind, so the analysis needs to stay the way it is, with this firmly in mind. Your warnings when disaster or dodgy dealings appear are timely and can be acted on, or not, as the investor feels necessary. Day-traders are not your target market, they have to live on their wits and this often has little to do with considered opinion, more with gut feeling and speed of reaction.
I have much to thank you both for, please keep the quality, never mind the speed...
J.
J, thanks very much for that comment.
And I'm sure Paul is listening, wherever he is!
Cheers
Graham
I hope Paul's not dead! That comment made it sound as if he is beyond the grave - a spector, forever watching over us