Small Cap Value Report (17 Dec 2015) - ZYT, CHA, BOOM

Good morning!
I'm interviewing the CEO of Zytronic (LON:ZYT) this afternoon, am looking forward to that. I've only had one reader question submitted so far, so could do with a couple more. Therefore if you wish me to ask the CEO of Zytronic anything specific, please submit your question using this simple form, and if it comes in before 2:30pm today, I should be able to ask it (the interview starts at 3pm)
Concha (LON:CHA)
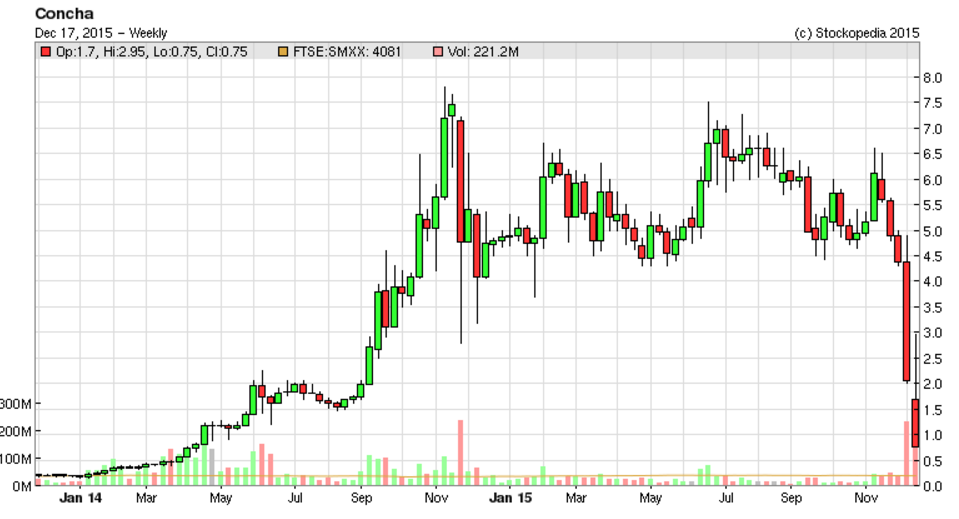
Share price: 0.75p (down 71% today)
No. shares: 1,552.7m
Market cap: £11.6m
Termination of investment discussions - let me translate this as: the big ramp finally unravels. Concha is just a cash shell, which only had £5.7m in it when I last looked at it here on 31 Mar 2015. I warned readers that the £92.5m market cap (once options were included, or £78.8m without, at 5.33p per share) was completely ludicrous. When I find over-priced junk, I don't hold back, because people need to be warned, and my concluding comments on 31 Mar 2015 were:
"It will be fascinating to see how this pans out. Anyone buying the shares is crazy, as it's nothing more than a wild & grotesquely over-priced speculation at the moment. Let's see if anything of substance does appear, to justify this absurd valuation. It's going on my bargepole list for now though. - See more at: http://www.stockopedia.com/content/small-cap-value..."
The company had said it had found an exciting but unspecified investment opportunity, but that has now fizzled out. So the valuation now resets back to what it should be for a cash shell, which is at par with cash. So the shares really need to fall further, to about half the current price to get there.
It was blindingly obvious that this share would collapse sooner or later - you can't defy gravity forever, by valuing a cash shell at £70-85m more than its cash pile, justified simply by vague assurances that an exciting investment is going to be made with the £5.7m cash.
It's just a pity that I wasn't able to get a short on, but never mind. Frankly, it's just embarrassing that silly ramps of this nature keep happening on AIM. Part of the problem in my view, is that AIM has no minimum free float. Therefore it is very easy for unscrupulous groups of people to operate a "corner", then manipulate the share price up to anything they want. Squeezing out shorts can further exaggerate upwards movements, hence why it's so dangerous to short illiquid AIM stocks.
My opinion - elaborate ramps like this share always end in tears. It's only a matter of time, as they can continue for quite some time, and you often see the same names behind this type of ramped up cash shell. Early birds can get lucky, and catch a worm, but generally by the time you see a bandwagon, it's already too late, and your buying will just be lining the pockets of the stock promoters, and giving them a profitable exit, whilst you end up with a 90%+ loss, once reality pulls the price back down to earth.
Anyway, readers here were warned in no uncertain terms that this was a blatant ramp, and it's another win notched up for my Bargepole List - which incidentally is only scratching the surface of all the rubbish companies on AIM, there are many more that I haven't ever got round to putting on the list, but which should be.
It just requires common sense more than anything, to see that a cash shell with £5.7m in it cannot possibly be worth £75-95m. It clearly doesn't make sense. If it looks too good to be true, that's because it isn't true!
In the end, this type of thing always collapses back down to where it started, timing is the only question:
Audioboom (LON:BOOM)
Share price: 3.6p (up 9.2% today)
No. shares: 535.6m
Market cap: £19.3m
Clarification of CEO comments - let me translate again: the CEO has had his legs slapped, for being naughty, ramping the share price in a promotional video interview.
The RNS today says;
In a recent interview, which has since been broadcast as a podcast, Audioboom's Chief Executive Officer, Rob Proctor, made reference to a new content deal and adviser related matters which would be announced next Monday.
No further details about the deal or content partner were disclosed. Although the Board would not expect any such announcement to be of itself price-sensitive, the Company wishes to update the market that the comment was made.
I'm confused here. The CEO pre-announced something in an interview, in order presumably to excite investor interest and push up the share price (why else mention it?). Yet the company says the announcement won't actually be price-sensitive anyway!
I think the reality is that the company is nearly out of cash, and so they want the share price up ahead of the next discounted Placing. A recent announcement indicated that the cash pile was down to £3.1m by 30 Nov 2015, and this is a heavily cash-burning company, with to date negligible revenues.
The company had £6.2m in cash at 31 May 2015, so in just 6 months it has burned through half that cash pile. Therefore, even if some revenues are generated in H2 (H1 saw revenues of only £46k - no you read that right, £46k), then the company looks set to run out of cash in perhaps Jun 2016?
So I imagine a Placing is already being worked on, hence why private investors are being warmed up for exciting things ahead, to induce us to act as cannon fodder to get the share price up, before a discounted Placing is done with larger investors.
If they can get the share price up to say 6p, then a Placing at 4p would be do-able. Placees will then flip the stock, and the share price will come back down to 4p, then probably below. It's the same old cycle that you see happening over & over again with blue sky AIM stocks. Indeed, it's exactly what happened when BOOM raised £8m in Oct 2014 - a big push was made to get the shares up, then the Placing happened at a discount of about 10-20% from memory, although the share price was very volatile at the time.
My opinion - bottom line is this. BOOM has failed so far to demonstrate that it has a viable business model. It's created a super App, and offers a very nice service, of spoken word audio clips. However without revenues, that's not a business, it's a public service.
I think investors are beginning to realise that Apps are a money pit. The odd one might make a fortune, but most seem to be a dead loss commercially.
I would look again at BOOM if & when it gets close to breakeven, but it's nowhere near that point yet, so is reliant on another funding round to keep the lights on throughout 2016.
The story a couple of years ago was that you could value sites like AudioBoom based on a multiple of their users. So £x in value per user. I (briefly) was seduced by that logic, until I had lunch with a bear on the stock, Was Shakoor (@Wshak1 on Twitter) who has a great nose for BS, and he persuaded me to ditch my shares for a profit, when the price was in the teens. Thank goodness!
I wish the company well, as it's developed a good & useful product, but it really does need to demonstrate commercial viability before I would look again at the shares. Hope, and hype are not enough any more.
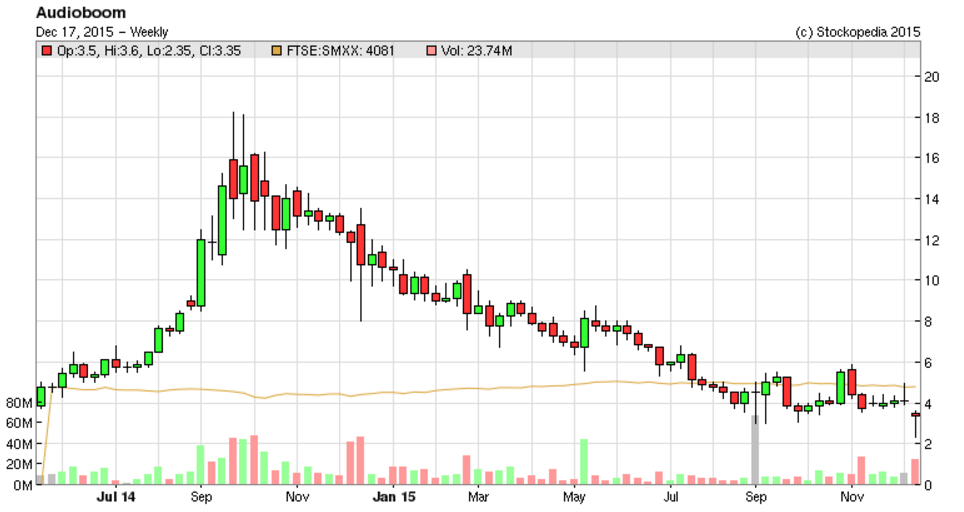
Note how a huge rise in share price, in a speculative stock, is so often followed by a long drift back down again to where it started. There's a lesson in that.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

16 comments
Thescoop, once youve been burnt once or twice by companies and directors telling outright mistruths, concealing, twisting and obsfucating, you learn not to ever base an investment decision on what they say.
Ignore what audioboom ceo says. Entirely. Look at the numbers and make your own mind up, not swayed by ceo or anyone else.
98% certainty Audioboom will be ramped, and it will do a placing.
Hi Scoop,
Well I wouldn't say that - I get plenty of things wrong, as everyone does. But generally I get more right than wrong, which is all that's needed.
It's just that in specific cases, the downside risks are very clear - only having 6 months' cash left in the kitty, for a heavily loss-making business, is one of the highest risk situations you could possibly entertain. It might be fine, you never know - they might be able to convince existing & new investors that it's worth chucking in another £5-10m, but there's a chance that investors may be reluctant to do so, in which case they can just name their price, and existing shareholders are potentially diluted to oblivion. I cannot understand why anyone would cheerfully accept such a gigantic risk?
Regards, Paul.
It's never a good idea to bet against the views of Paul Scott, but in this case I think I'll keep holding for a while longer at least. Thanks for your feedback Paul, iIl shall definitely keep it in mind.
Hi Scoop,
Audioboom (LON:BOOM) might well still have potential, but I don't buy shares just on hope value any more - as it's a fairly sure fire way to lose money.
Even if turnover does rise from £50k to £500k each 6 months, that's still nowhere near enough - its costs are running at about £3m per half year. So you need turnover to rise not by 10 fold, but by 60 fold, just to get to breakeven!
More pressing is the cash burn. As I mentioned in the article, there's only enough cash to last until mid-2016, so another Placing is a certainty. As we've seen with numerous cash-burning micro caps, these are usually done as discounted Placings, with no Open Offer. The latest recent examples being Snoozebox Holdings (LON:ZZZ) (done at a 25% discount), and last night, Rightster (LON:RSTR), done at a discount of about 47%.
So why on earth would you want to buy in the open market, when you can be virtually certain that a discounted Placing is imminent? I think you would have to be a reckless optimist for that.
People are probably already shorting this share, knowing that a Placing is coming, and they can close their shorts at a profit using new shares procured in the Placing at a discount. It's free money basically for the shorters, paid for by people who buy the shares in the open market now. Shorting ahead of a Placing is not actually illegal, providing you haven't been told there is a Placing, but have instead just deduced that there is likely to be a Placing coming.
I would look again at BOOM once it has proven that it has a viable business model, but so far that is completely lacking. It's all just jam tomorrow at the moment. It's a nice App, but like many Apps, it's not a viable business yet.
Good luck with it - you'll need it!
Regards, Paul.
My inability to write coherent sentences shines through once again! Sorry folks, but I hope at least my criticism over Paul's comments shines through. This stock IMO has legs and is well worth keeping an eye on, starting with clicking on the links I've provided above. I look forward to reading feedback.
Paul et al.,
Rob Procter was hesitant in mentioning the change of broker and the announcement due to take place this Monday, in an interview hosted on Audioboom (not the TipsTV interview given a day later, and not for any paid-for interview). I don't believe it was a blatant ramp at all, but I'll let you decide for yourself (listen from 4mins in): https://audioboom.com/boos/3959309-369-audioboom-ceo-rob-proctor-and-ex-market-maker-wayne-grossman
The reason for the rise over the latter part of this week was due in part to clarification made in the interview when Rob explained that this year's expected revenues of £500k (five hundred - substantially more than the £50k you have referred to) would not be met, and that although revenues were below market expectations as noted in Monday's RNS:
http://uk.advfn.com/stock-market/london/audioboom-BOOM/share-news/Audioboom-Group-PLC-Year-end-trading-update/69683579
This, apparently, was due in large part to an accountancy technicality where although BOOM had received payment for a service/es because BOOM had not had time to provide the advertisement services paid for before their end-of-year, and so some revenues had to be deferred to Q1 2016. I defer of course to you, Paul, in explaining the technicalities of accountancy rules.
I agree with you that BOOM is likely to go for a placing, but I suspect it will be at little or no discount to today's price, and shall be for growth and not to to replace batteries in any floundering life-support machine.
It appears from the interview that there will be good news flow through to the end of February, with Audioboom's app to be built as a 'native' app in an as yet undisclosed mobile OS; BOOM are also probably going to get some other big content providers in places such as India (think audio casting cricket matches) etc.
You used to love this company, Paul, because it had potential. IMO it still does.
Best wishes and Merry Christmas to you and all your readers.
Hi Paul - think you are wrong about the way placings in things like BOOM work. It is actually even worse. The company pays for some PR. This is often in the form of dodgy video interviews, proactive investor, tips TV etc. etc. This is all paid for by the company. It also sometimes hires well known stock tipsters to make positive comments. This inevitably pulls in the punters and as they see the shares rise they get more and more excited.
At some point and crucially before the placing those in the know start to get short the stock selling into the strength generated by the PR.
The company now turns to its brokers to do a placing and the first people who are willing to take part are those short who happily cover their shorts lower in the placing. Everyone's happy! Except of course the mugs that believed the daft PR.
Nothing illegal about any of this because the shorts are not inside on the placing when the stock gets ramped. The company knows it can't raise money without the help of the larger short investors because it's not practical to deal with hundreds or even thousands or retail investors and offer them rights issues etc. with a retail compliant prospectus.
It is important to realise though that this is the mechanism these types of companies use. It is fairly easy to spot just look at the cash burn and when they are starting to run out watch out for the CEO doing the usual junkets on the promo outlets.
Log
A great service to all use small invester
Paul, thanks for the opportunity to ask questions to ZYT.
I have a slightly off-kilter question. The new 12 sided £1 coin will be introduced from 2017, and all vending and gaming machines will need to be changed. Is this an opportunity for ZYT to get operators to upgrade/improve at the same time as making the necessary modifications to the coin chambers?
Also, we're moving inexorably, if slowly, towards being a cash-free society. How much of ZYT's revenue is ATM-related?, Or do ZYT see usage of ATM machines in other ways once a cashless society comes about?
Re. Audioboom (LON:BOOM) It is quite amusing now to think back and remember the ways internet companies were valued during the dotcom bubble years. Revenues per eyeball, webpage click, webpage impression, web traffic, to name the few I can remember. All marketing and development costs were immediately capitalised and accepted without batting an eyelid.
Off-set by things such as self service tills (think M&S, Tesco and WH Smith), all have touch sensitive screens.
Paul, Can you explain to me why a cash shell should be valued at the cash on its books. This implies that the cash may someday be paid out to investors or used for an investment that will pay out at least that in the end. Since many cash shells seem to exist for the purpose of paying the directors fat salaries until the money is gone, I value them at ...zero!
Paul: Is this your first SCVR with a title that sounds like the start of a Drum & Bass song?
Haha, love it!! ZYT-CHA-BOOM certainly does have a ring to it LOL!!
He also said in the same podcast that they would be announcing the change of broker on the same day... Placing ahoy?
Thank you Paul for providing us with so many valuable lessons.