Small Cap Value Report (17 Jul) - QPP, NRR, CLL, HSM, KBC, UBI

Good morning. There's a trading statement from Quindell Portfolio (LON:QPP) which, as usual, sounds highly positive. They report 1.1p adjusted EPS in H1 (the six months ending 30 Jun 2013), which if you believe the numbers means annualised EPS of 2.2p, so at 11.25p the shares appear to be very cheap, on a PER of 5.1.
Clearly at that price, a lot of the market does not believe the numbers, and nor do I. The history of this sector (insurance outsourcing) is of companies reporting rapid growth, fabulous profitability, and a debtor book getting bigger & bigger, and eventually large chunks of it being written off an uncollectable. So the profits were a mirage. Some people believe Quindell is different. It might well be, who knows? But there are enough similarities there to make me treat it with a bargepole.
I note that of the remarkable £43.5m profit before tax they report for H1, only £2.3m has carried across to operating cashflow! The bulls will say this is because they are growing so fast. Bears will say it's the same old story - big profits, but no cashflow. The bulk of their revenues come from very low margin credit car hire, and the profit is supposed to come from IT contracts.
The vital number that is missing from this morning's statement is what the debtors figure is. Why haven't they reported on that? What are debtor days? Are they static, or have they grown again? I would put money on debtors having grown a lot, hence why they haven't reported the figure.

I will only believe the bull story here & admit I'm wrong if & when debtors stabilise & the cash comes rolling in. That is not happening yet. They have exited their ill-conceived "Equity Swap" which was presented as if it were a Placing in Dec 2012, when it wasn't. They have repeated that it's not material, but that's not the point - the issue is that they misled the market as to the true nature of the fund-raising. To my mind that's the biggest red flag of them all.
It sounds like the shares have been given to vendors for deferred consideration, which avoids having to sell them in the open market. The trouble is, there is a wall of sellers here because of the many lock-ins for acquisitions, which expire in various tranches. So the share price will be up against a big headwind for a long time yet.
Good luck to holders, but it's not for me. I've never had either a long or a short position in this one.
Regulars will know that Newriver Retail (LON:NRR) is one of my favourite shares - it's a UK property REIT, which has been buying up secondary shopping centres, and then applying a range of actions to drive up asset value proactively. The management are highly impressive, and very experienced in this space. As a former retailing finance man, I know this sector pretty well, and can unreservedly tell you that these guys really know what they're doing. They focus on value-orientated tenants (think Primark, Poundstretcher, Sports Direct, etc) i.e. retailers that are not affected by the internet, and trade well in times of weak consumer demand - very important right now, as real disposable incomes are under a lot of pressure.
Funds from the recent large Placing are being put to good use. They announce today that a JV has been set up to acquire the Hillstreet Shopping Centre in Middlesbrough, which is being acquired for £50m, on a fabulous rental yield of 9.6%. New River's business model couldn't be simpler - they borrow money at 4%, and use that plus equity to buy assets yielding 9%. They also improve the assets through prolific common sense actions to improve the tenant mix, draw more customers into the centres, etc.
I saw the veteran CEO of New River, David Lockhart, present a Mello Central investor evening, and it was certainly one of the most impressive presentations I've ever seen. These shares should not be at a discount to NAV, they should be at a premium, in my opinion. NAV should rise to about 300p per share, from value adding work in the pipeline, and longer term rents will begin to rise again (although the pressure is if anything downwards at the moment). Plus they pay out a stonking dividend yield of about 7.5%. So in my view this is a great stock for a long term pension fund, as you'll not only get a terrific, tax-free yield, but should also make a good long-term capital gain too.
As with everything in these reports, these are just my personal opinions, and absolutely NOT any kind of recommendation. As always, please do your own research & take suitable professional advice.
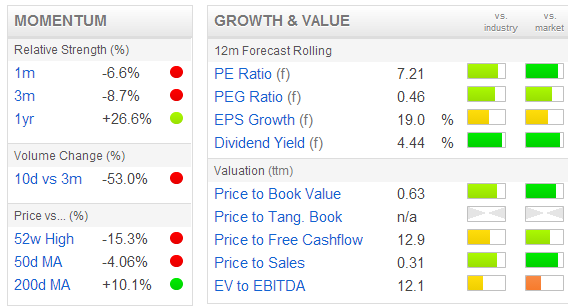
Cello (LON:CLL) is a marketing group that I've written positively about here before, although I do have concerns about their weak balance sheet. It pays a good dividend though, and the PER is low.
Anyway, they've issued a positive trading update today, which largely reiterates the points made in their 14 May statement. They confirm "robust trading" for H1 (six months ending 30 Jun 2013), and confirm expectations for the full year. So looks pretty good, and might be worth a deeper look? The shares are up 3p to 53p today.
I won't repeat my comments on Cello from previous articles, but for anyone interested you can refer back to them where I went into more detail about the Balance Sheet here (14 May), and here (13 Mar). Incidentally, you can check the archive here easily by just searching by ticker in the search box on this page, or clicking on the "Discussion" tab on any StockReport.
Oh yes, I forgot to mention, Cello also state today that "net debt is better than management expectations, following continued strong conversion of profit to cash". Pity they didn't quantify it, but it's still a positive.
Next I've been looking at preliminary results for the year ended 31 Mar 2013 for an upmarket bathroom fittings company called Samuel Heath and Sons (LON:HSM). Their products look wonderful, but I can't say the same about their accounts.
Their shares have fallen 14% to 297p today, so with 2,534,322 shares in issue, that gives a current market cap of £7.5m. As we're in a bull market, and the economy is beginning to improve, I'm being more flexible about market caps, and am prepared to look at things below £10m now, providing they have a sound business.
Although looking at the shareholder list, it seems that the free float is very small - with most shares being in the hands of family members, so the shares are likely to be extremely illiquid, and the risk of a de-Listing quite high if the family decide that it's not worth the costs & hassle of being Listed. Market Makers are only up in 250 share quotes too. Oh dear.
Anyway, they delivered £10m turnover, slightly up. Operating profit of £398k is down, and the outlook doesn't sound great. Also there's a nasty pension deficit, which is requiring £350k in annual cash overpayments, so this doesn't look good value I'm afraid. The one good thing I can find is that the dividend has been maintained at 11.75p for the year, a yield of 4% - not bad.
I think the downsides here substantially outweigh the positives, so let's move on.
Oil industry consultants & software company, KBC Advanced Technologies (LON:KBC) have issued a trading update. It sounds positive, with the key sentence being:
Following a strong first half, the Board is confident that it will maintain momentum during the second half and that the Group's performance for the full year will be in line with management's expectations.
Broker consensus is for 7.3p this year, so at 74p that puts the shares on a PER of about 10.
The forecast dividend yield is 2%. There was also a big cash balance here, but a lot of that was due to a customer paying a large fee up-front, so personally I would adjust the cash down for that before calculating Enterprise Value.
It's striking that a Director's investment company has been hoovering up huge amounts of shares in KBC, so he must feel pretty confident. I suspect this one might be going higher in due course, but we'll have to wait & see.
Last time I looked at Ubisense (LON:UBI) on 22 Jan 2013, I wasn't impressed. However, the shares are a little lower now, and the newsflow is starting to get interesting. They announce a contract win today, which isn't material at E1m, but gives some useful background about their technology - which allows companies to track everything inside their facility, hence improving productivity. Sounds a useful product, and it clearly works well, as it's installed at 4 out of the 6 major European car manufacturers.
They've also issued a trading udpate today that says H1 of 2013 has seen record order intake of £17m, up 83% against the same period in 2012. It had net cash of £2m at 30 June.
The Board say they are confident of meeting expectations for the full year, but that's only very modest profits of £0.8m, or 2.37p EPS. That means at 193p the PER is stratospheric at 81, although you can't really value growth companies that are near breakeven on a PER basis, it's future profits that matter, not the turnaround year.
I need to find out more about this one - in particular whether revenues are recurring, or just one-off licence fees. Also what growth is in the pipeline, what is their competitive position like? So it needs more work, but my interest has been sparked at least.
Time for my 11 am email to go out, so I'll sign off now.
Regards Paul.
(of the companies mentioned today, Paul has long positions in KBC, and NRR. He has no short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

21 comments
Paul, thank you for the response, I did not realise the dividends issue regarding REITs.
many thanks
Paul
why don't the normal rules on dividend cover not apply on a REIT ?
I'd never go near one again because of the forced lack of dividend cover. A lesson I learnt the expensive way after a near total wipe out on the Mapely REIT a few years ago.
REITS live in the real world of cash flow just like other companies.
I think you are too harsh on QPP. At this price they can make the odd mistake
One advantage that we have up here in the Grimm North is that everything is alot more reasonable price wise (can still get a pint in my local Thursday night and Sat afternoon for £2.00) so less spent on buying a house and a pint of beer (or 57) and takeaway at the end of the night and less (nowt) put into a pension at the end of the week = more money to spend in the local shopping mall on a nice new bit of tat - although if the Wallsend Mall is the town centre one it was very run down last time i went past so will mainly be restricted to locals - but being in the town centre it will always be right location to ensure they have enough customers passing by to make it worthwhile for someone to open summit there - better in town centre than in the middle of nowhere if the quality is a little less than on offer elsewhere.
Hello Millaree
Just to let you know the Forum is being tarted up as we speak. The old Co-Op is becoming a new library, and a new extension will be built on part of the car park. The structure allows these renovations to be done quickly and cheaply. The anchor tenant will be the local council. This is a VERY smart move. I missed the boat here!
Hello Paul,
Re: New River Retail
I have no experience of working in a retail business and only a little in property. However, my instincts still tell me that E-Bay and/or Amazon would make much better investments for a long-term pension fund than New River Retail. I would not want the progress of my investment to be dependant upon the growth of disposable income in Wallsend and err... Middlesborough.
Regards.
Bonitabeach
Interesting to note the success of the MetroCentre in Gateshead near Newcastle upon Tyne which has more than 340 shops occupying 2,930,000 square feet of retail floor space, making it the largest shopping and leisure centre in the UK.
Hi Bonitabeach,
Well it's that prevailing mood which is why NRR is able to buy properties on such attractive rental yields!
It's true that internet sales have made a dent in traditional retailing, but only in certain product areas. The internet has not made any impact on value retailers (e.g. Primark don't have a transactional website, despite being one of the UK's largest clothing retailers), and things like pound shops satisfy a need in some people on low incomes to just buy stuff, e.g. cheap toys for their kids, household basics, etc. That business will never go online.
Shopping Centres are morphing from purely shopping locations into meeting places as a leisure activity, and the food/drink offering is becoming far more important. As are cinemas, etc. Ladieswear is still very dominant, as people want to try things on. Many retailers are moving to a click & collect model, so shops become a hybrid between a traditional shop, and a collection/returns office. Much easier to try it on in the shop, and reject it if it doesn't fit, than having to drag yourself to the Post Office to return it by mail.
NRR are doing things like installing free WiFi in their centres, and installing Amazing collection lockers, to drive footfall. Coffee outlets as meeting places are very popular now, and so they're building a unit for Costa in one centre, having surveyed local people as to what they want.
I wouldn't normally touch a bog standard retailing property company right now, but having met them I've understood that New River are taking a really innovative approach to it, which works. The amount of activity they have going on to maximise the value of their centres is breath-taking, pages & pages of activity was explained on the slides they showed us. They are building a new store for Morrisons for example in surplus space outside one centre, and the build cost is £7m, it's pre-let, and the capital value once it's built will be £30m! This means that you will see NAV rise over the next few years.
Another example, they combined two large units in another centre they bought, and then let it to Primark, who of course generate massive footfall.
You need to get into the detail with New River before it starts to make sense.
Cheers, Paul.
Re: NewRiver
Would not the wafer thin dividend cover cause some concerns regarding the sustainability of the dividend?
Hi dosn,
No, the dividend cover on NRR is not a concern, because it's a property REIT, so in order to maintain its tax-free status, it HAS to distribute 90% of profit in dividends. Therefore the normal rules on dividend cover don't apply, as it will always be just about covered by earnings. But this means you'll get higher divis as the earnings grow (over the very long term, I'm not expecting any increase in rents in the short term).
Cheers, Paul.
Re QPP
I guess if you set your expectations low then its fairly easy to beat them.
I think they went from £16 mill net cash (31/12/12) to £14 mill net debt - so the actual cash position looks to be much worse than the operation cashflow which broadly neutral - albeit £35 mill worse than achieved in 2012.
Any they also expect margins to reduce by possibly 10% in the future - that isn't exactly going to aid cash collection.
And there is the continual increase in shares issued that means they need to be generating ever increasing profits simply to stabilise EPS.
Hi Paul. Hope you are well and working from the garden in this fantastic weather! I am very interested in Avation (AVAP) which manages and leases aircraft. It has a fleet of 23 aircraft and seems to be valued quite cheaply - PER of 6 and PEG of 0.29. I was first drawn to this company because Mark Slater has a holding. I would be interested to hear your thoughts on this one. THANKS!
Hi Paul
I have also been a fan of NRR and topped up this morning in my SIPP on a 'buy and forget' basis. The div is fantastic.
Just one thing that is nagging me. Looking at their march 2013 annual report, they report debt interest as just over 60% of operating profits. I don't fully understand the REITS sector, but this seems to me pretty high leverage. Wouldn't take much to wipe out net profit. Would appreciate your views.
Regards, Ram
Hi Ram,
From the presentation by Newriver Retail (LON:NRR), I recall that they had every risk buttoned up. So interest rate risk is covered by caps, etc. Therefore the business model is pretty solid, they just buy assets yielding 9%, and borrow money at 4%. I think their LTV is something like 50%, so together with the interest rate caps, etc, means that there really shouldn't be a problem when interest rates do rise.
Rents of course are fixed on standard leases, with 5-year upward-only rent reviews, on typically 15 year leases. Their voids are low, and the tenants are value orientated retailers, so tend to do well in economic downturns.
They've really thought about everything, and structured the company accordingly. Superb management, absolutely superb. Down to earth too, not the usual gravel-voiced BS merchants that you find in the property sector!
I completely agree that New River is just a buy & forget share. Not racy enough for most, but sitting back and getting a 7.5% yield at low risk, and knowing that management are working hard to increase the asset values over the long term, is a good place to be for a long term portfolio like a SIPP. The yield should be inflation protected too, in the long term, making it even more attractive. Being a REIT, they must distribute at least 90% of profits as dividends, which is an excellent structure in my view.
These guys set the company up & are buying assets at the perfect point in the cycle, when the spread between primary & secondary property rental yields is at an all-time high, and they are choosing the assets wisely - with the right type of tenants, and with development potential too.
Cheers, Paul.
Fantastic. Many thanks. Ram
Good morning Paul Quindell Portfolio (LON:QPP) expected an Out flow of cash between £15 to £20 million, they actually reported £2.3m Inflow of cash, this is a very significant improvement over what they guided.
Extract for clarity, I fail to see what is wrong with this, the cash can only have come from Debtor or am I wrong?
"...Adjusted operating cash flow for the half year significantly ahead of expectations and guidance with £2.3 million inflow compared to guidance of £15-20 million outflow during significant growth in H1 ... - See more at: http://www.stockopedia.com/content/quindell-a-great-british-innovator-and-job-creator-now-with-fy13-forecasts-73640/#sthash.1Sx6i5QV.dpuf
Hi Steamy,
Point taken that Quindell may be ahead of what was planned on cash inflow (when they were expecting an outflow), but as we have seen with other companies in this sector in the past, rapid growth can hide a multitude of sins. It's only when the growth stops, you realise that they're not generating any cash, but have reported huge profits and then have a huge debtor book.
This time it may be different, but I'm not prepared to take that risk. The PER of 5 says that a lot of people are similarly cautious!
Regards, Paul.
Hi Paul
I was just reminded of the danger of investing in highly acquisitive companies with the conclusion of the final SFO court case against Torex Retail. Two of the exec directors had pleaded guilty of cooking the books. The third pleaded not guilty and was a few weeks back found guilty. All three are doing porridge. Shareholders lost all, but the banks managed to get back their capital. For two years before a senior manager became whistleblower, the execs went into a buying binge. To my recollection, no share analyst seriously questioned this strategy or their accounts. I too burnt my fingers losing 25% of my investment, which is my built-in stop loss.
For the avoidance of any doubt, I am not drawing any parallels with Quindell except for the highly acquisitive strategy and the dangers this entails. Just to balance my comments, I am sure people can find other examples where companies have gone on to become bigger and better companies.
Regards, Ram
Ramridge - I too had shares in Torex (I held XN Checkout when it was taken over by Torex).
There's a nice summary of the sentences here: http://www.complianceweek.com/sfo-wins-conviction-in-torex-retail-false-accounting-case/article/300463/
Personally I'm glad the SFO is getting tougher on Directors doing this type of fraud - and, like you (and Paul), I'm very dubious of any companies growing through acquisions of other companies (as opposed to buying products etc) - there's just too much scope for adjustments etc. Also, combining this with software companies, many of whom have dodgy amortisation / goodwill policies and revenue recognition - lends me to avoid companies like Quindell.
Paul, what do you think are the best type of screens on Stockopedia to avoid companies like these? Or indeed take a short position?
Good to see Newriver Retail using recent fundraising in such an efficient manner. Certainly if there were any doubts about the placing, then this purchase should be a confidence booster. As an aside personally I like the investment they are putting in the north east namely Wallsend and now Middlesborough - long may it continue.
i would guess that someone employed by Quindell reads this bulletin board. Let's see if they respond to investor concern and release the information on debtor days.