Small Cap Value Report (17 Mar 2016) - SKP, CLL, QRT

Good morning!
An interesting Budget yesterday from George Osborne. I won't cover that here, as there are any number of other places where summaries and analysis can be found.
SkyePharma (LON:SKP)
Share price: 427p (up 3.3% today)
No. shares: 104.8m
Market cap: £447.5m
(at the time of writing, I hold a long position in this share)
Results y/e 31 Dec 2015 - sparkling results were published yesterday for this, "expert oral and inhalation drug development company". Pharmaceuticals is a sector I normally avoid, unless the figures are easy to understand, which they are in this case - SKP has ticked the right boxes to be considered a good GARP (growth at reasonable price) share for some time. It's one that I've written about here 10 times before.
Pre-exceptional EPS rose from 17.5p in 2014, to 25.1p in 2015. Even after recent rises, the shares don't look particularly expensive to me, at a PER of 17.0 times, although there are lots of moving parts with this company's accounts - e.g. milestone payments, etc. So it really needs more in-depth analysis which is beyond my pay grade in this sector.
I've always thought SKP would, sooner or later, make a bid target, and that's what's happened:
Recommended merger - also announced yesterday. The boards of Vectura (LON:VEC) and SKP have reached agreement on an all-share merger, whereby SKP shareholders will receive 2.7977 Vectura shares for each SKP share. There is also a partial cash alternative.
Personally I'm not at all happy about this. I don't want Vectura shares! I want to keep my SKP shares. So it will be interesting to see how the shareholder vote goes.
With any luck, this not particularly good merger deal might smoke out a proper bid (at a decent premium) for SKP.
EDIT: A further point that I forgot to include before, is that all-share mergers can be problematic. The trouble is that often there is part of the acquired company's shareholder base that doesn't want shares in the acquirer. So they sell in the market. That can cause a terrific overhang of shares, which can last a very long time.
I noticed this happen when Matchtech (LON:MTEC) bought Networkers Intl in Apr 2015, and the share price has never recovered - even when MTEC puts out good news, any rise is almost instantly snuffed out by sellers - probably former Networkers shareholders.
Let's hope the same thing doesn't happen with the SKP/VEC deal. Although I am told by a contact of mine who's knowledgeable in the sector, that Vectura is a very good company. Although it's also on a very high rating - much higher than SKP.
I'm tempted to sell my SKP shares in the market before this deal goes through. It's only a small position anyway, so would remove a worry getting rid of them, banking a profit is always nice anyway.
Cello (LON:CLL)
Share price: 96p
No. shares: 85.3m
Market cap: £81.9m
Results y/e 31 Dec 2015 - I last looked at this marketing group this time last year, and flagged up in this report how the company makes enormous adjustments to move from relatively modest statutory profit, to adjusted profit approximately 2-3 times the size!
Well they've done it again! For the third year running now, a whole load of adjustments are made, to inflate profit by a material amount;
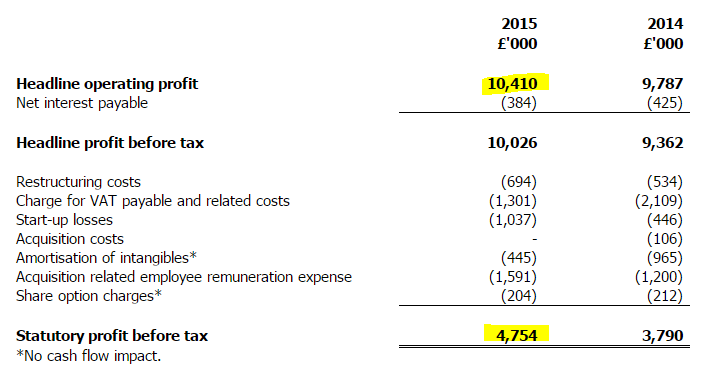
So I think the adjustments are so highly material, and repeat every year, that the adjusted figures completely lack credibility in my view. Therefore, I think it would be a mistake to value this share based on its adjusted EPS figures.
Basic EPS is only 3.54p, and even if you move that up to about 4p, to allow for reversing the amortisation charge, that still puts this share on a PER of 24 times - i.e. very expensive.
Balance sheet - quite weak, and dominated by intangibles. NTAV is negative, at -£2.9m
Outlook - sounds confident;
The Group began 2016 with a robust level of secured forward bookings. It has also seen encouraging levels of new business wins so far this year. At this relatively early stage of the year, the Board is confident that expectations for 2016 will be met.
Dividends - not bad. The forward yield is just over 3%.
My opinion - you have to be so careful with the accounts of marketing/PR groups, because it's basically their job to create a misleadingly positive impression, for clients. So the same mentality goes into the preparation of accounts.
These figures are a bit of a joke - 3 years on the trot putting through enormous adjustments to profits, has blown their credibility as far as I'm concerned.
It's not a bad business, but the reported accounts greatly overstate the true level of profitability, in my view. The market is not questioning the adjustments, and is hence over-pricing the shares I think.
Quarto Inc (LON:QRT)
Share price: 252p (down 5.8% today)
No. shares: 19.7m
Market cap: £49.6m
Results, y/e 31 Dec 2015 - the P&L figures look pretty good;
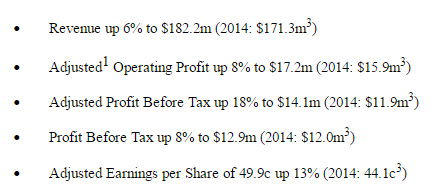
I've had a look at the adjustments to EPS, in note 6, and they look reasonable (and relatively small), unlike the last company I looked at above.
Valuation - so taking 49.9c, converting into sterling (at £1 = $1.439) arrives at EPS of 34.7p. With the share price at 252p, that gives a PER of 7.3 - very cheap on the face of it.
Why is the PER so low then? I think it's partly because of investor scepticism about book publishing. Although it seems remarkably robust to date, technology is advancing so fast, that who knows, in a few years there might be much bigger/better iPad-type devices which drive further declines in book publishing. I don't know, but this has to be a factor holding back shares like this.
The PER is also low because of Quarto's balance sheet issues - it's got far too much debt basically, so let's take a look at that next.
Balance sheet - I still don't like it, but things are improving. Net debt has reduced by 10% to $59.5m. Although gross debt seems alarmingly high, at $84.6m, but is partially offset by $25.1m in cash. I don't see the logic for simultaneously having a large cash balance, when you're paying interest on debt at the same time. Surely the logical thing to do would be to repay some of the debt, using that $25.1m cash pile?
I also very much dislike the $59.4m of capitalised "pre-production costs" within fixed assets. This gives rise to a greatly inflated EBITDA figure, which is best ignored in my view. I'd be much happier if pre-production costs were written off as incurred.
Dividends - total divis for the year are up 6% to 14.5c, or 9.5p. That yields 3.8%, although I'm not keen on companies with lots of debt being generous with dividends.
Outlook - second-half weighting emphasis might have spooked some investors today possibly?
The Group is well-positioned to deliver continued earnings growth in 2016. We expect this to manifest itself in the second half of the year; the increase in second half weighting experienced in 2014 and 2015 is in line with continuing global retail trends. Visibility gained through our forward order books and the recurring revenues of our business model gives us confidence in our ability to continue the momentum of the last three years as we execute our business plan.
Quarto remains a cash generative business and we are committed to reducing our net debt, including by resolutely examining the strengths and weaknesses of our portfolio with a clear focus on our working capital. Continued reduction in net debt will further enhance our options to build on the strong platform that has been created in the last three years and prior. As we further develop our business to take advantage of growth areas and the acquisition opportunities that are presented to us, thereby increasing the Group's earnings, we will progress the Company's dividend in the second half of the year, as we have done in 2014 and 2015.
My opinion - I'm warming to it a bit, or perhaps am less averse to it. Some interesting snippets in the narrative today, indicating that non-core businesses could be disposed of. That might sort out the excessive debt, and gives them flexibility if the bank ever did get the jitters.
I'm hopefully having a telecon with Marcus Leaver, the CEO, next week, so will report back on anything interesting.
It seems to me that Quarto is trying to balance up several conflicting forces - they need to reduce debt, but also need to spend money on acquisitions, to boost declining sales of older titles. They're also under pressure from shareholders to pay increasing divis. It's a delicate balancing act.
I've run out of time for today now, as have to jump on a train back to Hove.
See you tomorrow.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

20 comments
FCCN
Grumpy5 -- yes, I have overlooked his appointment as an NED. Some digging shows he was Group Product Director for Next for at least 10 years until 2014, when he left for Abercrombie & Fitch.
Guardian said when Mr Angelides left for A&F, that he was the "power behind the throne" at Next.
http://www.theguardian.com/business/nils-pratley-on-finance/2014/jun/10/next-christos-angelides-abercrombie-replace
Anyway, Bloomberg says he was fired from A&F in late December last year:
http://www.bloomberg.com/news/articles/2015-12-22/abercrombie-executive-angelides-is-fired-removing-ceo-contender
Mr Adderley then declares a notifiable FCCN holding in early January, and Mr Angelides then turns up as a non-exec this week. Coincidence?
I now wonder too whether Marks is lining up Mr Angelides as a successor. That must be the case, surely...!
Re FCCN it's the appearance of Christos Angelides as a NED that excites me. For many tears he was the star behind Next's product selection, and I am wondering whether the fat old nutter Marks is lining him up as a successor.
RNS just out that WA Capital have increased their holding beyond 7%. The plot thickens...
http://www.investegate.co.uk/french-connection--fc...
FCCN
It's a shame Paul has missed FCCN's results, as he has decent sector knowledge and it is one of his higher conviction holdings (at least going on his SCVR-based fund).
Anyway, the appearance of Will Adderley, the son of Dunelm's founder, on FCCN's shareholder register is probably the best news FCCN shareholders have enjoyed for years.
We could all be adding 1 plus 1 and getting 5 here, but Adderley has vast retail experience and connections, and could buy FCCN with 'loose change' (he owns 30% of Dunelm, a stake worth almost £600m) .
The issue with FCCN is founder/42%-owner Stephen Marks is now past it (at least going on FCCN's dismal results since 2007-8) and no-one has had the inclination/power to turf him out. Adderley could (or should!) be just the man to make it happen.
FCCN does have a 'home' retail operation selling fancy tables and furnishings, which I always thought was upmarket when compared to Dunelm. But maybe there is potential for Dunelm to sell tea-towels etc in FCCN's Oxford St store? Who knows. At least Adderley has been a buyer this week and sees something in FCCN's stock.
Standout performer for me today was Capital Drilling (LON:CAPD) http://www.investegate.co.uk/capital-drilling-ltd--capd-/rns/full-year-results/201603170700083361S/
"
Long term production contracts are a strategic focus for the Group due to the unique level of stability and visibility they provide within a sector beset by uncertainties. Currently over 70% of Group revenue is derived from long term contracts. Combined with the recent success of the Group’s new Lean Operating Model, targeting the exploration and delineation sectors, Capital Drilling is well placed for growth in the years ahead.
The Group’s financial position is its strongest since listing on the Main Market of the London Stock Exchange in 2010. Management’s strict focus on cost and capital discipline has resulted in record free cash flows being recorded in the past three years, increasing to $14.4 million in 2015. These cash flows have enabled us to de- gear the balance sheet and pay our first dividends since inception in 2004. A total of $4.0 million was paid to shareholders over 2015, while gross debt reduced to $5.1 million, with closing net cash at $8.3 million, versus net debt of $0.4 million in 2014.
In line with the Group’s solid financial and operating position the Board of Directors have declared a final dividend for the 2015 period of 2.5cps (US$3.4 million), payable in May 2016, representing a 32% increase on the 2014 final dividend."
So a near 10% yield and returning to growth and profit this year, I'm a happy holder and bought a touch more when the price fell back this pm. The stockopedia score is 98 so I guess I'm not too wrong to be holding.
Two posts numbered 4..interesting..
NI
Hi Paul
Any comment on Bill Adderley, Dunelm Dunelm (LON:DNLM) founder building up a stake in French Connection (LON:FCCN)
From yesterday RNS Adderley's WA Capital has now built up a 6% stake
http://www.investegate.co.uk/french-connection--fccn-/rns/tr-1--notification-of-major-interest-in-shares/201603161216383080S/
He will likely be looking to have an input into the direction of firm.
I have a small holding in Dunelm (LON:DNLM)
another £1M in value buy went through today so watch out for another announcement
Interesting developments here. May be just a simple PA investment by Adderley, but could also be an interesting tie up. French Connection (LON:FCCN) offloads its loss making retail units and long term leases ahead of schedule to Dunelm which is still expanding its network, especially into the SE. Dunelm (LON:DNLM) then gains access to French Connection (LON:FCCN) branding and merchandise while French Connection (LON:FCCN) rolls out its brand license through Dunelm stores throughout the UK. Win win all round (and my French Connection (LON:FCCN) shares go up too). Maybe adding 1 plus 1 and getting 5 but stranger tie ups have happened in UK retail recently.
Gus.
I see French Connection (LON:FCCN) are down 12% today, any idea whats going on?
I have been watching Norcros (NXR) closely as the share price has fallen from around 200 to around 165. The most recent reports have suggested improved earnings and a possible EPS of 23p. Indeed the interim dividend was raised from 1.8 to 2.2. Since the reports, South Africa has suffered an economic downturn and NXR has a third of their business by value there. No RNS has been issued so I took the liberty of telephoning the Company and spoke to the CFO. After asking him about current conditions, he agreed that their overall earnings were in line with expectations and if they were adversely affected, the Company would have to warn the market.
I was already a shareholder in NXR but decided to buy some more on two recent occasions.
In addition, an RNS has been issued yesterday announcing that Miton now hold 17.5% of NXR.
I agree with Paul about SkyePharma (LON:SKP), its not a sector I usually invest in, I was keen on SkyePharma (LON:SKP) but have no desire to own Vectura shares, I thought it was a done deal so I sold out on today share rise. Mergers do not always go well but seems Vectura have done a good deal though, a takeover would have cost them rather more.
Despite Quarto's rise over the last couple years I think it is as good value as it has ever been. The debt reduction should give investors comfort, and of particular note is the performance of new books. Their model always has been to produce books which have longevity and drive sales long beyond the first year of publishing, and the group is getting better at tracking and ensuring this value is created.
They continue to grow publishing organically and have a very resilient niche (illustrated, large format), as well as a geographically and functionally diverse range of products.
The clean-up of the shareholder register earlier this year, and the resignation of two of the activist investors on the board, bring to an end one chapter of the group's history. I think in this new chapter, people begin to realise that this is a solid, high-quality, cash generative business, not one fighting to clean up its balance sheet. The set of challenges it brings is different, too - now, as Paul notes, there is more discretion on what can be done with capital, and more of a discussion about what the correct allocation is.
I think the current price still under-rates a good business. I hold.
Paul. Do you fancy taking a look at Safestyle? (SFE) Cracking little company who do one thing really well. Finals today are noteworthy.
My own view is SFE is starting to look expensive although I agree it seems like it is well-managed as a business. It's now priced at 15 times 2015 earnings.
I don't like how they operate.
I agree that I don't like the way their sales teams work - at least the ones that have knocked at my door. I would never buy from them and in this case that stops me buying into the company.
Re. Cello (LON:CLL) The use of 'headline' numbers is annoying because there is no agreed convention as to what a headline figure should be, and so companies then make up whatever definition that suits them.
In this case, they have have defined headline earnings to mean EBITDA less amortisation and depreciation.
They then go on to provide a "headline" eps of 8.39p. A totally meaningless and misleading figure (against a diluted eps of 3.44p). Just a clumsy subterfuge to puff up the numbers.
Hello Paul
Finsbury foods (FIF) interim results yesterday looked good and have taken a small position. If you have time please could you take a look through them and share your opinion?
Thank-you
Hi Paul,
I'm a holder of SkyePharma (LON:SKP) and have mixed feelings about the merger. I think the shares may have risen more yesterday without the merger due to the very good results they just released. On the other hand, Vectura also looks pretty good, and I'm sure that there will be a lot of synergies between them.
The merger looks like a done deal to me with both companies recommending it and big shareholders in both companies supporting it.
Is there any particular reason that you don't want Vectura shares?
Re SKP - I am long VEC - so happy about the deal!!
Did wonder about the VEC share price moving down over the last couple of weeks - obviously somebody was in the know. Probably some US group will wait until the "merger" is completed and then bid for the entire group - it would then be a sizeable acquisition - circa £1.1billion - and then realise the cost savings