Small Cap Value Report (17 Nov 2014) - OPAY, LTC, CAMK, MJW

Good morning!
The Equities First Holdings scandal continues - I note that Optimal Payments (LON:OPAY) has come out with guns blazing this morning, issuing a reassuring trading update, and making further comments re the incorrectly disclosed Director dealings via EFH, saying;
In relation to the loan and pledge agreement I entered into with Equities First Holdings, LLC, I can confirm that I entered into the agreement outside of a close period, the loan was taken for the purposes of liquidity and it is my absolute intention to repay the loan when it falls due.
The main problem with the EFH "loans" is that they are not really loans at all. Legal title to the shares is transferred to EFH by the Directors entering into these transactions, in return for a payment. That is a sale, simple as that. It would undoubtedly trigger a CGT tax liability. However, it is a sale combined with an option to repurchase the shares at an agreed time & price.
Another key issue is that EFH "loans" are non-recourse. Therefore, the Directors concerned are NOT obliged to repurchase the shares at all, it's entirely optional.
So these EFH facilities should be disclosed as a Director sale, with all terms disclosed. The Directors who look particularly bad over this EFH scandal are the ones who tried to window dress these sales as if they were purchases - i.e. making simultaneous buys of shares, in order to make it look like a Director purchase, rather than a Director sale. That stinks to high heaven! I believe that at best, these Directors have been very foolish to transact with EFH.
Some similar transactions with UBS were flagged up over the weekend, with 3 fully listed companies, including Telecity (LON:TCY) for a Director who has since left apparently. I looked into these 3 Director loans (secured on shares they own), and they look different to the EFH deals to me - the key difference being that the stock is only pledged, but not transferred to UBS unless/until a Director defaults on repayment. So those are not a disposal of shares, they are just borrowing against their shares, using the shares as security. Very different.
Latchways (LON:LTC)
Share price: 731p
No. shares: 11.2m
Market Cap: £81.9m
Consulting my previous notes here, which you can do by following the steps shown below;
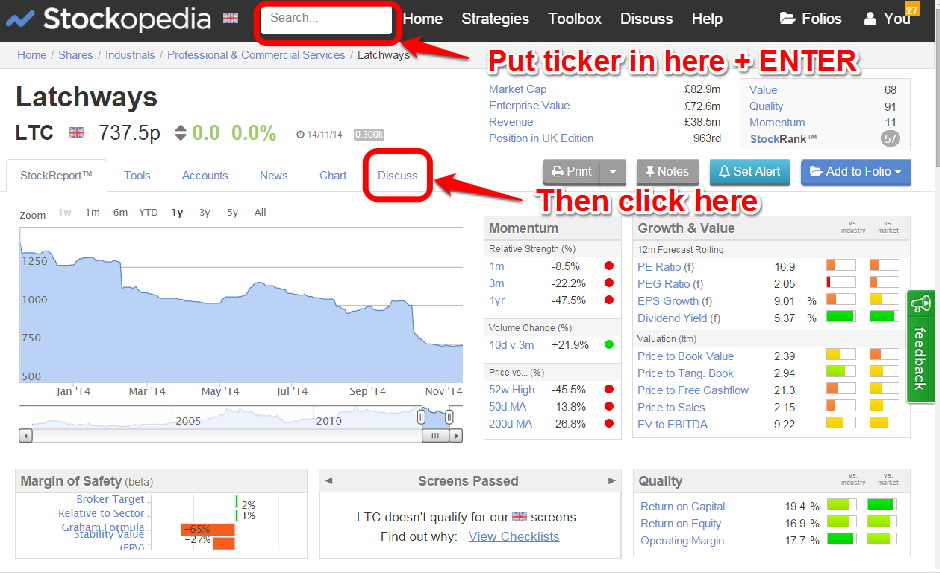
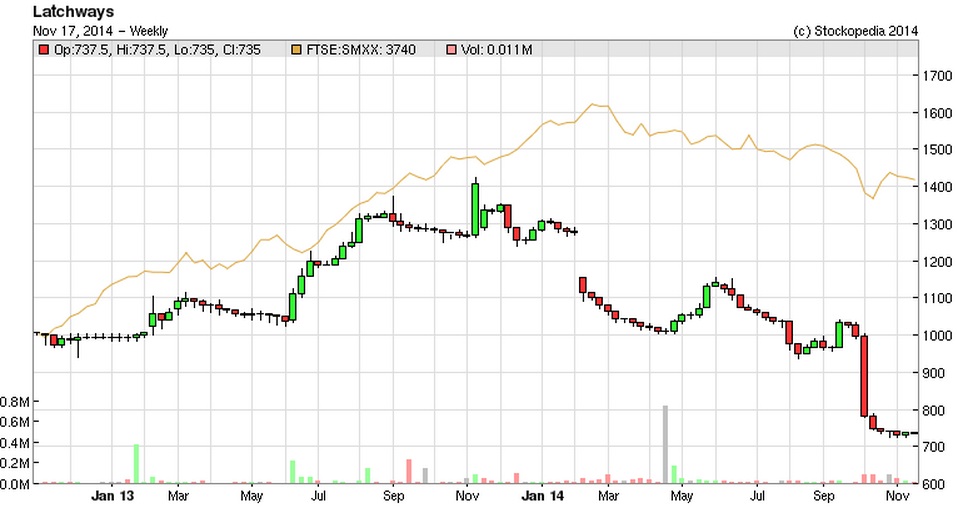
My last report on Latchways (a safety devices maker) was here on 7 Oct 2014, reporting on a rather nasty profit warning. At 830p I concluded that the valuation looked expensive, based on much reduced earnings outlook for the current year ending 31 Mar 2015. That was the right decision (not to buy), as the price has since dropped by another 99p.
Interim results - for the six months to 30 Sep 2014 are published this morning. They seem to be in line with expectations - delivering 17.3p basic EPS for H1 (none of this adjusted nonsense, I'm pleased to say). Double that to annualise it, and that's about 35p EPS, which is exactly what I guesstimated in my last report. on 7 Oct. Broker consensus is 33.6p for this year, rising to 49.4p next year.
Outlook - I can's see anything much in this outlook statement to justify the big increase in EPS forecasts for next year, this all sounds a bit waffly;
We share our investors' disappointment in these results. Economic activity in Europe will take time to recover and therefore we are looking elsewhere for growth. The other setbacks that we have suffered this year are temporary in nature and are in the process of being resolved. In the meantime the underlying business remains robust with strong cash flows and a solid balance sheet.
Looking to the medium term, we see significant potential for our existing products such as Wingrip and our Vertical systems given the groundwork currently being laid with new prospects, whilst our ground-breaking new products provide us with the wherewithal to change the face of the global SRL market. International prospects offer growth opportunities and we are reshaping our sales team to realise this potential. North America remains a core market which will resume growth once current overstocking issues have worked through.
Valuation/ My opinion - due to the somewhat half-hearted nature of the outlook statement today, I can't justify factoring in any recovery of earnings yet. Hence I would be inclined to value it on a PER of about 12 times this year's earnings, so 12 * 35p EPS = 420p, plus a bit extra for the very strong Bal Sheet.
I think all the cash can be regarded as surplus, since there is plenty in stock & debtors (debtors look a little too high actually), so net cash of £10.4m is 93p per share, so adding that on to the 420p above, I would value this company at 513p. That's 30% less than the current share price. So effectively, 30% of the current share price is a premium anticipating a recovery in earnings. Is that reasonable? I don't think so, so will pass on this one. It's going on the watch list, but I'm only interested at an entry price of c.500p.
Camkids (LON:CAMK)
Just a quick comment on this Chinese footwear maker, as I have a blanket ban on all Chinese companies in my portfolio, because the figures cannot be relied upon.
Trading update - the company warns on a deteriorating outlook for 2015 for the Chinese economy.
I'm surprised that the shares are down 23% today, as the PER of 1.8 suggests that the market didn't believe the figures to start with.
I maintain my bargepole rating on this, and all other Chinese stocks on AIM. Surely de-listing is the inevitable end game? Maybe the odd one might be genuine? But how can you tell? Why take that risk at all?
Majestic Wine (LON:MJW)
Interim results - for the six months to 29 Sep 2014 are out today. Can't say they look inspiring in any way.
Profits are down a little, and the outlook statement talks about 2015 being a year of investment.
So it looks to me as if they are struggling to maintain their competitive position. There must be no end of competition from supermarkets relentlessly discounting, and online wine retailers with lower overheads than Majestic.
For that reason I imagine Majestic will be fighting a permanent uphill battle, and could see their own quite strong operating margin gradually erode.
On the other hand, the brand name is good, and many people would rather deal with an established bricks & mortar company, plus online sellers have heavy postage costs to contend with - plus sometimes bottles smash in transit, when you order online - it's not very nice to receive a parcel of shattered glass, in a wine-soaked cardboard box!
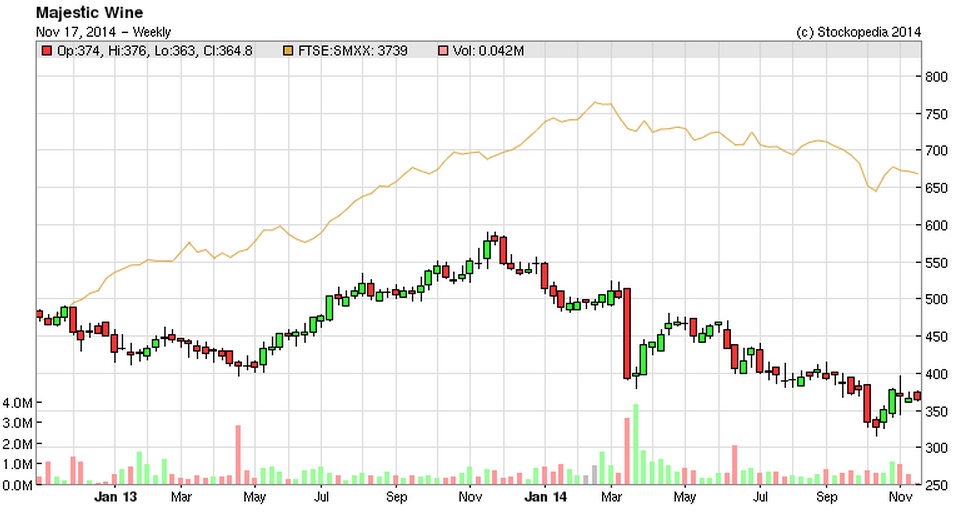
I can't get excited about it, even though the valuation looks reasonable, and the divis are good. This downtrend in the share price looks firmly established;
Nothing much else of interest today, so I'll sign off.
Regards, Paul.
(of the companies mentioned today, Paul has a long position in OPAY, and no short positions.
A fund management company with which Paul is associated may hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

20 comments
When Optimal Payments (LON:OPAY) agreed to buy MERITUS in USA in July 2014, it was agreed that part of the payment would be $60 million of Optimal Payments shares (issued in equal tranches over four years commencing on the first anniversary of the closing date). Does that mean that these will be new shares that are created? And to what extent will this mean that existing shareholders shares will be diluted in value?
I have no position in OPAY but out of curiosity I Googled the new CFO. He was previously Group FD of Telecity. From the fact that his pay off included an amount to settle any statutory claims he may have had against Telecity and coverage of his legal fees I presume that he was effectively thrown out. I know that sometimes people's faces simply don't fit any more but it's interesting anyway. I noticed that he won an D of the Year award in 2012 and was lefted by Telecity in 2013. He aso stayed on to help handover to his successor.
http://www.telecitygroup.com/our-company/news/2013/telecity-group-plc-board-change.htm
Hi all,
Another Mello Derby-gleaned point re Majestic ...and perhaps others : at least one keynote speaker volunteered that he felt a number of AIM share prices were 'underpinned' by investor support for their IHT value, as opposed to their underlying commercial merits.
Tax tails wagging investment (not yet) dogs springs to mind !
ATB
Hi Paul,
A couple of derby-gleaned points. One of the fund managers I chatted too had had a recent conversation with the Latchways (LON:LTC) FD and the story was that the reduced orders were mostly delays not cancellations. The FM felt that this year's was a blip in performance and didn't make a big difference to the true long- term value of the business.
In chatting to Software Radio Technology (LON:SRT) 's Simon Tucker he highlighted the £5m inventory they have to support future orders valued at cost. Given GM's of 50-60% this would be £10m+ of revenue. There's no obsolesce and he expected the vast majority of that to go out in the next 6 months or so, particularly when the US coastguard rule is published.
Ok, these are opinions and could be unduly optimistic but thought it was worth mentioning what the people running these businesses were saying.
Cheers,
Mark
If I were MJW's chairman I would be looking at a management refresh. The CEO and CFO have been there a very long time, and whilst corporate memory has its virtues, I think the business could benefit from some fresh ideas. The strategy at the moment seems to be more of the same.
Paul, don't quite see why you think Majestic are "struggling to maintain their competitive position" when they actually reported an increased market share in the announcement this morning. Perhaps you could explain.
Roger,
Because profits were down. So they may be maintaining market share (in sales), but their margins look to be slightly under pressure. I can only see that getting worse, can't you?
Regards, Paul.
Re Majestic. No the margins (difference between revenue and cost of sales) are up on the same period last year. The change is due to higher overheads/admin costs which was signalled and explained well in advance of the latest results.
Roger,
Gross margin may be up, but for me the only margin that matters, is the operating profit margin, which is clearly under pressure - from increased costs, or whatever.
I just suspect that competitive pressures are likely to see the net profit margin shrink here over time - supermarkets, internet, will all erode it probably, plus relentless increases in overheads, with no increase in demand. So it's difficult to see what there is to get excited about with these shares. Obviously you're long, so you see it differently! ;-)
I'd rather find companies where profits are going up, not drifting down.
Regards, Paul.
Hi all,
I am long Optimal Payments (LON:OPAY) and sadly topped up @410. Whilst I think the company is sound and that is the most important issue here, I have e-mailed their IR as I noted that the day after the transaction with EFH, the CEO purchased 80,000 shares. I have specifically asked what funds he used to purchase same.
Personally, I am of the view that this is simply a Tax fiddle - why is it that some of these CEOs see fit to pay hardly any tax? - Where are the SFO and HMRC?? Busy hunting the little people whi are asy targets I suspect!!
Regards,
Sully.
Surprised Paul that you didn't think SRT's interims of "interest" as you have commented on the company before and I believe the CEO was at Mello in Derby where I'm sure there was some interest from attendees.
Hi alterego,
Results from Software Radio Technology (LON:SRT) were (it seems in error) announced on Fri afternoon. I had a quick look, and the figures are in line with the trading update given a little while ago, so no surprises.
The outlook is uncertain - dependent on big contract wins, which may or may not happen.
I was impressed with Simon Tucker's presentations at Mello Derby, indeed I was the announcer & timekeeper for his two presentations. So buying/holding the shares now is a straightforward bet on whether the company can close the big orders which are in the pipeline.
I hope it works out, and suspect it might do, but the future is too uncertain for me to invest.
Regards, Paul.
thanks Paul, I understand your position. I'm of the view that the big orders will flow since there really isn't anyone else with the products and the sales channels to offer significant competition. SRT's problem is that it has to wait for large projects to come to fruition. A case in point is the USA where the mandate to require AIS on boats has been delayed and delayed. Finally though we appear to be less than 30 days from it becoming law. It's a biggie for SRT and will reward the patience us shareholders have shown. Thankfully SRT have developed products that do not depend on large Government backed mandates such as the Satellite data deal with Exact Earth and the 3d imaging suite from GeoVS. That bodes well for future revenues.
With the exception of QPP it would appear that the directors in Angle,OPAL et al have been seduced into a method of "cheap""loans" to finance reasonable personal requirements by dubious advice from the Company's NOMADs. This should not affect the actual trading futures of the Companies concerned other than a slight dent in confidence. Unless I am missing something should this not be a buying opportunity?
RE QPP
It may be an omission but Redleaf does not appear as the media advisor on this mornings RNS - just Bell Pottinger.
EFH sponsor some AIM events. Nomads were probably telling directors that this was a great way to get cash from your shares without affecting the share price as it did not have to be declared a sale. Directors started to do this and it was under the radar. Then Rob Terry and QPP got wind of it and, as usual, couldn't resist doing it in such an unsubtle and underhand way. By declaring it as a share purchase instead of a Director Dealing RNS and with QPP being subject to such scrutiny from investors and bloggers, the whole sordid episode has come to light.
I think OPAY and QPP are totally different. Is OPAY now a mis-priced bargain caught in QPP cross-fire? I think so, but I've been wrong many times before so DYOR.
Given HMRC are so keen on tax avoidance I guess directors doing their tax returns will be having a few sleepless nights thinking about their CGT liabilties ...
Hi Paul -
RE, OPAY. I understand that you have posted an open letter to TW on ShareProphets giving in detail your position and views on this share.
People in this forum might be interested in reading this as well.
Disclosure: I am long and topped up on Friday.
Hi Ramridge,
I just commented after an article on ShareProphets, I wouldn't call that an open letter!
TW is bearish on Optimal Payments (LON:OPAY) because of the Director loan done with EFH. I've researched the company, and in my view, whilst I agree that the CEO of Opay was unwise to get involved with EFH, it seems to me that he thought this was a cunning way to borrow money against his holding. I don't think there is anything fundamentally wrong with Opay at all - the company is profitable, growing, and there are no accounting funnies at all.
The only issue I don't like about Opay, is that it is highly dependent on one key customer, constituting 42% of turnover. That will fall, as mentioned in today's RNS, due to acquisitions in the US done recently, but it's still an uncomfortable risk. However, that's not new information, so should not affect the valuation at all, as it was already known.
Therefore in my view, a Director doing something unwise re his personal shareholding is annoying, but shouldn't affect the value of the company in the long run. You could even view it as a bit of storm in a teacup. Therefore, as Opay had been on my watch list for some time, getting the chance to buy in substantially cheaper on Friday, at about 330p, seemed to me an opportunity, if you're prepared to ride out short term volatility.
DYOR and all that, but this whole EFH issue can be seen as both a threat, and in some situations, an opportunity. The crux is whether the company concerned is fundamentally good, or bad. Everyone has to make up their own mind about that, and I listen to both bull & bear opinions on this and other issues.
Regards, Paul
Optimal (OPAY) - Saw them at Mellow-2014 Investor Conference in Derby and was impressed, so likewise, took the EFH controversy opportunity to pick some up at a far better price. I gather that they are interested in further acquisitions so the concentrated client base will diminish over time. Regards, Maddox
Hi Paul
Don't know if you have spotted this morning's QPP announcement - Cannacord Genuity resigned on 21st October giving a month's notice & have insited that this be broght forward to this morning.
Shouldn't it have been announced when they resigned?
Andy