Small Cap Value Report (17 Oct 2016) - BVXP, ZYT

Good afternoon!
I spent yesterday afternoon catching up on the backlog from Friday, and ended up digging into an AIM-listed Barbados hotel chain called Elegant Hotels (LON:EHG) . What an interesting company. I was tempted at one point to buy a few shares in it, but overall was put off by 2 specific factors - click here for that report. It's one for the watch list anyway, but I'm expecting profit warnings to come in 2017.
Bioventix (LON:BVXP)
Share price: 1485p (up 2.4% today)
No. shares: 5.1m
Market cap: £75.7m
Results, y/e 30 Jun 2016 - this is a terrific set of results. The headlines section is most impressive;
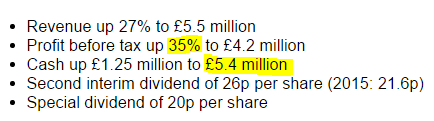
This company operates in an astonishingly profitable niche, with one of the highest net profit margins we'll ever see - profit before tax is 76.5% of turnover. I've wondered in the past if that would be sustainable, but so far, so good.
The barriers to entry seem to be that each new product takes years to develop & test. Also, the volumes are possibly too small to attract any serious competitors. Although such high profit margins do make me nervous, hence why I don't hold this share.
Well done to people that do, as its track record is absolutely superb, and shareholders must be delighted with today's figures. It's good to see some surplus cash being paid out in divis too.
Diluted EPS has risen strongly from just under 50p, to just under 68p - again, tremendously impressive. That gives a PER of 21.8 - a rich rating, but fully justified by these numbers I feel.
Balance sheet - is very strong. Although debtors looks too high at £2.7m. Considering the full year's turnover was only £5.5m, its customers seem to be very slow in paying.
I've just found an explanation for the large debtor balance in the narrative;
Approximately three quarters of Bioventix sales are generated from customer royalties. These are based on our customers’ global sales which are then factored by a royalty percentage and then sent to Bioventix around 2 months after the end of each half year.
In the first half of 2016, this mechanism resulted in $ based and Euro based royalties being converted into sterling around August at post Brexit exchange rates of approximately 1.3$/£ and 1.2Euro/£. As no hedging mechanisms are employed, this provided an additional uplift in reported sterling revenues compared to previous periods.
So the depreciation of sterling has been a help in boosting profits.
Outlook - it sounds like growth will slow in the new year.
We are delighted to be able to report such positive news for the current year. Furthermore, we remain optimistic that further modest growth next year will come from additional vitamin D antibody sales and royalties.
Beyond that, growth in the period 2017 2020 will be linked to our troponin project and the success of Siemens in their product launches around the world.
We continue our research activities as we look to seed additional projects that will germinate in the period 2020 2030 creating additional shareholder value.
My opinion - so far so good. It all hinges on whether profitability is sustainable, and what levels of growth will be achieved in future. A recent spike in share price was apparently caused by it being tipped in a tip sheet. Sometimes those spikes can wear off, as people get bored and drift on to the next hot tip.
Overall though, it's difficult to fault Bioventix, having a superb track record of profit and divi growth in recent years. The shares are illiquid, so there can be large & rapid moves in share price.
Zytronic (LON:ZYT)
Share price: 386.5p (up 1.7% today)
No. shares: 15.4m
Market cap: £59.5m
(at the time of writing, I hold a long position in this share)
Trading update - for the year ended 30 Sep 2016.
Underlying trading looks good;
Reported profit before tax for the full year will reflect the impact of a c. £0.9m non-cash provision arising from the Group's foreign exchange policy; however, the Group's underlying profit (before this non-cash item) is expected to be significantly ahead of last year and at least in line with market expectations.
Zytronic is a UK producer of bespoke touch screens. It exports practically all of its production, so should be a big beneficiary of the recent plunge in sterling. However, in the short term it looks as if the company's currency hedges have backfired. Still, that's what happens with currency hedging - sometimes it's profitable, sometimes costly.
Looking through the 2015 Annual Report, it says this about foreign currency hedging arrangements;
Risks associated with currency movements: A large proportion of the Group’s sales are denominated in US Dollars and Euros, so the Group is subject to risks associated with currency movements. It is the Group’s policy to manage these risks and provide a degree of certainty for cashflows into the UK without taking the risks of speculative positions.
Natural hedging is adopted to manage currency risk, whereby goods and services are sourced from Europe and the USA and the liability arises in the respective currencies. Surplus currency is then protected through the use of forward foreign exchange contracts for a period of twelve to 18 months ahead. This ensures the business knows its position around FX in the current year.
If my understanding is correct, it sounds as if the company must have forward sold its net dollar & Euro receipts, into sterling at less favourable rates than would now be the case.
This is just a transitory factor. Obviously it would have been much better if the company had not entered into hedging arrangements - indeed as Bioventix (above) showed, not using hedging has boosted its profits considerably. Whereas Zytronic took a more prudent view, but it has backfired this time. Such is life.
The important thing is that underlying trading at Zytronic is good, and is likely to continue to be strong, given that it now has the benefit of weak sterling making its products much more competitive in export markets.
My opinion - I remain positive about this share - it's good value, pays decent divis, and has a smashing balance sheet with plenty of net cash. Plus it should now be a big beneficiary from weak sterling. Plenty to like then. The £0.9m hit from currency hedging this year is by the by really, nothing to worry about - more bad luck than anything, that exchange rates happened to move against their hedges. They will more than recoup that cost from improved profits going forwards, as a UK exported.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

21 comments
Not really Herbie, a lot of people bought in on a tip and have banked profits. They are very illiquid, so a small flurry of sells can have a disproportionate effect. I will leave it another week or two to see if it drops a bit further before topping up (which I was about to do before that darned tip sent the price rocketing).
I wish Bioventix (LON:BVXP) had more disclosure on the revenue front. It is really difficult to get to grips with which diagnostic companies are using which antibodies and their contribution to growth. I would love to see revenue split by base products vs recently introduced (say last three years). Or maybe number of licensees for each of the non-exclusive products. Would also like to see more descriptive discussion of the sponsored projects and more generally on the commercial prospects and adoption for the newer products.
It's nice to see that Vitamin D still has legs given that it was introduced in CY12, became the largest contributor to revenue in CY14 and as at FY15 results had 16 licensees (which you would imagine covers a very substantial proportion of blood tests now).
Interesting to see that androstenedione is now generating "material" revenues given that it was listed as "entered development" in the June piworld presentation. I spent a fair amount of time interrogating the FDA database and the only thing I could find was a Siemens new device 510(k) for calibration verification material for androstenedione (and Troponin I) (https://www.accessdata.fda.gov/cdrh_docs/reviews/K143636.pdf - Feb 2015). Maybe someone who knows a bit more about FDA approvals can comment on what, if anything, this implies.
It also looks like Siemens is using a sheep monoclonal antibody for Testosterone on the Dimension Vista system (https://www.accessdata.fda.gov/cdrh_docs/reviews/K151529.pdf - Feb 2016) and the Advia Centaur system (K151896 - Jun 2016).
Does anyone know if Europe has a similar database of device approvals to the FDA one?
The special dividend is interesting. It further reinforces the income potential. I wonder if £5m represents a sufficient cash buffer above which excess cash will be returned to shareholders? Greggs (LON:GRG) last year pledged to return cash above £40m subject to a de minimis of £20m (20p/share).
Re Zytronic -my read is that the company takes out rolling forward cover on anticipated receivables. Clearly short term it has somewhat backfired as no one would have foreseen the steep plunge in sterling v the $ and Euro. Alot of these contracts are on a three month expiry basis so will run out and can be renewed at better rates. The Report and Accounts might give more detail. Another big gainer I came across recently is SUN which makes medical instruments in the UK and mostly exports them -alot to the USA. The margin gain to an exporter from a weak £ is very nice and represents a tangible cash benefit. Gains from translating overseas profits into sterling are also nice -but that's really more about the arithmetic expression of one figure (say US $profits) into another (£) at different rates.
The fact that Bioventix have just recruited two new research members must be a sign of confidence. In my view it is extremely unlikely that the Siemens deal will not go through. Happy long term holder.
Hello Paul
Thank you for the Bioventix report. I am a happy holder after a first introduction to the from Leon Boros. Do you have any thoughts on Tristel (TSTL). Their annual results are out today? Adjusted results look very good, reported results after share based payments less so. I'm at work today so haven't had a chance to dig any deeper. You reported on TSTL a few months ago. Except for this they look like a good, profitable company with additional potential if they can get approval to sell in the USA.
Thanks
Julian,
I hope you get a chance to report your deeper dig. I thought that IF Tristel (LON:TSTL) had made a market for disinfection of endoscopes, from within rather than wipe down of sealed ones (like nasenscopes) this would be worth a fortune but even with such an endorsement they did not and gave up their struggle in NHS (Look at Deltex Medical (LON:DEMG) ) But not only have they spread globally but also into four legs not just two. I cannot do forensics but though div is only just over 1% this has been nearly 4% for last two years with the special dividend, add in significant profits in $US and a few more currencies. There are major pressures for means to kill bugs in animals with anything, but preferably not antibiotics. tbh as a patient (and retired surgeon) I do not give a dam if a bug becomes resistant to Chlorine Dioxide as a result of farm use because the drug would also kill me so resistance does not affect me in anything like same way as resistant to farm antibiotics. Hey PAUL..... this is company on AIM paying dividends, and a bit, with no debt so what have I missed?
Seadoc, holder from Valentines day 2012 and up, if I may include the dividends, just 342%
Penny Share Letter. Also worth pointing out that Peter Harrison & team are not greedy, unlike say VLK.....
10 days ago these shares had a huge spike (up to today's levels). Wonder why that happened... - all thoroughly depressing.
I think that was because of a share tip.
According to John Rosier (JIC) it was The Penny Share Letter that tipped it. I have not read the article.
I have held since 13/10/15 and bought at various levels in the following year because the company, the management and outside investors (Lord, Boros, Gervais Williams at Miton Group. - the latter owns 13%).
There is still plenty of upside. The CEO (and 8% owner) talks about plans though 2030. This is one to hold and keep buying on dips in my opinion. So not that depressing!
No wonder Bioventix (LON:BVXP) is one of Keith Ashworth-Lord's favourite shares, it's one of mine too. It is indeed small and illiquid, but the business franchise and shape are absolutely superb. Just as importantly, Peter Harrison and his (very) small team appear grounded and sensible, so I don't see the temptations of empire-building being a significant risk. I'm a happy holder
Does Ashworth - Lord have a holding? I was aware that Gervais Williams at Miton had 13% of the company.
Yes, through the Sanford Deland Buffettology fund. It was one of KA-L's write ups that first put me on to Bioventix (LON:BVXP) I used to follow him (and Jeremy Upton) in the much-missed Analyst newsletter.
Thank you and very interesting.
Is there a reason it does not show at
http://tools.morningstar.co.uk/uk/stockreport/default.aspx?tab=5&vw=own&SecurityToken=0P00012UAP]3]0]E0WWE$$ALL&Id=0P00012UAP&ClientFund=0&CurrencyId=GBP
or is the holding still below 3% of Bioventix (LON:BVXP).
They hold 4% of their fund (£45m) in Bioventix (LON:BVXP) which is £1.8m, which is only 2.41% of shares in Bioventix (LON:BVXP).
Surprising how quickly these shares have dropped back.
Thank you.
Bioventix (LON:BVXP) is Ashworth-Lord's third largest holding at 4.36% of his Buffetology fund.
Yes good results from Bioventix (LON:BVXP), I see the shares are only up 0.5% now, there were 1600p earlier, I did top sliced some at 1564p, very illiquid stock mind with wide spread.
Paul
Any comments on CAR from friday?
In haste Paul. Bioventix (LON:BVXP). From what I have read BVXP get paid their royalties cheques twice a year from very large (likes of Siemens) solvent companies. So on that basis one would expect the AR's to somewhere around half turnover.
May have go that wrong but I think this was mentioned in this mornings RNS.
I hold.
KR
Michael
Hi Michael,
You've jumped the gun there! I updated the article to include the company's comments about receiving its royalties 2 months after period ends, so it looks fine.
Regards, Paul.