Small Cap Value Report (17 Sep 2014) - EGS, IND, SAL

Good morning!
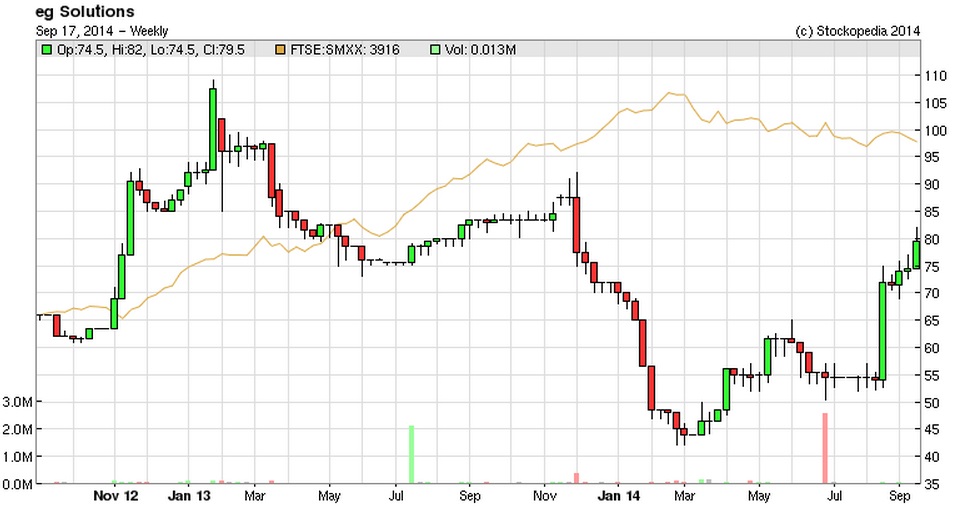
eg Solutions (LON:EGS)
Share price: 82p
No. shares: 16.5m
Market Cap: £13.5m
This is a small software company which sells back office optimisation software to large companies (e.g. insurance & energy companies). They had a stand at the Stock Market Show last Saturday, so I dropped by and had a chat with a Director about the company, and learned a bit more about what they do. I bought a little stock for my pension not that long ago after an intriguing contract win announcement - I like small companies which report large contract wins with large customers - that tends to be good evidence of the company having a valuable product which might continue to sell well elsewhere.
So even though the historic performance of EGS has been poor, I was satisfied from talking to the Director that there were known reasons for previous poor performance, and that the company was now getting onto the right track. Because of the lack of liquidity with these shares (very small market cap, and shares are tightly held) I would only ever have a small position in this company - it's important to be able to exit if something goes wrong, and that can only be done with a small position usually.
Interim results for the six months ended 31 Jul 2014 are published today. As you can see from the headline figures copied below, the numbers look good:
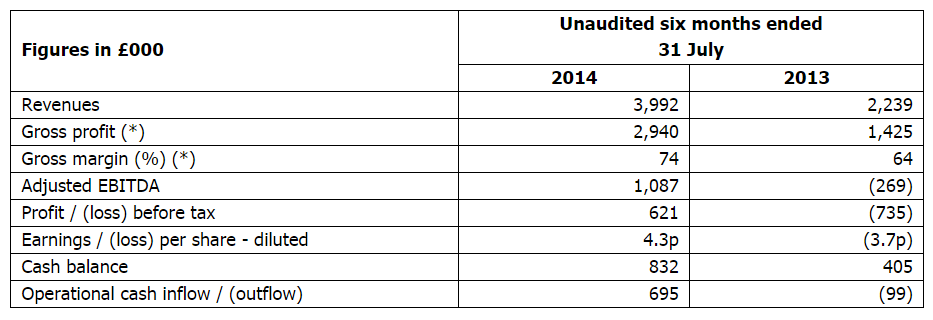
Although note that the company had already indicated that turnover would be around £4m, and profit above £600k, in its trading update of 20 Aug 2014, which I reported on here.
Outlook - today the company says;
The Company has made a strong start to the financial year, with significant growth in revenue, profits and cash generation. We are making demonstrable progress in the global workforce optimisation market, with multiple new and existing client wins during the first half. This improvement has been achieved with measured enhancements in our operating infrastructure. The Company has a substantial market opportunity and the leading software product. We will continue to invest to ensure we achieve the true growth potential of the Company and remain confident of delivering our full year financial performance in line with expectations.
Note that an H1-weighted year is expected, with the full year forecast only seems to be £0.3m, suggesting a loss for H2. That doesn't look right to me, and I vaguely remember seeing a forecast a few weeks ago suggesting just under £1m profit for the full year, so something like £300-400k for H2.
There were some large one-off contract wins in H1, hence we probably shouldn't get too excited about the H1 profit, or extrapolate it out.
Balance Sheet - is rather weak, with net tangible assets of negative £200k. Working capital is a tad on the weak side, with current assets being 100% of current liabilities, which is a little lower than I would like (over 120% is my usual minimum). So I wouldn't be surprised if the company does a Placing to strengthen the Bal Sheet at some point. That could be why the company is keen to talk to private investors, to get the share price up before a Placing? Maybe I'm being cynical there, but it is the usual pattern that we see time & again with smaller companies.
My opinion - an interesting little company, which seems to be trading well at the moment, so let's see how it pans out. It obviously has to be seen as high risk, being small, and with a poor historic track record.
Indigovision (LON:IND)
Share price: 480p
No. shares: 7.6m
Market Cap: £36.5m
I read the results this morning, and then went back to bed, as all was well.
Results published today are for the twelve months to 31 Jul 2014. This was the old year end date, but this year the company has changed its year end date to the more normal 31 Dec, so there is a one-off 17-month period this time, hence today we have a second set of interim results, before finals for the 17 months ending 31 Dec 2014 will be published probably in Feb 2015.
It's a completely common sense move, which was announced a long time ago, in advance, so there is nothing untowards going on - i.e. a change of year end, if announced very late, is usually done to cover up poor results. That's not the case here though.
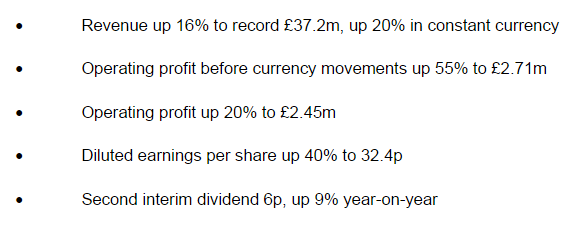
The financial highlights speak for themself, and look impressive in my opinion;
Currency - I am pleased to read that the company intends to change its reporting currency to US dollars, since it invoices customers mainly in dollars, and purchases its equipment (from outsourced manufacturers) from the Far East, hence are invoiced by them in US dollars, as is the norm. So it makes obvious sense to report in dollars for the company overall, which will stop the yoyo effect of currency tranlation. It also pre-empts any issues from possible future Scottish independence, which I rather like.
R&D - Note that the £2.4m operating profit is stated after fully expensing £3.4m of R&D, which is the right way to do things, not capitalising such spending, as many companies do. I am a firm believer in the value of R&D spending, and it's good to see IND spending 9.3% of turnover on R&D, as that spending today creates the competitive advantages (and hence profits) of tomorrow.
Valuation - with diluted EPS reported at 32.4p, and the shares currently at 480p, the PER is 14.8 - not a particularly demanding valuation given that underlying (i.e. constant currency) profit has just risen by 20%. So that's a PEG of 0.74 (where anything under 1 is usually seen as good value).
PEG only works if growth rates can be maintained of course! So let's dig out the forward-looking comments from today's announcement.
Outlook - this sounds positive;
The last twelve months has seen good growth throughout the business, record sales, and a strong operating performance. More importantly, IndigoVision's position as a key industry innovator has been enhanced through rapid development of our product range, and internal and customer confidence is high. Current trading is strong and we expect to report good results for the seventeen months to our new 31 December year end.
IndigoVision has delivered strong growth throughout the business in the twelve months to 31 July 2014. The final five months have started well and we expect to report good performance for the seventeen month period to our new financial year end.
Perhaps more importantly, the medium and long term outlook for the markets in which we operate continues to be favourable. Although there is effective competition, IndigoVision is well placed relative to its peers as far as product range and performance, reputation, innovation, global sales coverage, and distribution network are concerned.
It therefore seems likely that the excellent progress in the last twelve months has been the beginning of a more sustained period of growth and we look forward to the future with a sense of confidence.
I particularly like the sentence about this being the beginning of a more sustained period of growth, which reassures that this is not another false dawn, of which there have been several in recent years.
Balance Sheet - this is strong, with current assets being 251% of current liabilities, which warms my cockles.
Dividends - the company has a history of generous dividend payments, including a special dividend of 70p a few years ago, which I suspect was to deter predators who were circling at the time, from using the company's own cash to part-fund a takeover bid!
A 6p divi was paid in Apr 2014, and another 6p has been declared today, payable on 16 Oct 2014, with the ex-divi date being 26 Sep 2014.
My opinion - I meet the CEO & FD every six months, and have been tremendously impressed with the methodical, structured plan to turn the company around. So much has been going on behind the scenes to improve every aspect of the business, and we were always told that year 3 of the turnaround plan would be when things would come together, with growth resuming - and that's exactly what has happened now that we are in year 3. Therefore I remain an enthusiastic holder of these shares. Hopefully there will be more upside to come?
Spaceandpeople (LON:SAL)
Share price: 44p
No. shares: 19.5m
Market Cap: £8.6m
A couple of readers have asked for feedback from my meeting with SAL management yesterday, so here goes.
I should preface this by saying that I am supportive of management, but my sanguine view was not shared by another person in the meeting who I had a post mortem with at the pub, so there is a chance that confirmation bias might be creeping in with me? I'm trying to be objective, but fully accept that maybe I'm looking for positives?
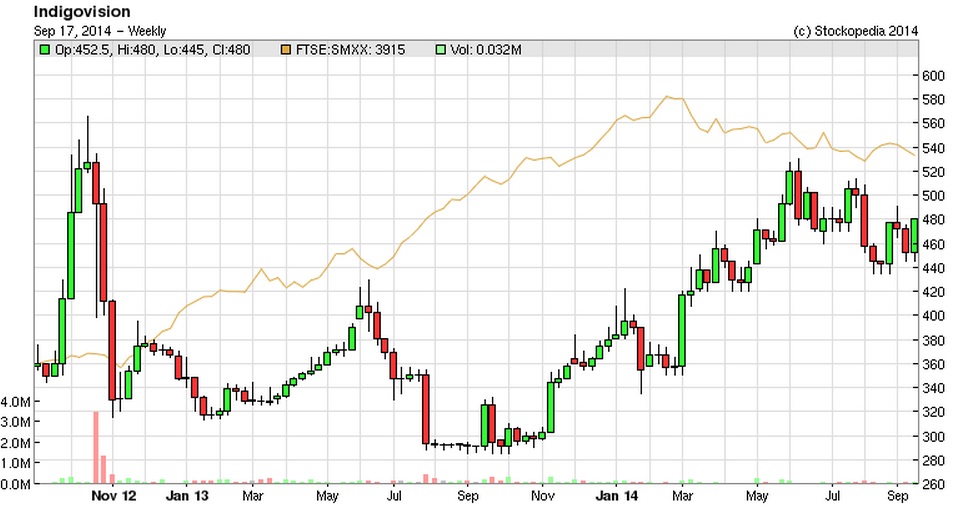
The shares had been peaking around 150p in the spring of this year, after good 2013 results, and an excellent multi-year track record of growing profits & dividends. The shares have since dropped by more than two thirds, after two profit warnings. To refresh your memory, here are links to my reports on the profit warnings this year;
Profit warning of 17 April 2014
The meeting I attended yesterday started with the company giving a presentation, the main thrust of which was to explain what had gone wrong this year, and what they are doing to fix it - which is exactly what I wanted to hear.
What has gone wrong?
The company said that performance up to July had been in line with the revised forecast for this year, but that problems began to emerge in August, and worsened in Sept. So the company firmly refuted any suggestion that they had been slow in informing the market about deteriorating performance. I'm prepared to take that at face value, and one person in particular in the meeting grilled the company very hard on this point.
The specific problems causing the second profit warning in Sep 2014 were;
- German retail - some empty kiosks, combined with minimum rental payments due to landlords has hit the bottom line.
- S&P+ (the subsidiary which does experiential, i.e. face-to-face marketing campaigns) had a big contract deferred until the Spring of 2015.
So what are they doing to fix things?
- Negotiations are underway with German landlords to amend contract terms, which the company believes is in their mutual interests, so they are hopeful of success here.
- New business initiatives - including a new kiosk design which can be used by multiple vendors, hired out on a weekly basis, at much higher margins.
- The company has a much sharper focus on higher margin business now, and is not renewing contracts which generate turnover but little profit (hence the drop in UK business recently).
- Win new venues - contract negotiations are underway, but are more protracted than in the past, because SAL has tightened up its contract terms, and Malls are pushing back against this.
- Reduce overheads - £700k p.a. cost-cuts have already been implemented, which is a very material sum.
Budgeting process
Myself and others have been critical of the company's overly optimistic budgeting process. In particular lowered forecasts were issued to the market in April 2014, which also turned out to be too optimistic. The company accepted these criticisms, and made it clear they have now taken a much more conservative approach to forecasting, so the revised forecast of £ 800-1000k profit for 2014 is a figure they are happy to hang their hats on.
2015 forecasts have been prepared on the basis that new business will come in 6 months later than hoped for, and heavily risk weighting new business (i.e. putting things in at e.g. 25% probability of success). A couple of quotes - "we've stopped looking at the future through rose-tinted glasses", and "We're preparing budgets with a much more jaundiced eye". I think they accept the criticism that it should have been like this to start with, but as the CEO pointed out, the company has had disappointments before, but has always managed to recoup lost business elsewhere - but that hasn't happened in 2014.
Is the business model broken?
We discussed this at some length, and having run through some numbers (I didn't realise the rents on kiosks are so high!) it's clear to me that the revenue made by shopping centres from kiosks is far too important for them to forego for aesthetic reasons. So my concerns that kiosks might be on the wane, look misplaced. Although SAL do need to focus more on providing quality offerings to Malls.
SAL completely dominate this niche, with hardly any competition. The main competition is Malls taking the management of kiosks in house. Contracts are being amended so that Malls cannot simply poach SAL vendors, and put them into a permanent unit, without properly compensating SAL.
Management emphasised that they are winning new business, e.g. a large new mall in Birmingham.
I wondered if SAL might be a business that is counter-cyclical - i.e. doing well in Recessions, when Malls are desperate for revenue, but less relevant in more buoyant economic times? Management firmly refuted this suggestion, and stressed the capital value added to a Mall from the increased rents from kiosks. So the only issue is that some Malls will from time to time take the kiosk management in-house. That has always been the case, and those clients usually come back to SAL after a couple of years managing it themselves, and finding that they are not as adept as SAL at maximising the revenue from kiosks.
I asked if management have been fire-fighting this year? They replied yes. So the strategy is now to improve margins, and get the business back on track.
"We're the biggest & best at what we do in Britain & Germany".
"All the problems this year have either happened at the last minute, or have come from left-field".
New non-Executive Directors
The Chairman has bowed out due to being too busy to focus on SAL, and having been there 8 years felt his time was up. A heavyweight new Chairman is hopefully lined up for appointment in Oct 2014.
The company has also had a refresh of the Non-Execs, and the CEO spoke highly of the two new Non-Execs, Steve Curtis, and George Watt (currently the CFO of STV Group) who both have highly relevant experience & contacts. It is also an endorsement of SAL that high calibre people want to join.
Rebuilding trust
Management are open about this being a disastrous year, and they seem to accept that, and have learned from it. The CEO said, "I know we have to deliver this year's (revised) figures". It was pleasing to hear the CEO emphasise how he feels personally responsible to shareholders, and is gutted that things have gone badly this year. OK it's only words, but he meant it I think.
My opinion
With the market cap now only £8.6m, I feel that the market has thrown the baby out with the bathwater. The company is still profitable, and should deliver £ 800-1000k profit this year. It's not under any cash pressure, and will still pay a (reduced) dividend of 2p in the spring of 2015.
That said, after 2 profit warnings, you can understand the market now being very sceptical, and not being prepared to believe the revised forecasts. The latest forecasts (much more conservatively prepared) for 2015 are for a £1.5m profit (base case), with an upside case of £1.85m. This is a much better way to steer the market, and I'd be very surprised if they are not able to achieve those figures.
Therefore, if I'm right about next year's forecasts being achievable (which they should be just on the basis of the cost-cutting already done), then these shares should be at least 50% higher this time next year, maybe more?
So personally I am prepared to back management here, and let them get on with turning the business around, whilst acknowledging that this year has been extremely disappointing.
Got to dash now. See you tomorrow!
Regards, Paul.
(of the companies mentioned today, Paul has long positions in EGS, IND & SAL.
A fund management company which Paul assists with research ideas, also has long positions in IND and SAL)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

18 comments
Hi Paul,
I know you are a fan of SpaceandPeople (SAL). We have just published a main write up on this stock - I wonder what you think about our fundamental case:
Based on our fair value estimate the stock offers a big fat juicy 82% upside from the current share price.
Our estimate is based on a DCF fair value estimate of GBP 16.5m versus the current market cap of GBP 9m. Following are our key subjective assumptions:
- full recovery in operating cash flows in 2016 to the average levels seen between 2011 and 2013
- zero growth after 2016
- maintenance capex at current depreciation levels in line with the zero growth assumption
- 10% discount rate (WACC)
full details can be found here: wp.me/p57Kw2-K
let me know what you think, appreciate your comments as our treasured UK Small Cap specialist :)
Best,
Michael
when you say they will be toast ... what would actually happen to them .... nothing! management rarely ever get booted out n matter how bad they are, one might be a sacrificial lamb, but on the whole the smart talking ones will get away with outright failure and theres not much anyone can do about it
Paul,
Thank you for your write up on SAL. As I read it there is still plenty to do in reorganising the business to cover the holes that we have seen this year. It is possible that we may see another profit warning or disappointing numbers low end of expectations. I agree these should be turning now but sentiment being what it is and given the size of the business I can see these shares drift lower until some concrete evidence is received by the market that they are not seriously holed. Maybe the arrival of the new hires will be the beginning of that process.
Hi Camtab,
Management at SAL know that they'll be toast if they issue another profit warning.
So it's very much a case of "we've GOT to achieve these numbers".
That said, I can fully understand the market not yet giving them the benefit of the doubt, hence the current very low valuation. The company has to earn back investor trust, which they know.
Regards, Paul.
Paul thanks for your excellent write-up of the SAL meeting.
As this is easily the worst performing share that I've ever had (I usually sell out long before and should have done so here) I'm very interested to see how the Management can turn this business around. I think the fundamentals really stack up and it represents a bargain for the brave and patient. Whether I will be increasing my exposure at these cheap prices is a decision I have yet to make.
Pity you feel like that, Paul, I've noticed very little anti-English sentiment and the level of debate has been several notches above the usual rubbish.
You'll be welcome in Scotland but you can obviously choose to stay in England with the ever more popular UKIP welcoming all-comers with open arms!
Thanks for the Space and People update. One thing that doesn't make sense thoughy
"The company has a much sharper focus on higher margin business now, and is not renewing contracts which generate turnover but little profit (hence the drop in UK business recently)" - the UK was the higher margin business, the international expansion was the lower margin business.
The original profit warning saw a drop in profits, but not in revenue, because they were losing UK business. I think we are not getting the whole story!
I want to mention Cenkos Securities resutls this morning which were a cracker. Rev +226% and PBT up 653% - plus plans afoot to return cash to shareholders.
Hi Shaun,
I saw them and have topped up by a further 30 odd%
I think Cenkos Securities (LON:CNKS) will continue to do well over the next 12-18 months.
Best,
Sully.
Paul - really appreciate your write-up of the meeting with Spaceandpeople (LON:SAL) yesterday, thanks!
Was any mention made in the meeting about the potential effects of Scottish independence in the event of a Yes vote? (Sorry to raise that thorny issue!) I know that the majority of their business is in rUK but surely there's a danger that they'll be affected by lowering business confidence and the problematic currency issues...
I was a bit scared venturing over to read Pauls tweet in relation to SAL but nothing untoward thankfully.
Im pretty new to SAL and am trying to do a bit of bottom fishing on the basis that the wheels can go back on the truck - lets hope this is the case.
Apologies for going OT (i dont do twitter) but i think its unfair (IMHO) to criticise the Scots for asking and being granted an independence vote by the powers that be, the powers that be when they sanctioned the vote should have at the same time come up with a sensible roadmap as to how the main things currency/debt etc would progress without descending into outright chaos (as seems to be the case) . Nearly all polls (and bookies have confirmed that the odds back this up) have show the majority against independence - but the majority would agree that having the vote is the right thing - the added bonus of a no vote is that it puts the issue to bed for the forseable future (10 years plus lets hope?) job done. I don't particularly like the attitude of the outsiders complaining about issues that have only minor relevance to the issue when its a very good sow of democracy in action - something UK/England should be proud of. Having said all that as an exciled Scot i don't really qualify as being worthy of having an opinion officially speaking :)
Hi rmillaree,
The point I was making on Twitter last night, is that I think Scots will discover that they have done enormous damage to their relationship with the English, and that I think this will cost them dear in reduced tourism, etc.
As an Englishman, I've had to endure a couple of years now of anti-English rhetoric from Scots on the TV, and to be honest I'm sick of it. This is bound to have an impact, even if subconsciously with a lot of English people. I was talking to some Irish people about this a long time ago, and they said that there had been a realisation in Eire that they had to drop the anti-English stuff, as it was more important to be welcoming & friendly in order to get the tourists' pounds. Scotland is going to learn this lesson the hard way too in my opinion. If you make your immediate & much larger neighbour feel unwelcome, then it's going to be a serious self-inflicted injury. Anyway, that's just my view.
I understand the desire for self-Govt, but it's unleashed a particularly strident & ugly type of aggressive Nationalism in my view.
Regards, Paul.
Paul, I'm intrigued to know how many different shares you hold, as a small position in eg Solutions (LON:EGS) would appear to have to be little more than £1k (NMS 1,000 at 79p) to give you the freedom to exit quickly if trouble occurs.
Hi FREng,
From memory I've got 6,000 shares in eg Solutions (LON:EGS) in my pension.
I wouldn't want any more, as the lack of liquidity then becomes a problem. It should be possible to dispose of that sort of quantity reasonably easily, although if trying to sell on bad news, then the price would probably take a nasty hit & the MM might want to bid me a couple more pence below the quoted price?
Hopefully the company will do well though. If the newsflow remains positive, then I'll hold the shares for a few years probably.
Regards, Paul.
Re eg Solutions (LON:EGS) this company seems to be run for the benefit of the CEO as her pay is astronomical for such a small company!
Re. eg Solutuons. The CEO Elisabeth Gooch is the founder and she currently owns 32% of the company. Presumably the eg in the company's name stands for her initials. Shades of the Mike Ashley syndrome.
Hi Paul
I am probably jumping the gun here, and I saw your tweet, but do you have anything else to say regarding your meeting with Spaceandpeople (LON:SAL) managment? All help gratefully recieved.
Hi Paul, would be very interested in what you found out about Spaceandpeople (LON:SAL) yesterday when you met with them. Really appreciate your professional and thoughtful reports, thanks!