Small Cap Value Report (18 Apr 2016) - SPRP, TPOP, IGR, LAKE

Good morning!
I'm back from a long weekend in Warsaw - it was really good to have a change of scene. All was great, apart from being ripped off by an illegal taxi driver, and a stag party on the plane back who made the flight a misery. The airlines really do need to do something about this increasing problem.
Mello Beckenham
A reminder that David Stredder's popular, and long-running monthly investor evening is happening today - click the blue link above for more details. The popular & very capable David Cicurel of Judges Scientific (LON:JDG) will be updating investors on progress this evening.
I probably won't be able to make it tonight, as I'm working in North London this afternoon, helping a private company. I'm taking on some NED roles in smaller, private companies with good growth potential, to help them with finances, and strategy/planning. All good fun, and it's enjoyable to do something a bit more hands on.
Sprue Aegis (LON:SPRP)
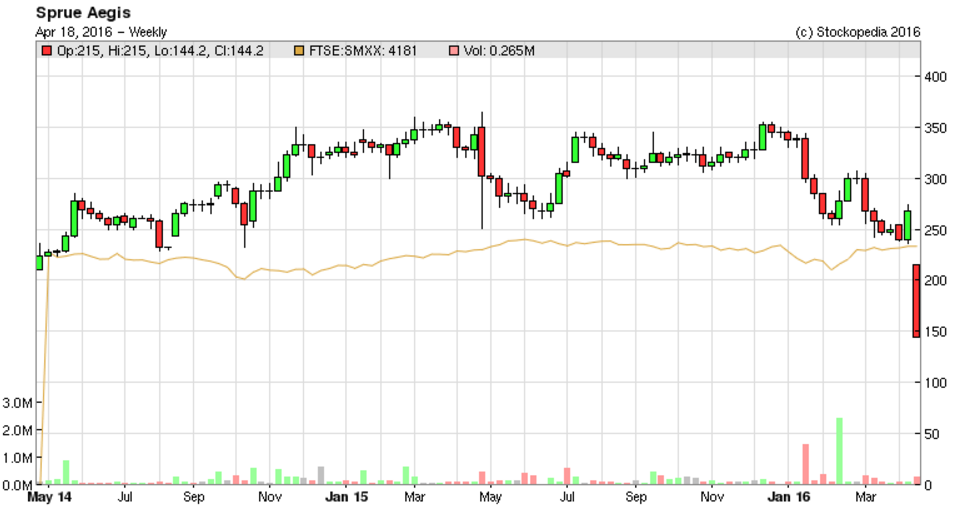
Share price: 142p (down 47% today)
No. shares: 45.9m
Market cap: £65.2m
Profit warning - you know straight away, when a share price is down 47%, that the profit warning is a bad one. Also, there has been no bounce in the share price yet, Such an initial bounce often happens for 2 reasons;
1) The early drop can be exaggerated by forced sellers at spread bet companies - whose positions are cut at any price, once the stop loss is triggered. It's important to remember that there can often be considerable "slippage" with stop losses - i.e. your spread bet can end up being closed at a far lower price than the stop loss you set. A stop loss is only a genuine stop loss if it's guaranteed, and you have to pay extra for that. Any share that gaps down at the open can make a mockery of a (say) 10-20% stop loss. The actual loss can be considerably more.
2) Existing holders are often anchored to the previous share price, and wrongly see the reduced price as a buying opportunity. This is down to psychological factors, and often an underlying desire to support the share price. This is due to the increasing pain of the losses on their existing shareholdings. It's nearly always a mistake to steam in and increase your existing holding on a profit warning - unless the profit warning is mild, and due to one-off, and easily fixed problems. Or, if the share price has wildly over-reacted, and fallen far more than it should have done.
In the case of SPRP, the company has a strong balance sheet, with net cash, so the 47% share price fall is really even worse than that, on an Enterprise Value basis. So things must be bad, and they are bad I'm afraid.
2015 results - warranty increase - a problem has emerged with batteries supplied by a third party:
...the Company has recently identified an issue in certain batteries supplied by a third party supplier that may cause a premature low battery warning chirp in certain of its smoke alarm models sold in the UK and in Continental Europe.
The Board is keen to stress that this is not a safety critical issue.
I don't really understand this problem. Surely the customer would just replace the battery, if it gives a warning chirp? Perhaps it's not as simple as that? Maybe it's a built-in rechargeable battery? I think the company could have explained this better, so that non-technical people like me could understand the issue properly.
EDIT: In the comments section below Biloseli reckons that this might relate to a "sealed for life" product, which is supposed to have a 10-year battery inside, which it now appears could fail after 3 years.
The financial upshot of this is quite considerable:
As a result, to support the Company's customer service obligations, the Board proposes to increase the Group's warranty provision as at 31 December 2015 by £5.5m to £6.8m (2014: £0.9m). Consequently, further to the Company's trading update released on 20 January 2016, the Board now expects the Company's operating profit* for the year ended 31 December 2015 to be approximately £7.3m compared to the previously announced expected operating profit* of £12.1m.
Well done to the company and its advisers for quantifying the impact, so that shareholders & commentators have accurate information to work on. All companies should do this, rather than the more usual vague wording without numbers.
One hopes that the company can sue its supplier, to recover some or all of these losses. This is not mentioned in the RNS. There is also reputational damage to think of - customers affected by this warranty issue might buy competitor products in future perhaps?
In itself though, the above is clearly not anywhere near enough to have triggered a 47% share price fall. There is also a warning for the current year, which looks a lot more serious.
2016 profit warning - this looks pretty dreadful:
Challenging trading conditions in France, principally due to overstocking, and weaker sales in Germany, due to product certification delays, are likely to significantly adversely impact the Group's expected results for this year. Consequently, the Board has revised its guidance for the full year 2016. Subject to no major changes in exchange rates, the Board now expects a first half operating loss* of approximately £1.9m (which includes a restructuring charge of £0.2m as a result of reducing certain fixed overheads), and an operating profit* in the second half of approximately £3.8m with sales and operating profit* in the full year of approximately £55.0m and £1.9m respectively. The estimated saving in 2017 from the fixed cost reduction is approximately £0.8m.
So loss-making in H1, and only a £1.9m profit anticipated for the full year. That's a long way below previous guidance of £8.3m given just over a month ago. Although as above, hats off to the company for giving profit guidance to the market - if some companies can give profit guidance to the market, why can't all companies?
Outlook - the company hopes to get things back on track by 2017:
We expect to rebuild trading momentum in the second half of 2016 with certified new products and enter 2017 with normal levels of trading.
Whilst regrettable, the overhead reductions will put the Group onto a lower cost base saving an estimated £0.8m in 2017 and keep the Group on the right course to deliver our longer term strategic objectives as set out last year by Neil Smith, the Group CEO.
Cash position - the company reports today that it had net cash of £22.4m at 31 Dec 2015, so that protects the downside risk - there's no danger of it going bust. Also the 2015 dividend is still going to be paid, but it doesn't say what amount.
My opinion - the product warranty issue is a nuisance, and probably deserves a say 10% fall in share price. The real damage though is the collapse in 2016 forecast profits. This really casts into doubt the whole business model of this company.
It looks as if the bumper profits of 2014-2015 were a bit of a one-off. We already knew that bumper sales in France were caused by a law requiring the fitting of smoke alarms. However, bulls in the stock hoped that new products would take up the slack. Clearly that has not happened.
The shares are supported by the cash pile, but I think for the time being the bull case has really gone out of the window. It's difficult to know what level of sustainable profits the company can generate, which is key to valuing the shares.
So for now, I can only really put a question mark next to valuation. As the shares are illiquid, then who knows where the share price might settle? I'm inclined to sit on the sidelines for a few weeks/months, and see what happens. That also gives time to watch the RNS to see what "holding in company" statements are issued - giving an idea what the big institutional holders are doing. Ideally, I look for the big holders to buy, in support of the company & share price. If they are selling, then I think it's usually best to wait until they've finished selling, before considering a purchase.
Bad luck to holders here - I know quite a few friends hold this stock.
People's Operator (LON:TPOP)
Share price: 30p (down 14.3% today)
Share price: 77.1m
Market cap: £23.1m
2015 results - these numbers are a joke, and the least time spent on it, the better.
The company is generating a gross loss - i.e. it's selling telephony services at a lower price than it has to pay to provide the service. That's just plain bonkers.
Sure there's plenty of top line growth (from a low base) - I'm sure customers are happy to use services that are provided at below cost price.
The company managed to generate a £10.4m operating loss, on £2.1m turnover.
There's only £8m cash left, so the begging bowl is likely to be out fairly soon, for more cash. I'm not sure whether investors will be quite so wowed by Jimmy Wales' name, after seeing such diabolical trading figures.
The company says it has very low cost customer acquisition. So the big question is this - where's all the money going then? There must be a large central overhead.
My opinion - after a few bad experiences, I try to avoid blue sky, heavily loss-making companies like the plague. They nearly all go wrong - taking far longer, and costing far more than originally planned. Early shareholders are the mugs who get diluted down to nothing, when the discounted placings are done later to keep things going.
Why take the risk, when hardly any companies like this actually deliver what they say they're going to deliver?
I put this share on the Bargepole List less than 4 months ago, and it's already down about 64%. The thing is, you can spot things like this a mile off. So I continue to be amazed that brokers can find institutional punters who are prepared to chuck other peoples' money into such questionable & unproven business models.
I hope TPOP works, because it supports charities. However, to date it's shareholders who have provided the charity.
From what I've observed, you have to be so careful with loss-making tech companies. There is a Silicon Valley mentality in a lot of them - where management and staff are convinced of their collective genius. Losses and cash burn are regarded as of negligible importance. The assumption is that each round of funding will be easy to secure, and at incrementally higher share prices.
In a bull market, shareholders can become caught up in this madness, and end up hugely over-paying for companies which don't have any commercial viability. However, the bubble has already burst for some such companies. Shareholders now want to see real progress, and a road map towards profitability. This is a rude awakening for some smaller tech companies, which are forced to slash costs, and race for breakeven (as has happened with Synety (LON:SNTY) for example).
So for TPOP, I think they may well find that the mood for another fundraising is very different to when they floated. So I imagine a deeply discounted placing is probably on the cards. However, the growth might be enough to excite investors - as we saw recently with Koovs (LON:KOOV) - an apparent basket case, but generating enough growth to swing the pendulum of investor mindset from gloom to excitement again.
International Greetings (LON:IGR)
Share price: 175p (up 12.2%)
No. shares: 59.3m
Market cap: £103.8m
(at the time of writing, I hold a long position in this share)
Trading update - relating to the y/e 31 Mar 2016. This looks to be a business that is firing on all cylinders:
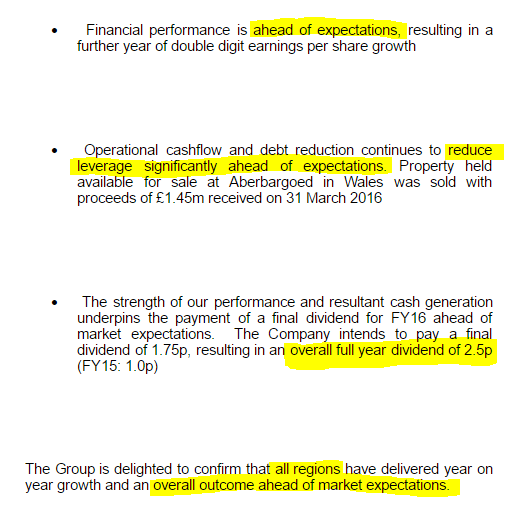
I like big increases in divis, as it demonstrates confidence, and a positive trajectory in what might initially be a modest dividend yield. However, increasing the divi by 150% means this could become a decent yielding share in the future.
My opinion - I've held this share for a while. Although there were some balance sheet issues, these are being sorted out well. Also, a series of upbeat trading statements, gives the impression of a company that is really going places.
Gervais Williams of Miton Group was raving about this company and its management at an investor event last year. I'm a great believer that when good stockpickers meet management, and come away impressed, then it's worth including that ingredient in your overall investing hot pot.
The forecast PER is still reasonable, something like 12-13, after today's share price movement, and also allowing for forecasts to probably rise a bit. Given that the valuation appears reasonable, and the Directors sound confident, then I'm happy to continue holding.
Lakehouse (LON:LAKE)
(at the time of writing, I hold a long position in this share)
Many thanks to reader Imranawan, who flagged up in the comments section below, that the Board of Lakehouse seems to have have reached agreement with the EGM requisitionists (Slater Investments, and the founder Steve Rawlings) as to the future Board composition.
I'm very glad that agreement has been reached, as public mud-slinging between the parties can only damage the business.
Right, I have to dash now. See you tomorrow!
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

27 comments
There is a meeting arranged by ShareSoc with the Sprue management for this Wednesday. ShareSoc members only http://www.sharesoc.org/events.html
Results and the recent update will both be covered.
Two or three years ago my father had a free fire safety check at his home carried out by the local fire brigade, during which they supplied him with a free Sprue FireAngel ST-620 alarm that they fitted for him. A few weeks ago it started chirping from time to time (although it could be cancelled by poking the central test/reset button with a stick.) I phoned the fire brigade to let them know what had happened and they said they knew about the problem and would arrange to send him a replacement. An updated model ST-622 then arrived in the post directly from Sprue. I'm assuming it's an updated model with a better battery but we'll find out in two or three years if it starts chirping again.
Either way, it looks as though they've known about the problem for some time and that they must have supplied a lot of the original alarms under contract to local fire services.
The Amazon reviews of this alarm ST620 could hardly be worse.
One thing I never liked with SPRP was their weird supply chain.
If you don't control the whole process, then who knows what goes on.
It's not a company I want to revisit anyway.
P.
If you want to know more about sprue's problems, the easiest thing to do is to read Amazon customer reviews. This is what put me off buying the shares a few weeks back. There are many reports on there of battery failures in times far shorter than 10 years. Maybe people will just buy another (some people on Amazon said they bought another because it fitted on the same mount) but personally, if I invested in a piece of safety equipment that was outside the specification, I wouldn't buy another. As for claims and compensation, maybe individuals won't be bothered but some large organizations have bought in bulk. They might be more persistent and forceful. I suspect the biggest issue here is reputational ... and that's very hard to fix, however good the balence sheet.
Whitby,
That's a great point actually.
Many investors, including myself, get most of our info about all companies from their RNSs and the website. Yet this is one-sided info, and often wrong.
We should perhaps learn to ignore the lies that companies & their PRs tell us. Instead find out info ourselves. As in this case, people said that the news of failing batteries in SPRP products was commonplace. Smart people sold their shares when that news became widespread - easily checked from Amazon & other websites.
So perhaps we should put less emphasis on the RNS, and the lies that management tell us, and seek out more accurate information ourselves?
How much do I trust company management? Very little! Most are varying degrees of liars - from the extreme conmen at AIM resource stocks, to the next level up that twist & turn to schmooze you. At the top there is an elite of wonderful entrepreneurs, so don't get TOO sceptical..
PP.
PP.
Sprue not Spruce - my post above (must type with a lisp).
Everything you could possibly want to know about 10 year Lithium (and alkaline) batteries in Smoke Alarms. https://www.cpsc.gov//PageFiles/116967/LithiumFinal.pdf
From a 2002 U.S. CONSUMER PRODUCT SAFETY COMMISSION paper. - PRELIMINARY TEST RESULTS ON LITHIUM BATTERIES USED IN RESIDENTIAL SMOKE ALARMS
Clearly places the then findings squarely at the door of the battery manufacturer....
If Spruce had ever been able to produce Lithium batteries that functioned satisfactorily to give 10 years working life then all the world's lithium battery manufacturers would have been biting their nails down to the quick and getting their CV's off in the post long before now.
10 years working life out of any lithium battery, c'mon !?! Own up, who swallowed that one?
3 ot 4 years before 60% capacity gone, in the very best Lithium batteries - sounds about the ultimate you could expect.
I bought 2 of the SPRP sealed for life smoke detectors about 12 years ago. They were the type that plugged in between a lightbulb and the fitting thus providing a source of power to recharge the batteries. They also had a 10 year life. One of them gave up after about 3 or 4 years so I bought a replacement and that only lasted a year before it started chirping away every few seconds. It was in the middle of the night that I realised the sealed units aren't so great because you cant take the battery out of them to stop them chirping. End result was to put it in a bucket of water outside the house (even then it continue to chirp )- great fun at 3 in the morning.
Yep we had similar issues with the sealed for life units. I think they just got thrown away, I would imagine most consumers would do that.
Paul
A long time follower of your excellent work here
I have also seen you across the tables at mello
I lived in Warsaw 1992-94, illegal taxi? Seems like nothing has changed
Like you JDW72, I also bought more Sprue Aegis. The products are good and 3 years is not bad, I was always sceptical of 10years. Like you I don't think many customers will look for redress it is not a big enough purchase to warrant the trouble.
Given some time I believe Sprue Aegis will prove a good investment and we have just picked up more shares at a cracking price.
I use People's Operator (LON:TPOP) - it's bloomin' cheap. £11.99 a month for 6GB data, unlimited minutes and text. Thank you to the shareholders who are subsidising me ;) I see it has recently upped the price of this package to £14.99 a month for new subscribers, presumably for the reasons Paul sets out. That still makes it cheaper than any other provider I can see while maybe improving its bottom line a bit. It's a good investment if you want a SIM-only deal, maybe less so if you're trying to make a bit of profit out of the company.
On a brighter note Boohoo.Com (LON:BOO) seems to be having a good run of late.
The original plan for Lakehouse (LON:LAKE) was to replace all the NED's, so this RNS is a bit of a climb down for the requisitionists as only the Chairman is walking out the door. Of course it may be the plan from the beginning but we don't know. So perhaps the arguments have moved from the public forum to the boardroom or maybe a tacit agreement has been reached as to when the other NED's will leave to pursue other interests.... Either way the company should be in a better position going forward, I hope!
Seems like a virtually total win for Rawlings and Slater to me. Rawlings and the other two he put forward are going on to the Board. And taking the Chair and Senior Independent Director positions. In themselves the NEDs weren't the issue, it was adequate management and oversight.
It has been a while since Paul covered Boohoo.Com (LON:BOO) (assuming he will with the prelims next week).
I just wanted to say that every day I look at my portfolio, I see that it has gone up. I think I owe Paul a beer because by doing my research after reading his articles about it, he has made me a nice chunk of change!
Thanks Paul for the articles, I always read them with interest.
The boardroom issues at Lakehouse (LON:LAKE) also look to have been resolved according to an RNS issued this lunchtime: http://www.investegate.co.uk/lakehouse-plc--lake-/rns/intention-to-adjourn-general-meeting/201604181151075179V/
Hopefully the board can put the issues behind them on focus delivering some value for shareholders.
Hi Paul,
Sorry to hear about another stag party ruining a flight. Only way I've found to avoid this is to fly out on Thursday or come back on the Monday, it's normally cheaper too.
Indeed it's a shocking profit warning from Sprue Aegis. This is what they say about the battery issue:
The failure mode in the battery in affected smoke alarms has only recently become apparent and typically occurs after around three years from the date of battery manufacture. To prevent the issue happening in the future and to ensure all the Group's smoke products perform to the highest standards, the Group has introduced additional screening processes on the production line prior to the battery being fitted into finished smoke alarms and we are reviewing, and, if necessary, will enhance our internal operational controls and processes.
I am a technical person and to me this does not read clearly either, but one way of reading it is as an internal quality control issue in that they may have been fitting batteries that have been sitting on the shelf for too long prior to fitting during production - hence the need for "additional screening processes on the production line" to weed out these batteries. I can only think this is what they mean because it's impossible to test the battery life at that stage of the process.
However, they should have been performing accelerated life tests on these batteries as part of their overall component testing and quality control procedures. Clearly there is a problem with the battery but it has also highlighted a worrying hole in their quality control.
All the best, Si
Another theory is that the battery has a discharge curve (voltage * time, see examples) that is somewhat different than the original part their product was designed for, hence reaching the battery warning trigger voltage earlier, before it's really empty (the point is to identify the end-of life drop). If so it's a quality control/engineering issue, if a subtle one.
The warranty reserving seems pretty high, as Carcosa says you wouldn't expect most customers to actually claim, though they may buy from another supplier and/or some resellers might drop them because of even a few returns.
Sprue Aegis (LON:SPRP) Looking at their website it appears to affect only a small proportion of their product offering. It's a custom made lithium battery which is not replaceable; hence the ten year warranty. However this is not an expensive item to purchase and I would have thought that three years into buying it customers, when they have a problem, will just throw it away and replace it with another detector, possibly even the same supplier as before. I find it hard to believe most owners would go through the annoying process of claiming on the warranty for a low cost product after three years.
As regards the other non-warranty issues then that is another topic!
I had one that started beeping with a battery issue last week. I just chucked it and replaced it. I can't even remember where I bought the original from, let alone have any warranty info or a receipt.
Surely there must be some form of redress against the supplier as well.
SPRP were a little racily rated a while ago but they have a good innovative product, cash on the balance sheet and many markets to exploit. I've actually bought more this morning.
Surely there must be some form of redress against the supplier as well.
This will depend. If it is a custom part and the supplier can prove that Sprue were using the battery outside of its design specification (entirely possible) they would have no chance of any claim. There are various reasons for the reduced life of a battery and most of them are not related directly to its manufacture.
SPRP were a little racily rated a while ago but they have a good innovative product, cash on the balance sheet and many markets to exploit. I've actually bought more this morning.
Surely the point is that even at the reduced share price, they are still looking very racy until 2018 at the earliest and there's got be better opportunities in the meantime? Especially since SPRP looks like it would be pretty badly affected by Brexit given it's major overseas market is Europe. Given the recent news flow from the company I would also have to question whether the management are on top of things here. Management credibility is a very important aspect for me and so I wouldn't touch this until it was very, very cheap.
All the best, Si
Ha - is that a freudian slip - "illegal tax driver"
Hi Paul
Thanks for the write-up of Sprue Aegis (LON:SPRP) and I sold out for a loss this am, luckily this was the second smallest holding in my p/folio. As you mentioned the profit guidance for 2016 is very worrying. PBT estimates have fallen by 75% in the space of a month, as they reiterated PBT guidance £8m when they communicated the FX issues. This suggests earning visibility is very low, as things have dramatically changed to revenue and PBT forecasts for 2016 in the space of 5-6 weeks.
The other element in the RNS is product certification delays in Germany. Part of the investment thesis in Sprue Aegis (LON:SPRP) is predicated on them being able to sell products into other countries. The fact they've not been able to quantify the length of the delay (although they may well cover this in next weeks results) was also a concern.
Best wishes,
Imran.
If I recall correctly, Sprue sells several "sealed for life" products with a lifetime approaching 10 years, which is the recommended maximum life of most of the sensors. They're not rechargeable and the batteries cannot be replaced. If the problem refers to these, very early failure will cost them credibility. My research did indicate some buyers had experienced this but I wasn't able to get a feel for how often it occurs.
I sold this morning but will keep an eye on Sprue. Their products are fairly innovative and quite good quality. I have a couple of their smoke alarms at home - I avoided the sealed for life products though.
>>Sprue sells several "sealed for life" products with a lifetime approaching 10 years,
Seems likely, as an aside I recently bought smoke detectors and was going to buy sealed for life units (don't know if from this company), but decided against on reading reviews that they lasted much less than the advertised length. It seems like a good idea to have battery power for the length of the life of the sensor, but does mean that if the battery should fail prematurely, the unit has to be replaced.
K