Small Cap Value Report (18 Aug 2016) - EMR

Good morning!
Kingfisher (LON:KGF) today reports a strong performance in the UK, and a poor performance in France;
"We have delivered another solid sales performance in Q2 driven by the UK and Poland. In the UK, the EU referendum result has created uncertainty for the economic outlook, although there has been no clear evidence of an impact on demand so far on our businesses.
In France, widespread industrial action and exceptionally wet weather created a more challenging environment, after a more encouraging Q1. We remain cautious on the short-term outlook.."
Empresaria (LON:EMR)
Share price: 98.8p (up 0.8% today)
No. shares: 49.0m
Market cap: £48.4
Interim results, 6m to 30 Jun 2016 - this diversified staffing group has put out good half year figures today. Here are the highlights (i.e. the figures that the company wants us to focus on);
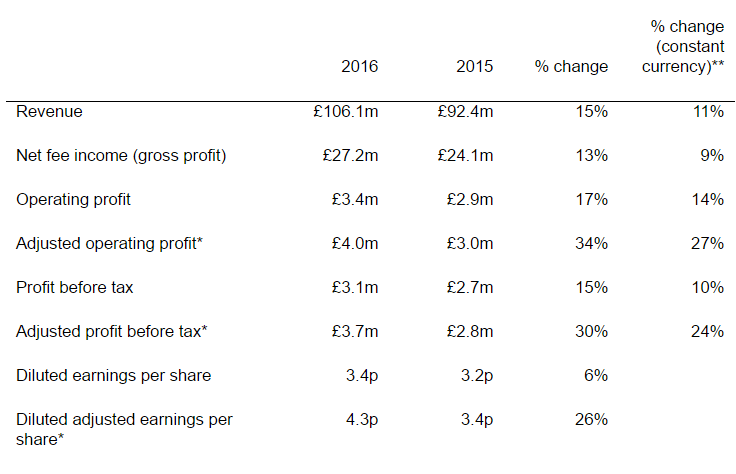
Note how the currency effect has reversed - i.e. last year most companies showed stronger growth in local currency, but that was blunted when translated into strong sterling. The opposite is now the case - so overseas earnings are now translating into a better growth percentage when expressed in now weaker sterling.
That's a recurring theme in these reports of late - the sharp deterioration in sterling after Brexit means that companies with overseas earnings are sitting pretty - as those overseas earnings are now worth more when converted into sterling.
I interviewed the CEO & FD of Empresaria recently. Here is the link. There's a lot of useful background information about the group in this audio interview. I was impressed with the company's logical, and effective strategy to diversify across different geographies & sectors.
A fairly big acquisition (£7.5m) was made just after the interim period end, which is important to remember in terms of increased debt.
Balance sheet - net assets of £38.5m reduces down to only £3.5m NTAV, once intangibles of £35.0m are disregrded.
So there's really only a sliver of equity, with the business mainly being supported by bank debt. Net debt was £10.2m at the interim period end. A figure for "average net debt" is also given, of £10.5m. I'm assuming this is the average daily net debt over the 6 months. I wish all companies would report this figure, as average net debt is a far more meaningful figure than a snapshot on one particular day (period end), which can so easily be window-dressed.
Another useful figure which is reported, is net debt as a percentage of debtors. This is very reasonable 28%. So overall, the debt position looks reasonable.
Outlook comments sound positive. The group has greatly benefited from having a wide geographical spread of activites, so has brushed aside any worries about Brexit. This has been reflected in a strong share price in recent weeks;
Empresaria has a clear multi-branded strategy, which is underpinned by investing in our existing brands, to help develop them to build long-term sustainable profit streams. Complementing this we continue to build a diversified and robust group through an Invest and Develop approach, where we evaluate external investment opportunities and strengthen our presence in sectors where we feel we are under-represented. This approach will help us develop leading brands in a group that is diversified and balanced by sector and geography.
We continue to look for suitable external investments to fill in gaps in our sector or geographic coverage with a pipeline of interesting prospects, as well as investing in our existing brands as part of their long-term growth plans. We believe in a balanced growth programme to create a business that is not dependent on one sector or geography for growth.
We see strong growth opportunities across the Group and we remain confident in our ability to deliver increasing profits.
Also, the CEO comments indicate that trading is in line with full year
expectations;...We remain confident in our ability to meet current market expectations.
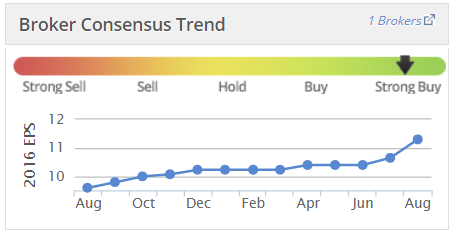
Valuation - note that broker expectations have been steadily increasing this year - obviously a good sign, of a business performing well (plus upgrades relating to acquisitions);
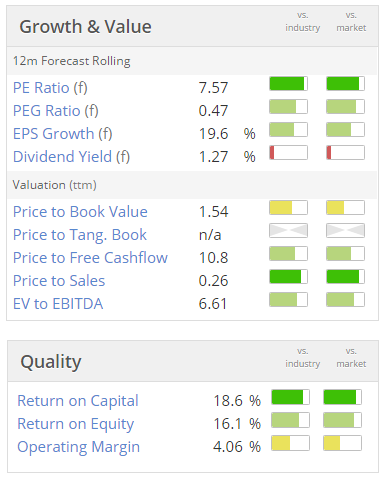
The StockRank of 97 is excellent.
Note that the PER is low, but you have to take into account the debt too. Also, the sector is quite lowly rated at the moment - investors are spoiled for choice for cheap staffing companies at the moment.
A geared balance sheet is reflected in a modest dividend yield - cash is being retained for acquisitions and repaying debt.
My opinion - I like it. This seems a well-managed, successful group, which is growing well through what appear to be sensible acquisitions. The valuation is hardly demanding.
I'm not entirely comfortable with the weakish balance sheet, but whilst debt is so cheap, I suppose it makes sense to use some degree of gearing.
Short & sweet today I'm afraid - there's nothing else of interest to me being reported today.
See you tomorrow!
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

11 comments
Ramridge, I have had a meeting with management since the results. First, the 1H:2H split is stated as one third:two thirds so 4.3p is ahead of forecasts. Secondly, I have the Arden note. They upgraded on the back of the NZ Rishworth acquisition but not on the results. They state "With H1 results tracking well ahead of,our full year forecasts and stronger FX tailwinds likely for H2, we see upside potential to our numbers if current trading conditions are maintained, and firmly believe the shares have scope to double on a two year view"
Of course the house broker is likely to say that, but the point re currency is very valid. The results RNS states that "all the major currencies we work in have strengthened against Sterling, ranging between 9% (India) and 28% ( Japan)". The currency benefit for EMR could be significant as only 30% of the business is based in the UK.
I remain a happy holder
I have been working for Kingfisher (LON:KGF) for a few months and it's my first time working in retail and for such a large company. It's quite an eye opener - in that basically such a company has to run just to stand still, has to continually innovate, grow and develop. It's a very competitive market and the likes of Homebase being taken over by an Australian outfit should bring a new dynamic to the industry. In stark contrast to a company on the top of their game is ASDA - I went into ASDA for the first time in many years a couple of weeks ago (A large ASDA is situated next the the B&Q HQ) and was shocked at how old fashioned, untidy, dim and dark, cluttered and messy it seemed. I'm not surprised that they have announced their worst quarterly sales fall today. It may stock great products at good prices but the experience of just being inside the store is awful! Going back to Kingfisher (LON:KGF), it's remarkable how correlated weather and sales are especially around key trading periods such as the May bank holidays for example. The "One Kingfisher" strategy seems to be working because it is based on clear and sensible plans to make the business more efficient.
Just a few thoughts,
Ben
simoan, johneustace -
There is a separate thread here , Thoughts on ETO, if you haven't seen it already.
Excellent analysis by Jane Bolacha.
Hi Ramridge
They say run your winners!
Personally, I am not sure I have ever got this right. Maybe this works if you distinguish between Holding type stocks, and stocks where going you intend to intend trade beyond a threshold.
Re. Empresaria (LON:EMR) There are lots of positives about this company and yet reluctantly I sold out this morning booking around 25% profit in six weeks.
Why? because an adjusted eps of 4.3p mid-way is a little short of broker expectation of 11.3p for the full year. That plus the debt burden plus a cautious outlook over the next 6 months.
I may well be leaving money on the table.
All IMHO and please DYOR
They do say that the 2nd half of the year is always stronger and that they are on track to meet market expectations. Hence I see no reason why they cannot meet 11.3p from these results
Hi Ramridge,
I like the company's strategy and the management seem to be switched on enough to execute it really well, but I agree with you to a certain extent, and so top-sliced a few this morning as there doesn't seem that much upside at the moment. The rest I will hold for the foreseeable although it's a little annoying there's no interim dividend to maintain one's interest! £EMR was a bit of a no-brainer in the low 70's post Brexit, but is much less so now, particularly as we head towards the triggering of Article 50 and whatever that will bring...
All the best, Si
BTW Ramridge, where are you looking to put the proceeds from selling £EMR? Looking down my watchlist of shares Trakm8 Holdings (LON:TRAK) is starting to look tempting at £2. Sorry for being nosey but it's a slow day at work and pretty quiet here today too :-)
All the best, Si
Hi simoan -
I have already recycled the full amount on Entertainment One (LON:ETO).
I think ETO is a sitting duck, ripe for takeover. Kind of 80% sure that it will be either KKR or some other US company with deep pockets. ITV fired the starting gun last week. The upside is in my view north of 300p which is about 20% up from today's SP.
Downside risk? Nothing comes of this and the SP slides 15% - 20%. Statistically the expected gain based on 80% probability is good enough for me, as a punt.
All IMO and please DYOR
Hi Ramridge,
Thanks, very interesting, Entertainment One (LON:ETO) is completely off my radar - I've never looked at it so will now rectify that oversight and do some research.
BTW I bought a few Trakm8 Holdings (LON:TRAK) at 201p this afternoon in hope of continued good trading, a positive AGM statement on September 7th, and the 2p dividend coming at some point. Another slight positive is that there seems to be active M&A in the telematics sector currently, so who knows?
All the best, Si
I've taken a position in Entertainment One (LON:ETO) as well. I'm working on 300p being enough to take them out, but if they can get some competition running to take it higher then happy days.