Small Cap Value Report (18 Dec 2015) - ZYT, BRY, OPM, UCG

Good morning!
It's quiet for news today, so a fairly brief report.
I recorded another CEO interview yesterday afternoon, with Mark Cambridge of Zytronic (LON:ZYT) . He is one of my favourite CEOs, being a down-to-earth manager, who tells it like it is, and doesn't expect outrageous remuneration or options schemes.
It's a super little company I think, making excellent margins with niche products, and the shares still actually look quite good value in my opinion. Zytronic has a StockRank of 95, so it's well worth a look in my view, despite the shares having recently hit new highs (disclosure: I hold a long position in ZYT).
My next CEO interview is with Brady (LON:BRY) who I'll be talking to on Monday morning, re their recent profit warning, on a "right to reply" basis, and also to hopefully clarify what has gone wrong, and why they didn't see it coming. It's really good when companies engage, and respond to criticism, or clarify areas where there might be differing perspectives, so I'm looking forward to that interview. (disclosure: I recently picked up a few shares in Brady, after they stopped falling - as usual, I couldn't resist a falling knife!)
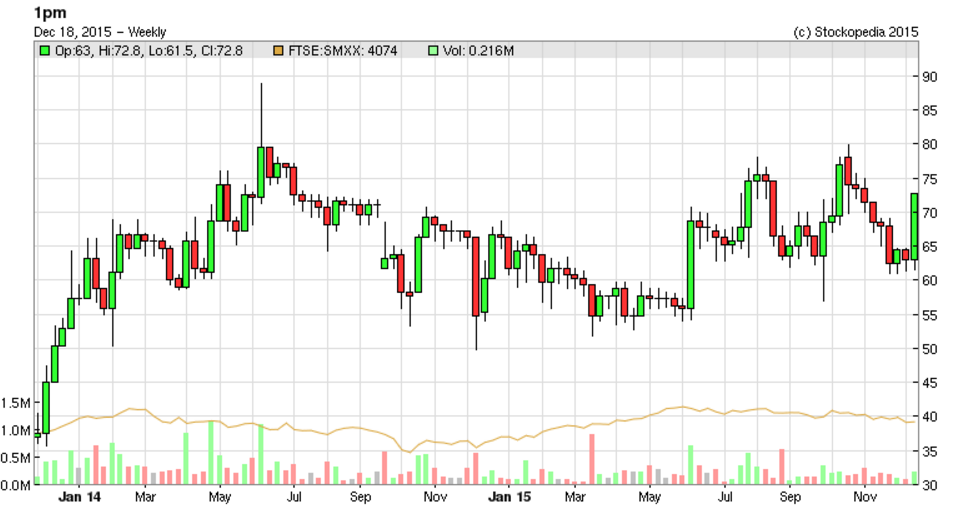
1pm (LON:OPM)
Share price: 70.5p (up 8.4% today)
No. shares: 52.5m
Market cap: £37.0m
Pre-close trading update - covering the 6 months to 30 Nov 2015. There's plenty of detail in this update, which I'll skip over, but the most important bit says;
The trading results for the half year ended 30th November 2015 will show further growth in revenue and profits compared with the corresponding period last year and are ahead of management expectations. The results include a first contribution from Academy Leasing Limited ("Academy") for the period from 25th August 2015 to 30thNovember 2015. Academy, a provider of equipment finance and an equipment and vehicles broker to the SME market, is the only trading company within the MH Holdings (UK) Limited group of companies ("MH Holdings"), which was acquired by 1pm plc on 25th August 2015 (the "Acquisition"). The trading results of Academy are also ahead of management expectations.
1PM seems to be doing very well, taking advantage of a gap in the market for asset financing for SMEs, which banks seem reluctant to return to.
My opinion - I'd want to see the interim figures before forming a view on this, and to be sure that the market cap isn't getting too far ahead of NTAV.
It's easy for financing companies to book profits in the good times, but this type of business often goes badly wrong in recessions, as a proportion of the loan book turns bad. There's also the risk that as credit conditions gradually normalise, then the big banks will probably return to financing for SMEs, thus under-cutting margins.
For the moment though, 1PM seems to be making hay whilst the sun shines.
United Carpets (LON:UCG)
Share price: 12.05p (up 2.5% today)
No. shares: 81.4m
Market cap: £9.8m
(at the time of writing, I hold a long position in this share)
Interim results to 30 Sep 2015 - this is a carpet retailer, which claims to be the UK's second-largest, after Carpetright presumably, operating from 61 stores. The company seems off the radar to investors, and it's rarely mentioned by anyone, but actually looks quite a nice little company, in my opinion.
Key points from today's interim results;
- Turnover rose 11% to £10.1m for H1
- LFL sales rose a creditable 5.0%
- Underlying operating profit rose 15% to £583k
- EPS rose 45.2% to 0.61p - note that this is a large percentage because the tax charge normalised this year, after being unusually high last year in H1.
The company seems to have an H2-weighting to trading, so full year broker forecast of 1.3p looks achievable to me.
Valuation - using 1.3p EPS forecast for this year (ending 31 Mar 2016), and a 12.05p share price, gives a reasonable PER of 9.3 - that looks good value, but bear in mind this is a small company, so it should be cheap, as it's higher risk.
Balance sheet - looks good. The business went through an insolvency process a few years ago, thus getting rid of onerous leases, etc, and cleaning up its balance sheet.
NTAV is £3.7m, and it has a healthy working capital position, including £2.1m in net cash.
Dividends - good. Note that it also paid a 1p special divi in Jun 2015 - not bad in the context of a 12p share price. I think there is scope of possibly more special divis, as the cash pile would permit this.
The normal divi yield is 3.4%, so that's not bad either.
Outlook - sounds cautiously optimistic to me. Tougher comparatives are noted.
Like for like sales since the period end remain positive against much tougher comparatives in the second half of last year and the Group appears well positioned to complete this financial year successfully. The business is transitioning from a period of retrenchment to the next phase of growth from a sustainable base. The Group has negligible borrowings, the network of stores continues to strengthen, the market is showing greater stability and there are opportunities, if carefully selected, to increase revenues be it through new stores or new marketing initiatives. Overall, the Board remains confident that the Group will continue to generate improving returns for shareholders.
My opinion - the outlook comments suggest to me that increases in profit from here are likely to be fairly modest. Overall, this share strikes me as a good value on all the main metrics that I look at - PER, divi yield, P/NTAV, etc.
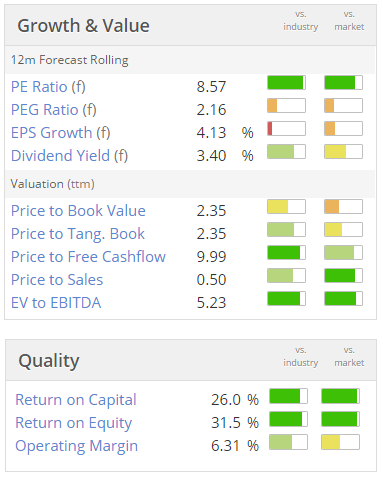
The Stockopedia computers like it lots too, with a StockRank of 99.
Note that there's plenty of green on the usual valuation & quality scores below.
I think caution is needed though, to take into account that this is a very small & illiquid share. So if something were to go wrong, you might have great difficulty selling, and it's extremely difficult to buy too. Therefore, for me, this is only a very small, long-term holding, that I've tucked away and largely forgotten about.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
Paul
Good ZYT interview. These are great insights for us private investors. It is very helpful to have access to more qualitative factors like the qualities of the CEO for these smaller companies. To add to the quants offered by Stockopedia. Keep up the good work, I'll look forward to others.
Regards
Howard
Thank you cig !
Hi Paul, carpets are pretty boring business, so we don't tend see too much coverage of them, but my they can be great little businesses! UCG always felt too small for me, but I can certainly see the appeal when you see all that green on it's Stocko metrics. Victoria Carpets turned into a wonderful little investment for me last year, but I sold out earlier this year when it started to look stretched on valuation. It just goes to show the boring stocks can often be the best.
Cheers, James
Hi all ! I note that UCG has a Stock Rank of 99 and yet it does not appear in the Top Stock Rank listing. Doug - a newcomer to StockoP
That page defaults to a 10 million minimum market cap. You can change it using the size filter on the right: if you choose Microcap you'll get UCG back.
Paul,
Thanks for a great interview with Mark Cambridge of ZYT yesterday. The answers to the patent questions were particularly illuminating. It does seem like a very well run company with good prospects and I am happy to be on board.
Your interview series is a very valuable service to private investors and performs an important function in redressing the balance in terms of advantages that institutional investors otherwise have in a difficult market so many thanks.
Goldsmithy
Hi Paul,
Excellent interview with Mark at Zytronic (LON:ZYT). Short, concise questions and plenty of meat on the answers. Mark is the ideal combination of a very technically capable manager with the ability to get his ideas across clearly and succinctly to a lay audience.
I was especially interested in his view on how ZYT position themselves into a niche as OEM suppliers rather than B2B or direct to customer complete product manufacturers. Hopefully this helps avoid the pitfall of product obsolescence and allows them to piggy back into other companies' successful product development.
Also very interested to hear how ZYT's business cycle lags that of the other equipment manufacturers, almost to the point of being counter-cyclical.
A good, well run and deservedly successful company.
Gus.
I looked at UGC , the chairman is Peter Cowgill, there is also a property dimension, I seem to recall another company Mr Cowgill was involved in ,MBL ,had a property dimension , I didn't invest although it looks good on the numbers.
Jane,
I listened to the Zytronic (LON:ZYT) interview too (I am a holder) and much of what you say is true, but I did wish the CEO was a bit more concise and that he brought out the +ve company points a little better - Maybe a sales course is required. My overall perception looking at the numbers and listening to the interview is that Zytronic (LON:ZYT) is a quality business in a growth market whose, "business YTD is ahead of 2015". Cant ask for much more! Ian
Hi,
Any chance of a look at Volvere? It announced the sale of a company it owns today - it appears to have spent less than £1m and got back £5m in just under 2 years...
Thanks
Hi FunnyMoney,
A few people have flagged up Volvere to me today, but unfortunately I just don't have time to delve into investment companies. They're special situations that require too much work, and there's only so much I have time to do, with over 500 companies in my remit already!
Sorry about that.
Regards, Paul.
Hi Paul,
I note Zytronic (LON:ZYT) is down 35p/8% in the last couple of days. I am presuming this is one of their occasional price hiccups coming off the recent highs and may well be a good opportunity to top up. I can't see any news or announcements driving this. Any views?
Thanks,
Gus.
Hi Gus,
I agree, the price move on Zytronic (LON:ZYT) seems just a normal gyration which this stock does from time to time. I think it's when people start to bank profits, then there's a stampede for the exit! As it's illiquid, the price moves on virtually every trade.
I was the buyer at 381p today that turned the price back up again! :-)
Regards, Paul.
Thanks Paul.
I suspect I'll be ticking it up too in the morning!
All the best,
Gus.
Paul, thank you, that's a very good interview with Mark Cambridge. I always try to "read into" a person's language and language expressions and reactions and intuit personality and character. In this interview I "read" openness, honesty and sincerity there. I liked the way he has a grasp of figures and detail, did not duck any questions, going into quite some detail in most of his responses. I was interested in his explanation of how Zytronic is intimately involved at the customer's unit design stage and how it's at that stage that Zytonic becomes "designed in" or embedded into the customers' products and how succeeding at that point pre-empts the competion, how that may be two years or so before revenues result from that work. The selling is effectively done at that point. That is something I had expected but the thought occurs that there is effectively a latent, invisible, unrecognised asset there, a kind of work-in-progress which I'd expect to be worth quite a bit more than the 1.4m pounds they have in intangible assets on the balance sheet. Mr Cambridge is obviously very hands-on and passionate about his company and their market (I had the impression he "lost" you in the detail a couple of times!) and I, a shameless technophobe, have listened to the interview a couple of times so as not to miss anything. It's a company I would just love to visit personally. They do seem great people (and I just love the accent!). Thank you once more, great interview.
Hi Jane,
You're a very astute lady, we're fortunate to have you here commenting. All your points are spot-on.
I also like doing interviews, to get insights into the person's character. Mark Cambridge at Zytronic (LON:ZYT) is one of my favourite hands-on managers - relatively modestly paid, no ego, passionate about the company, open & honest, easy to talk to.
Yes he did lose me a couple of times on the detail, but as the answers were quite long, there wasn't time to clarify all the points, where I wasn't sure if he was talking about ZYT or competitors. Hopefully listeners will be able to understand the technical stuff better than me! I did try to summarise on a few points, e.g. the patents, and he confirmed my summary.
It's a lot trickier to interview people than you might think, so I'm gradually learning on the job. You have to strike a balance between letting them talk, and not interrupting (as doing so makes it impossible to listen to). So I try to remain silent and let them answer fully, but then you run out of time if they give lengthy answers, as in this case!
Hopefully I got the main reader questions answered well, although there wasn't time to cover some of the more obscure questions, I wanted to stay on topic for the main points.
Above all, I hope it gave listeners a flavour for the type of person running the company, and I also learned some useful points about the business, which I found encouraging.
Brady (LON:BRY) interview on Monday should be interesting, given my highly critical comments about their profit warning, which triggered them wanting a right to reply!
Regards, Paul.
Hi,
I appreciate it is probably more of an investment company type share than a growth share but the announcement from Volvere (VLE) this morning is another example of a superb buy and sell of a Company using experienced management to add value.Worth a look !
Have a good weekend Paul.