Small Cap Value Report (18 Jun 2015) - NXR, HRN

Good morning!
When my clock/radio goes off each morning at 7am, and the iPad starts bleeping with RNSs, it's always entirely random which radio station comes on - this is because my sleepy fumbling to find the snooze button often dislodges the radio tuner. So I've gradually migrated, unintentionally, from Radio 4, through a local commercial station, to Radio 3 for a week or so, and now I think it's on Radio 2.
Anyway, Chris Evans was the chirpy voice who woke me up today. I have to say, Top Gear will never be the same without Clarkson (I can do without his two daft sidekicks though), but if anyone is going to make it work, Chris Evans will. He is annoying, but hilariously funny I think, and spontaneous, and most important of all, a fellow petrol-head.
I am angling for a job as a sidekick to Mr Evans on Top Gear, and have paraded my credentials on Twitter with a nightly competition to "Guess the Communist-era car" from pictures, although unfortunately readers have already discovered they can cheat using Google picture search. Right, onto the markets.
Norcros (LON:NXR)
Share price: 17.9p
No. shares: 597.2m
Market Cap: £106.9m
(at the time of writing, I hold a long position in this share)
Results for y/e 31 Mar 2015 - these are not the simplest of results to interpret, since there are a number of exceptional, and legacy issues. I'm mainly interested in the underlying trading performance of the business, so it's underlying diluted EPS of 2.1p which is the key figure for me. That makes the shares look strikingly cheap on a PER of 8.5. This is flat against last year on an underlying basis (and stripping out the benefit of deferred tax assets recognised last year).
It's also slightly ahead of broker expectations, according to a note from the main broker which has crossed my desk this morning. Forecast for the current year is left unchanged, at EPS of 2.0p, slightly down, so that's a PER of 9.0 for this year - still very cheap.
Balance sheet - overall this looks OK to me. The three key tests I look for are all passed;
- Net tangible assets are positive, at £25.8m.
- The current ratio is healthy, at 1.71.
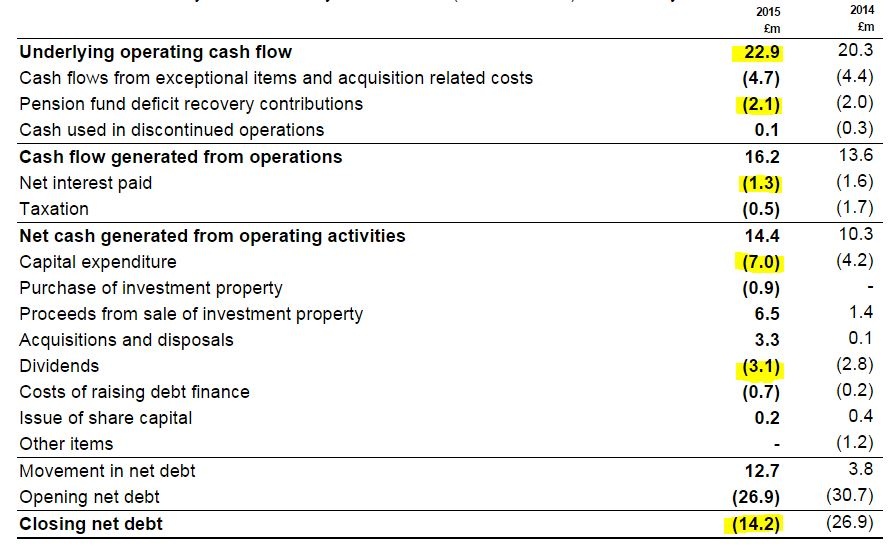
- Net debt is modest, at £14.2m (down from £26.9m, mainly due to proceeds from property disposals).
Note that the company still has significant freehold property, thus giving the balance sheet additional strength.
Pension deficit - this is the only fly in the ointment, but it's not a deal-breaker for me. The pension schemes are large, and as expected the overall deficit has risen from £21.8m last year to £44.3m this year, due to the discount rate falling from 4.3% to 3.3%.
Deficit recovery payments of £2.1m were made in the year, which looks manageable, given the company's strong cash generation.
As we saw with the amazing RNS yesterday from AGA Rangemaster (LON:AGA) saying that they had received a potential takeover approach, a big pension scheme may not be such a large impediment to a takeover bid as I feared. Certainly with US companies now on very rich ratings, I reckon we may see more bids for relatively cheap UK companies.
Dividends - the total payout has risen to 0.56p per share (up 9.8% on prior year), which equates to a yield of 3.1% - worth having, and that's about 3.75 times covered, on underlying earnings. There has been a good progression of divis since they were re-introduced in 2011.
Cashflow - this table is useful, and demonstrates the strongly cash generative nature of the business. The way I look at it, the business generates plenty of cash to finance all requirements - capex, pension deficit, divis, etc.
Outlook - the tone of the narrative seems generally positive, although outlook comments seem a bit mixed:
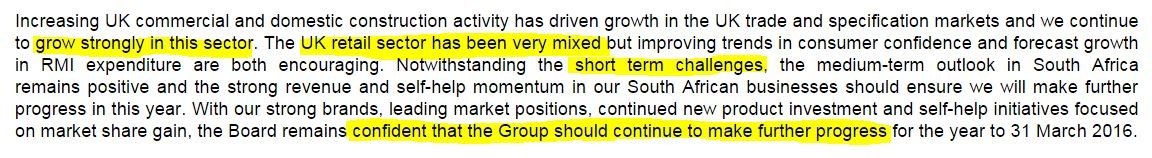
That all sounds consistent with flat broker forecasts for this year, and perhaps explains why the rating is so low - investors perhaps perceive this as a stale, no-growth company? That's actually at odds with the company's stated intention to double in size, and the comments in the "strategy" section sound a bit more exciting:
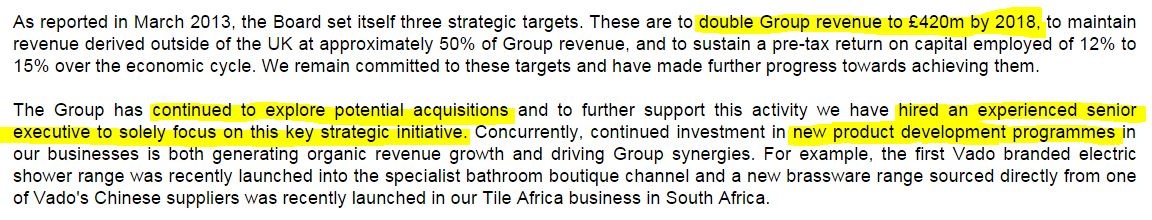
The company has plenty of firepower for acquisitions, with total bank facilities of £100m, largely unused. Norcros management have demonstrated that they can make good decisions on acquisitions, as the Vado acquisition seems to have gone well - and has offset arguably pedestrian performance from the existing businesses.
My opinion - shareholders in Norcros need the patience of a saint, as the shares have always looked cheap, and there seems to be a permanent seller in the market with an overhang of stock. Whilst this is frustrating, I continue to believe that the shares are fundamentally under-valued, and hence I continue to hold.
The divis are better than interest on money in the bank, and at some point I reckon this share could re-rate to a PER of say 12 (hardly demanding), which gives 34% potential upside on the current share price.
Although I am mindful that there is an opportunity cost to holding a share that doesn't seem to be going anywhere. Although in the past when I have sold out of boring, stagnant value shares, I've ended up bitterly regretting it (e.g. selling out of Dart (LON:DTG) at below a quid, because I'd held for about a year, and it had gone nowhere! It has since gone through the roof of course).
Norcros has performed adequately well, and fixed most of its legacy issues over the past two years, so the share price having gone nowhere overall in two years, seems unjustified to me. So hopefully my patience will eventually be rewarded here, and I have no problem continuing to hold a share that pays out over 3% in (growing) divis, and is on a single digit PER. It seems a pricing anomaly to me, but you may disagree - if so, please comment in the comments - we encourage civilised bull-bear discussions here!
I've just noticed that the Stockopedia computers like Norcros too - it has a very high StockRank of 96, which reinforces my confidence in the shares. In fact I'm finding a high convergence at the moment between my own favourite shares, and high StockRanks, which is great - it's always good when different investing approaches favour a particular share - I've found that this increases the chance of a successful outcome.
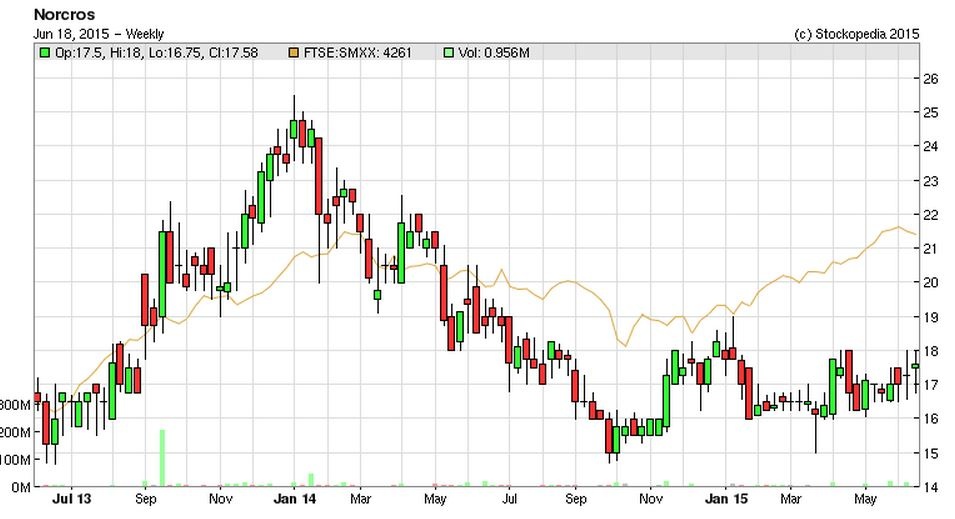
Even the chart is now starting to look positive - a "golden cross" pattern (50-day MA moving above the 200-day MA) occurred in late May 2015, and the 15-16p level has proven a strong support level for about 9 months now - which suggests to me that the seller(s) are not interested in selling below that level, and buyers move in at that level.
So risk:reward probably means there's only about 2-3p downside from the current share price, but maybe 6-7p upside (maybe more?). Therefore it's asymmetrical in a favourable way.
Hornby (LON:HRN)
Share price: 93.3p (down 5.9% today)
No. shares: 39.2m + 15.8m = 55.0m after Placing
Market Cap: £36.6m before Placing, £51.3m after Placing
Placing & move to AIM - I'm amazed that the company and its advisers have managed to get this fundraising away at 95p per share (to raise £14m after a whopping £1m in expenses), since it is abundantly clear from today's announcement that the bank have got jittery, and therefore this fundraise has I think been forced on the company, and is close to an emergency fundraise, reading between the lines.
Normally in that type of situation the share price tanks, and the placing happens at a massive discount. This one has been done at a small discount (of only 4.2%) to an already buoyant share price, so in my view shareholders should consider themselves lucky that they've been bailed out by the investors participating in the placing. This is probably because 55% of the placing shares are being taken up by existing major shareholders (New Pistoia, and Phoenix) - so they will have been keen to preserve the value of their existing shareholdings no doubt.
Today's announcement makes it clear that things could have got ugly without this deal:
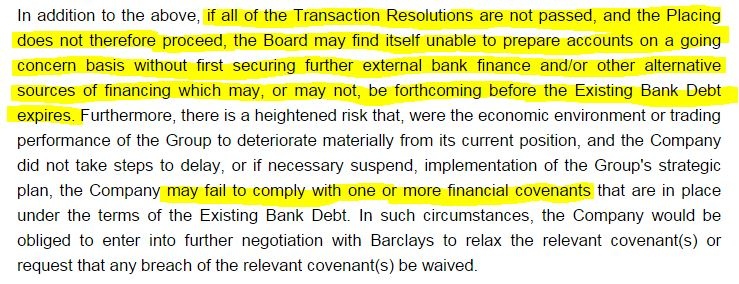
So there's no doubt the company has sailed close to the wind. The funds are mainly being used to get the bank off the hook:
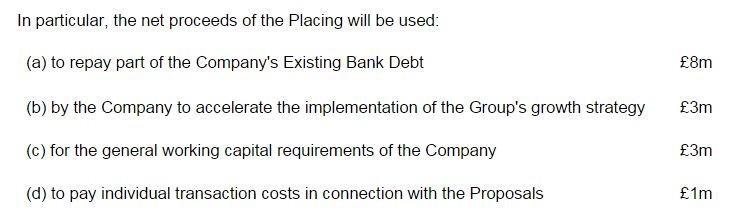
I think the move from a full listing, to AIM, makes complete sense - AIM is cheaper, less onerous, and more flexible than a full listing, and better suited to a small company like this, so this is a sensible move in my view.
Some institutions may become forced sellers, if their mandate only allows them to hold fully listed shares, but on the flipside, AIM will attract new investors to the shares, seeking IHT relief, etc.
Results for y/e 31 Mar 2015 - the company had previously announced on 1 May 2015 that it had moved back into profit, after three years of losses, so this should be seen as a turnaround situation.
Revenue was up 13% to £58.1m, and underlying profit of £1.6m is reported (up from a £1.1m loss last time).
Outlook - various details are given about ongoing turnaround actions. Current trading doesn't exactly sound brilliant, and clearly the supply chain problems are not fixed yet:
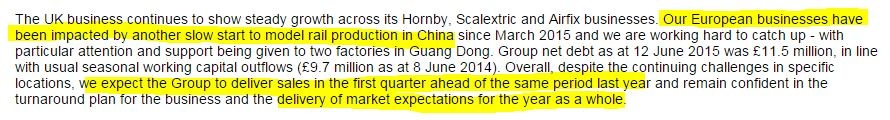
My opinion - this shows the dangers of investing in under-performing companies that have too much debt. When the bank goes jittery, the company is forced to raise fresh equity on whatever terms it can get. In this case Hornby has been very lucky to have such supportive major shareholders, who clearly believe in the turnaround plan, and are prepared to back it with substantial new funds.
It's great that Hornby has survived, and should now be financially strongish, so a nice piece of many of our childhoods (not just Hornby, but its other classic brands such as Scalextric, Airfix, and Corgi) survives into the future.
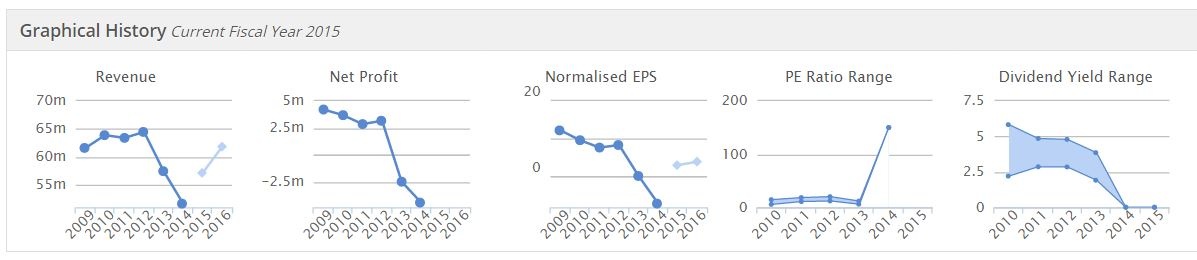
I'm not sure the shares represent value at 93p, which will now equate to a £51m market cap after the dilution from new shares. That seems an awful lot, for a company that has only just struggled to get back into the black. Although in the past, the company has been decently profitable, before they ran into seemingly catastrophic supply chain problems, as you can see from the Stockopedia graphics below. So the stock market has already priced-in a considerable further improvement in profitability.
Given where the company is at the moment, I suggest that a share price of about half the current level would represent a sensible level of risk:reward, so it's not of any interest to me.
Sorry, I ran out of time again, so recorded some brief thoughts on today's video, which covers:
MS International (LON:MSI) , Spaceandpeople (LON:SAL) , Tristel (LON:TSTL) , OMG (LON:OMG) , Plus500 (LON:PLUS) , HML Holdings (LON:HMLH) , Dillistone (LON:DSG) , £FDL
Regards, Paul.
(of the companies mentioned today, Paul has long positions in NXR, MSI, SAL, and has a short position in PLUS. A fund management company with which Paul is associated may also hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

21 comments
I see that Miton (Gervais Williams) has increased his holding in Norcros (LON:NXR) to 12%.
Hi Paul,
One more company reporting today that flies under the radar is MS International (LON:MSI). (Up 18% today at 167p)
http://www.investegate.co.uk/ms-international-plc--msi-/rns/final-results/201506180700154901Q/
They've had a bad year, as expected:
Accordingly, for the 12 months to 2nd May 2015, profit before tax was £1.54m (2014 - £2.93m) on revenue of £45.50m (2014 - £47.13m). Earnings per share were 8.20p (2014 - 14.6p).
But the interesting part is that they have had a much better second half:
I am pleased to announce that there has been a much improved performance by the Group during the second half of the year.
Their order book is improving:
The Group's current order book remains very strong. While marginally lower at year-end than that the £46m reported for 2014, it has since increased following the award of a follow-on two year contract by the UK MoD for the maintenance and support of MSI-DS 30mm naval gun systems and associated ancillary equipment in the RN fleet. Although the exact value of that contract is confidential, I can reveal that it is in excess of £12m.
And the outlook is improving:
Defence', we are predicting an improvement in the level of activity for our business in the second half of the current year, even though markets remain constrained. A very positive result from our substantial new product development programme is the winning of the first order for our new MSI-DS 20mm naval gun system....
'Forgings', should maintain a relatively stable position...
'Petrol Station Superstructures' markets continue to transform with the major oil companies leading the way in withdrawing from front line retailing by disposing of parts of their estates to independent dealers, dealer groups and operators. We perceive this to be an opportunity to expand our position in the market through providing an enhanced service to customers not only in terms of new build but also in relation to station maintenance and upgrades.
Cashflow is good:
Net cash and short term deposits increased once again to a record high of £17.15m (2014 - £14.29m) at year-end. (vs £12.5m at half year)
And the valuation is very modest with a Value rank of 92 even before today's improving results. With £17m cash at year end the EV is only £11m vs PAT £1.5m and OCF of £5m. There is a DC pension deficit of £6m but they only have to make 300k a year contribution and as you know these things are highly rate sensitive.
They are not very city friendly - I guess with £17m in cash they don't need to be - and the chairman clearly controls the company holding 29% of the shares. And one of the bug bears has been that they just sit on the cash not doing anything. To be fair they have been buying back chunks of shares if they become available but they have kept the dividend fixed at 8p for the last few years = 5.6% yield even while sitting on the cash and no special dividends.
But maybe as a sign of change today they also announced a post-period acquisition of a complimentary business:
http://www.investegate.co.uk/ms-international-plc--msi-/rns/acquisition/201506180701034903Q/
€3.4 million on a cash and debt free basis and includes "normalised" working capital. The consideration has been satisfied from the Company's existing cash resources.
Petrol Sign designs, restyles, produces and installs the complete appearance of petrol station superstructures and forecourts. The acquisition will enhance and widen the ability of the Company's 'Petrol Station Superstructure Division' to offer a more complete package of services to customers.
For the financial year ended 31st December 2014, Petrol Sign had unaudited revenues of €4,156,000 (€3,190,000:2013) and an unaudited profit before taxation of €446,000 (€196,000:2013). As at 31st December 2014, Petrol Sign had unaudited net assets of €756,000.
So 7.6xPBT for a business growing revenues 30%+ and PBT 100%+ with a 10% net margin.
Could start to look more interesting as these figures add to the bottom line combined with any improvement in the original businesses.
Cheers,
Mark (Disclosure: I hold)
Regarding MS International, I think there was an issue over very high director pay....not sure.
Richard Beddard got to grips with the issues here;
http://www.iii.co.uk/news-opinion/richard-beddard/ms-international-tests-resolve
Hi Mark,
Indeed, I bought a few MS International (LON:MSI) today - it's been on my watch list for a couple of years.
I report on it in today's video - bull and bear points.
Regards, Paul.
Hi Paul,
Thanks. I often forget that there is SCVR Extra!
Think you've probably got a good entry point as the key metrics will hopefully start to turn positive in the next few results. Although they are not very communicative so to see the hoped for re-rating you have to be willing to sit patiently waiting for a results rns every 6 months! As usual I bought my initial position too soon but at least had the balls to average down at c120p when the were trading at a discount to cash & NWC. Good to see at least one of my deep value plays coming good!
Cheers,
Mark
As always thanks for the report. I sold out of Norcros (LON:NXR) on Tuesday out of boredom and lack of movement either way and on realising the size of the pension deficit (BTW does anybody know by how much (%age wise) a pension deficit is reduced for for every 100 basis points that the yield on gilts increases?)
Am cross with myself as I have set myself a rule of holding for at least three years to control my impulses to trade because a stock does nothing. We will see if it is a mistake.
There's not going to be a simple universal formula, given the many moving parts (age distribution of claimants, conditions of the scheme like inflation indexation, sensitivity of the asset side to rate changes, spread between corporate bonds and gilts, etc). If it so wishes a pension fund can match assets and liabilities in such a way that there is no sensitivity to interest rates at all (and conversely).
Accepted but a scheme that has shown sensitivity when yields are going down (i.e. actuarial calculations have shown the scheme to be in deficit) must be sensitive to gilt yields I think?
So all other thinks being equal I would have thought that there must be a correlation between gilt yield changes and the size of the pension deficit. If not pension deficits would not increase when gilt yields fall.
Hence my question. Therefore if an increase of 100 basis points in gilt yields would wipe out the Norcros (LON:NXR) pension deficit then long term it is a non issue but if gilt yields have to rise by say 600 basis points to halve the deficit then I am glad I am out of Norcros (LON:NXR) and would avoid all companies (eg £AGA) with large pension deficits.
Make sense?
Hi Brackendale
Net debt is listed on a company's individual stock report, under the balance sheet section. So for example Hornby (LON:HRN) net debt for the year ending 2014 was £7.25m. I think the £378k you are referring to was the total of Non-current liabilities. However, most of their debt appears to be listed under current liabilities. For example according to the FY results they issued this morning net debt was around £7.5m.
Hope this helps.
Imran.
Thankyou Imran, appreciated.
RE. Norcros (LON:NXR). The overall pension deficit has more than doubled from £21.8m to £44.3m. But the company has kept the deficit recovery payment to £2.1m . This can only be sustainable if there is an expectation that interest rates, longevity rates and other assumptions move in a favourable direction. Not sure when the triennial actuarial valuation is for this company. Given that they made £8.2m net profits, the deficit reduction charges may become material if they need to rise north of £2.1m.
Great analysis, and hat off to producing this daily.
I'm wondering and it's a genuine question, if your approach, which I also use, isn't too conservative in a bull market, particularly early stage, climbing the "wall of worry"?
It definitely saves you from jumping into story stocks (ok forget tungsten, been there as well), and breaking the first two rules of investing - no 1 - don't lose money and no 2 don't forget rule 1.
looking back over the sticks you liked but didn't buy - due you feel this is a fair assessment ?
Hi SingSing,
With hindsight, yes I agree that my approach has probably been too conservative - I could have pushed the boat out a bit more, and been less paranoid about debt, and balance sheets, so I've definitely missed some good investments.
However on the other hand, I've had some big winners lately too, e.g. Avesco (LON:AVS) and Character (LON:CCT) which were screamingly cheap, but the market just missed the obvious, and gave me a great opportunity to buy before the big recent rises.
Also note that some of my dogs from last year are now recovering - which generally companies with strong balance sheets do, after a while - Spaceandpeople (LON:SAL) and Flybe (LON:FLYB) for example.
Overall, I'm being a bit more flexible on balance sheet strength now, and recently surprised myself by buying some Idox (LON:IDOX) for example!
Overall, I remain of the view that many, or even most investors are wildly cavalier with debt & balance sheet risks. This may be fine now, but when the next financial crisis happens, they'll get a very rude awakening I think. You'll find that banks behaviour becomes a lot tougher once interest rates return to normal - we're still very much in a period which is a historic aberration at the moment, but far too many people are now thinking this is the new normal. It isn't, and I think maintaining discipline on balance sheet strength will serve me well in the long run.
Regards, Paul.
Hi Paul,
Hornby. I have clearly messed this up because my impression from last annual report was that they had very little debt - £378,000 long term, having fallen rapidly over last few years. Where did I go wrong and what should I have looked for?
Thanks
Hi Paul
I also hold Norcros (LON:NXR) and agree that patience is needed as the SP has done very little. I just wanted to pick up the point you make about 'opportunity cost', as I think this is an important point. For example comparing the performance of Norcros (LON:NXR) to Topps Tiles (LON:TPT) over a two year time period, you can see that Norcros (LON:NXR) has been largely flat, whereas the return for Topps has been very strong. I did have a position in Topps, but sold out far too early. I still feel Norcros (LON:NXR) is undervalued, but there is an opportunity cost of holding a share where it does very little.
Best wishes,
Imran.
Morning Paul et al,
I was really pleased with the Norcros (LON:NXR) results this morning. (by-the-way, I usually wake up to John Humphries..)
A big plus for me is the increased dividend and the big reduction in debt. The growth strategy is indeed very bullish, they will need to make some exceptional acquisitions to double in size. Until these are announced I can't see much real share price progress.
Do you think that currently there is a shift from high growth and momentum stocks (which are overvalued) into value. Perhaps this will be a new dawn for us value investors!
I think good company management under promise and over deliver and i'm seeing examples of this at the moment in value stocks such as: Norcros (LON:NXR), Spaceandpeople (LON:SAL), Flybe (LON:FLYB) and Panmure Gordon & Co (LON:PMR)
I seem to remember value investors suffering during the tech boom of 2000 and in the years that followed did rather well as investors moved from highly speculative companies with high price-to-turnover ratios into classic value stocks. Neil Woodford under-performed during this period and subsequently went on to outperform in future years because he stuck to his principles.
Hi Paul....is there by any chance a link to the video extra......or am i blind and or ...stupid? tx
Hi Paul, any thoughts on Poundland PLND?
Many thanks.
Hi Paul
I read the results this morning with interest as a potential investor, what struck me was how reliant the flat eps performance was on the turnaround in SA, the rest of the business went back markedly in earnings.
"Underlying operating profit
Underlying operating profit increased by 5.8% to £17.0m (2014: £16.1m). Our UK businesses delivered underlying operating profit of £13.8m (2014: £14.2m), and our South African businesses generated an underlying operating profit of £3.2m (2014: £1.9m). On a constant currency basis the improvement in underlying operating profit in South African businesses was £1.6m. Group underlying operating profit margins improved to 7.6% (2014: 7.3%)"
Looking at the 2 biggest divisions , Triton first;
"UK revenue was 2.1% lower than the prior year. Despite some good progress in specification sales, trade sector revenue was 4.7% lower than prior year, driven by specific destocking in a small number of key accounts. Retail sector revenue was in line with last year, which given the contraction in the retail market in the year was testament to Triton's leading position, the strength of its consumer franchise and its reputation for quality, service and innovation."
What puzzles me about this is that they should be operating in benign construction markets and seeing resurgent consumer spending? Maybe the product is iffy?
UK Johnston Tiles also seemed accident prone in a similarily benign market:
"Manufacturing process improvements which reduced wastage over the past two years eventually necessitated a change to our body recipe to reduce the amount of recycled waste ceramic material used. This change in recipe was implemented in July, but despite significant off line testing, it resulted in significant disruption and a reduction in production output in the year. Manufacturing performance improved and returned to normal levels of efficiency in the last two months of the year which has been maintained in this financial year. This, coupled with the challenging retail conditions, resulted in a small operating loss being recorded in the year."
I'm not sure that looks a good enough turnaround story to tempt me and the South Africa currency and political risk is a bit scary too!
Paul - following yesterday's video I had a look at WGB. Whilst there is a lot to like about it - not least the 'hot sector' it's well valued. Other concerns are the debtors in relation to creditors and director pay. However, the thing that leapt out was that fact that retained earnings were negative yet they still paid a dividend. I was under the impression that company could pay dividends under these circumstances ?