Small Cap Value Report (18 Nov 2015) - UKM, ECK, SCS

Good afternoon!
I ended up writing quite a long report late yesterday evening, which is here, covering the following companies' results or trading updates;
Cdialogues (LON:CDOG)
Idox (LON:IDOX)
InternetQ (LON:INTQ)
Lavendon (LON:LVD)
Mobile Streams (LON:MOS)
Blinkx (LON:BLNX)
In future, I will endeavour to only go out on the lash at weekends, and not on school nights! So apologies again for yesterday's delayed service.
UK Mail (LON:UKM)
Share price: 327p (down 10% today)
No. shares: 54.9m
Market cap: £179.5m
Interim results to 30 Sep 2015 - I've not looked at this company before, so am not fully up to speed on it, so this is just an initial impression. These H1 figures look poor, but given the shares are only down 10% today, this must have been previously flagged to the market.
Indeed, looking at the chart, 7 Aug 2015 is the date when the share price began to tank, and sure enough there was a trading update on that day. The crux of that profit warning on 7 Aug 2015, which was a "materially below current market expectations" one, i.e. nasty, is that teething problems had been encountered with the move to a new, fully automated depot in Coventry.
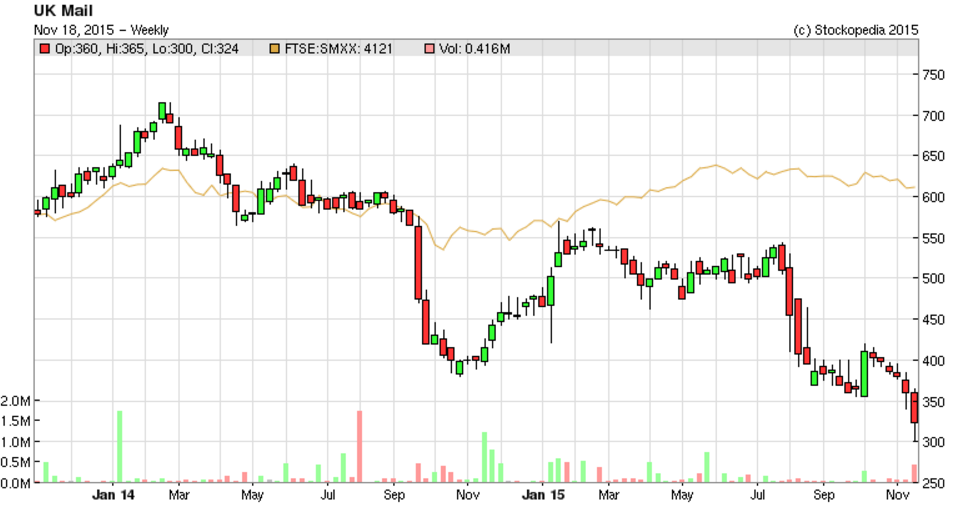
Today's interim results continue that theme, and the hit to profits is really rather bad, as the table below shows. They lost about a third of their operating profit, but due to what seem to be high central costs, this had a much larger impact on the bottom line - operational gearing working in reverse.
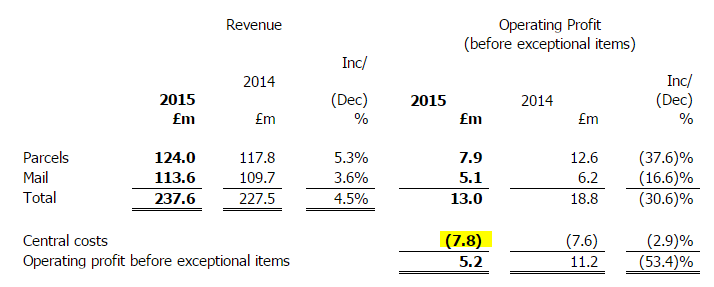
Therefore, the apparently strong operating margins mentioned in the narrative, are not really a very fair representation of performance, given that such a large lump of costs are classified as central costs.
In this type of situation, it's difficult to know how much of the drop in profits really is down to the temporary factors that management focus on, and how much is underlying deterioration in performance that will continue even after temporary problems are fixed. This is such a highly competitive sector. We say City Link go bust, and then a horrendous drop in shares on DX (Group) (LON:DX.) in recent days, after its profit warning.
This sector looks a minefield to me - combining many of the worst characteristics, which investors should avoid as much as possible - low margins, heavy capex necessary to stay competitive, lots of competition, and (with mail) falling volumes due to email substitution. Add to that, a national shortage of HGV drivers, with large pay rises being necessary to attract and retain them - as noted in DX's recent profit warning.
So really, all logistics companies look like bargepole (or even shorting opportunities), given the sector-wide difficulties. Unless the price is so bombed out, that all the bad news is in the price already (possibly the case with DX, which I bought recently, but time will tell on that).
Hence a strong balance sheet is essential in this space, as weaker players must surely end up going bust, sooner or later? Talking of which;
Balance Sheet - here are my usual 3, simple tests;
NTAV is positive? PASS - this looks alright, at £50.9m
Current Ratio over 1.2? FAIL - the current ratio is weak, at 0.81, although note that most of the bank debt is included in current liabilities, which skews the numbers. Given that long term liabilities are modest, at only £8.2m, then I can live with the current ratio being rather weak. So this test failing, is not necessarily a deal-breaker for me.
Net debt reasonable? PASS - the company does of course rely on the support of the bank, but total net debt of £12.7m is actually quite modest, for the size and profitabillity of the business overall. Although I need to check what further capex is budgeted for, as debt might continue rising perhaps? Note that a further £10.3m in compensation relating to HS2 will be received in Dec 2015, which is very material to the cash/debt position, and clearly a positive.
Dividends - given the drop in profits, the big divi yield was clearly unsustainable. Management have reduced it today, saying it is being "rebased" to 5.5p (from 7.3p last H1). That's actually quite a modest drop in the divi, but it will be interesting to see what they do with the final divi.
The narrative talks about dividend cover, rather than the absolute level of dividends, which is an important distinction, as it gives them wiggle room to cut the divi further, if earnings continue to tank;
We would expect to return to prior levels of dividend cover in due course as our earnings grow.
Outlook - rather disappointing, as expectations for 2016 are being trimmed;
As a result, our expectations for the current year remain in line with previous guidance, but our expectations for the next financial year have softened slightly.
Whilst this is disappointing, the strategic rationale for the transformation we are undertaking is as compelling as ever, and we are confident both of our ability to restore our parcels business to previous levels of profitability and to build from there. The medium term operational and financial benefits will place us amongst the most efficient and competitive operators in our market.
My opinion - this is a tricky one, as it's not a business I've looked at before. After the share price collapse at DX, I'm not inclined to go anywhere near this sector right now, it's far too high risk, since pressure on earnings is such that more profit warnings are almost certain from this sector.
Despite the share price having fallen a lot already, I this one could have further to fall. Operational problems, combined with intense competitive pricing pressure, and costs rising (especially drivers wages) make this such a difficult area, it's just best avoided (or even shorted) in my view.
As we saw with DX, a high dividend yield and low PER can be a value trap, once earnings collapse. This share is essentially a punt on whether UKM can restore previous levels of profitability. That's not a bet I want to take.
Eckoh (LON:ECK)
Share price: 47.2p (up 1.7% today)
No. shares: 223.3m
Market cap: £105.4m
Interim results - this share appears to be making the transition from being valued on fundamentals, to being valued on hopes of considerable future growth.
The figures reported today simply don't compute, to my mind, with a valuation now above £100m. Growth seems quite pedestrian, if anything, for such a highly valued stock. This is happening with quite a few fashionable growth stocks, so it's a general market thing, which could easily reverse.
H1 turnover only rose 10.3% to £8.6m, and adjusted operating profit rose 43.6% to £1.5m. It's important to note though that adjusted profit excludes share-based remuneration, which is material to the numbers. In H1 this year for example, the share-based payments charge was £343k, or just over 23% of adjusted profits. This wasn't a one-off either, as in the last full year, share-based payments (to Directors & staff presumably) was £939k, nearly 28% of adjusted profit.
Outlook - the forward-looking comments dangle some carrots about future growth in front of the eyes of investors who want to view this as a superstock, and who are happy to pay up-front for future growth;
Moving into the second half of the year, with market sentiment assisting the acquisition of new customers, and positive reactions for our new tokenisation proposition, we would expect our strong trend of growth to continue. The acquisition of PSS will enable us to grow more quickly in the US market where we remain confident that the size of the business can, in time, outstrip that of the UK and we will look carefully at the opportunity to move more meaningfully into the Australian market where PSS already has a presence.
With our high levels of recurring revenue from the existing client base, significant new business pipeline both in the UK and the US, and new opportunities to sell through PSS, we believe that Eckoh has an excellent platform on which to continue to build an exciting, fast-growing, business.
In line with our acquisition strategy, we will also continue to evaluate other acquisition opportunities where they may complement our product base or accelerate geographic expansion. As we look ahead, therefore, the Board remains very confident in Eckoh's future prospects and we continue to trade in line with market expectations for the year.
My opinion - it looks an OK business, growing modestly. This stock has been around for years, and I held shares in it a long time ago, but it just trundled along, never gaining any real tractions. It's gained a bit of traction now, but the market seems to have gone nuts over it.
I can't see how the current valuation stacks up, but maybe there is stronger growth potential in the pipeline? It's valued at a current year PER of about 34 times, and when you adjust the accounts to expense share option remuneration, you'd be looking at a considerably higher PER, well into the 40s I reckon. Does that make sense? Possibly, but it's certainly not obvious from the figures released today.
The market is starting to sell off very highly rated small caps this week, so personally I'm steering clear of opening any new positions for growth stocks, and am reviewing my portfolio to bank profits on things that have detached from reality in terms from valuation (although I rarely go into that sort of area anyway).
SCS (LON:SCS)
A very quick comment, as I have to catch a train back to Hove shortly. I'm impressed with today's trading update, which says;
"The Board is pleased to report that ScS Group continues to trade in line with expectations and has had a good start to the current financial year. Like for like order intake (including House of Fraser) has progressed as expected, and for the 16 weeks ended 14 November 2015 is up 7.9%, a pleasing performance against particularly strong comparatives during Autumn.
...We continue to look forward to the year ahead and beyond with confidence. A further update will be provided at the time of the pre-close statement which will be made in February 2016."
That's a very good LFL sales increase, which should feed through to better profits.
My opinion - I remember how quickly this stock unravelled in the financial crisis back in 2008, it went from good profits, to going bust, quite quickly. Therefore, with wafer thin profit margins today, I'm concerned that the same thing could happen again when the next recession strikes.
So it's not for me. The big divi yield on offer can obscure the reality that this is not a good quality business, in my view. That's what the market is telling you - a 9.3% dividend yield is the market telling you that this is not a sustainable payout.
In the short term though, the company appears to be trading well, so there might be further upside on the shares, for those investors who don't really think about the economic cycle.
Right, I've run out of time. See you tomorrow!
Regards, Paul.
(of the companies mentioned today, I have a long position in DX., and no short positions.
A fund management company with which I am associated may also hold positions in companies mentioned.
NB. These reports are my personal opinions only, which are subject to change without notice, and are never financial advice or recommendations. DYOR is what it's all about here!)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

31 comments
Hi Paul,
I much rather your model of journalism to that offered by some of the mainstream media.
With some of those publications, it seems they have to comment on multiple companies to meet the print deadline every week, with a corresponding drop in the quality of the analysis & comment.
In contrast, what's written here has some considerable thought put into it. The articles seem to benefit from your finance experience and the fact you're not pressured into writing cr*p to meet print deadlines.
If you want to write hardly anything on quiet days & occasionally go out on the lash and write the article late, to me that's much better than other places where people fill a page with anything to meet a deadline.
Jeff
Disclosure: Long on Boohoo...... (pus others)
Re profit warnings eg UK Mail, Rolls Royce, Tescos etc
There is a very old and incredibly accurate City saying, that would have saved me and countless others a great deal of money: "Profit warnings come in threes"
I see today that UK Mail had its second profit warning, after its first on 7th July. Recently Rolls had its second warning, Tescos is in about its third. Unfortunately this is totally normal. Management do a monthly update for the board. Realise something isn't going to plan, usually lack of sales or too much costs, often both. They wait another month to see if its an aberration. If it isn't the FD has to recut forecasts. The only problem is that the sales teams etc haven't readjusted their sights low enough and despite promising the CEO / FD they will hit the new, lower budget, they miss it again. Operational gearing works its magic and numbers are lower. After a second warning, the odds are extremely high for a third warning.
Every PM tells themselves to buy on the third warning. Trouble is that they start to lose faith- is the downturn structural not just cyclical? Can it really be fixed? There tends to be big register turnover at this point. It explains why shares can get so cheap. The danger is mistaking those companies for which the downturn is more structural rather than cyclical and avoiding them on the third warning eg Yell, HMV, UK coal,
At this point always revert to the balance sheet. How much debt has the business got ? What does the Cashflow look like? Current ratio etc. only the well financed survive deep downturns. Any doubts, do yourself a favour and sell (probably after the first warning would be best...)
So next time a warning appears out of the blue, especially in the current low nominal growth environment, be very nervous. Have expectations really been reset low enough? What happens if things get worse? Is the balance sheet solid enough?
And remember : (unfortunately) Profit warnings come in threes.
VegPatch
Excellent reminder VegPatch. I'm definitely coming around to the idea that it's better to sell first and ask questions later when it comes to profit warnings (even if you are booking a loss) as it's easy to believe that it's all just a temporary blip. Even better I think that money released like this should be recycled into companies which have just put out a profit surprise (for want of a better word) even if their share price has reacted accordingly. Better to reward a winner rather than a loser.
Damian
Re Tesco (LON:TSCO), yes 3 profit warnings but share is still above the low at first one around 164p, also the share did bounce up after each one, so you could have made a tidy profit. Some cos with profit surprises the share price has not gone up at all, see Inland Homes (LON:INL).
For sure selling on warnings and buying on surprises doesn't always work (especially in the short term) but it makes sense to me that I should increase my holdings in companies that are doing better than expected and reduce them were business is getting worse.
Sounds good in theory. Looking at the surprise earnings screen it has not performed very well though: http://www.stockopedia.com/screens/earnings-surprise-screen-31/
So would you sell Amino Technologies (LON:AMO) and Solid State (LON:SOLI), and buy Inland Homes (LON:INL) and Air Partner (LON:AIR),?
That's an interesting screen herbie47 - I haven't looked at it previously. It seems to have performed very poorly in Europe and reasonably in the UK but with some volatility. I imagine that some additional filters, such as a high StockRank, would help perhaps.
As for "So would you sell Amino Technologies (LON:AMO) and Solid State (LON:SOLI), and buy Inland Homes (LON:INL) and Air Partner (LON:AIR),? " I think that yes, broadly speaking, I would do exactly this. Obviously each profit warning is different, and in some cases they are a real one-off (such as with Dart last year), but I've been fooled too many times in the past to believe management over-optimism.
Interesting, well I do hold those 4 shares and I was considering doing the opposite. Start with Inland Homes (LON:INL), yes the profits this year look very good but they delayed the results to inc. a large land sale, but EPS forecast for next year is -59%, also debt has gone up but land bank has not increased much, bought some houses to let, not sure that is a good move, so I may take my profits soon. Air Partner (LON:AIR) I have held this share for some time but it just seems to go up and down, profits were ahead of forecast but shares did not go up, thinking of selling. Amino Technologies (LON:AMO) reading elsewhere many think this will recover, Naked Trader has bought some, Simon Thompson (Investors Chronicle) covers this, so I think I will hold. Solid State (LON:SOLI) I'm not so sure about, will have to do more research, but I did sell some at 810p. Problem with earning surprises is it a one off, many companies have a good year but then next year fall back, see Inland Homes (LON:INL), Sprue Aegis (LON:SPRP) and Renishaw (LON:RSW).
Not sure why I got a thumb's down?
Anyway Solid State (LON:SOLI) is up 7% today and Inland Homes (LON:INL) is down 4%.
ADVFN seems to attract a fair number of prophets, nutters and evangelists. If I want prophets and evangelists I can always pick up my bible or join the local happy clappy folks at the local Church. For nutters, I simply go to work at school every day. ADVFN is not for me - I wouldn't let them grind you down. I read your daily report with a good deal of interest and, like several folks above, would be happy to pay for a blog. I don't know where you find the time.
Best wishes
I guess the question is whether Paul is paid by Stockopedia for writing here. If not, then of course he can do what he likes (as opposed to doing what he likes regardless I guess).
As for his Twitter rant, I haven't seen the timing, but I'd guess fermented grapes might be a factor.
When he used to post drunken rants onTMF in the early hours, you just had to go to his sign off. It usually ended with Cheese! Lol.
I guess that even if Paul is paid for this column, it doesn't mean that "extras" such as the trip to Manchester and interview with BooHoo are funded.
Have to disagree with you on MOS Paul...
- No director buying, just major selling in 2013
- Cash flow margin over 5 years at 1.2%
- Cash flow margin at -2%
- Beneish M Score ?
SCS -- last time I looked, the management that steered the business into bankruptcy in 2008 were still in charge now.
and floated for PE to exit!! I wonder what happens next...
Hi Paul, are you doing an interview with Proactis management this week or did I imagine it? Would be very intrigued to hear about it if / when it lands. Promise I won't bug you about it like the vermin on the ADVFN boards! I guess that's why I tend to read those boards with a large pinch of salt, rather than post on them too much - your always in danger of being shot down when all your trying to do is be honest and respectful.
Seriously, thanks for reporting back your initial thoughts on the Boohoo visit - much appreciated from my persepective.
Cheers, James
UKM
Balance sheet here has £47m of freeholds as per the 2015 annual report. So some additional comfort there.
This share is the old 'Business Post' that some may remember from the 90s. Bit of a go-go growth stock in its heyday, but the profit expansion fell apart about 15 years ago. My data source says operating profits were almost £20m in 1998 -- and that figure was only just surpassed in 2004 and 2005, and 2014 and 2015. Intervening years have witnessed differing degrees of profit setbacks despite turnover almost quintupling in the same period. I guess that just goes to show how competitive this particular sector has become.
There are the remnants of a family-run firm here. Non-exec chairman Peter Kane founded the firm and he and his family continue to own at least 50% of the shares. Mr Kane turns 70 next year and I wonder if he's ever thought of calling it a day, especially as there are no younger Kanes on the board. I would have thought this business would be an obvious target for a larger rival in a sector where economies of scale and size can be important.
SCS -- last time I looked, the management that steered the business into bankruptcy in 2008 were still in charge now.
SCS. SmallCompany Sharewatch added this to their Portfolio a few months ago after making it a main reco. Then they tanked after a peculiar trading statement where they said they had had a very disappointing few weeks which they couldnt explain. Their orders have recovered since then, but Paul's comments about slim margins is very real, and not sure they can be depended upon to turn this ship round.
TMFM, I once held shares in Business Post. Lost money on them. Not interested in the slightest in the likes of DX Group or UK Mail. Even big boys struggle to make money in that business, so what hope is there for the small fry like either of these two?
As for ScS, one of the few shorts I ever made were in ScS but sold out for a small profit in the dark times of 2008ish. Didn't they warn on profits, after recently re-listing a while back?
I'd never buy their cr*p sofas, ergo would never buy their shares, esp. if what you say is true, that the previous incumbents are still running the show. It's a dog with fleas.
UKM
"There are the remnants of a family-run firm here. Non-exec chairman Peter Kane founded the firm and he and his family continue to own at least 50% of the shares. Mr Kane turns 70 next year and I wonder if he's ever thought of calling it a day, especially as there are no younger Kanes on the board. I would have thought this business would be an obvious target for a larger rival in a sector where economies of scale and size can be important. "
Here we go:
http://www.investegate.co.uk/deutsche-post-ag--0h3q-/rns/recommended-offer-for-uk-mail-group-plc/201609280700100392L/
440p per share recommended bid in cash from Deutsche Post. Up about 35% from the 327p referred to in the SCVR above.
And no, I did not buy any.
Not every Stockopedia reader will follow twitter, so for reference, here is Paul's tweet on the subject.
Never. I'm not doing a BOO report. Can't be arsed. Too many rude twats out there in bulletin board world. F**k the lot of them!
I don't know what prompted this, but I think leaving him in peace on the subject for a while would be a good strategy for anyone who wants to read a report.
Happy investing all
Jon
There are only two comments as far as I can see. Not exactly an avalanche. Paul, with respect, you created an expectation for a favorite stock of yours - and frankly, although I dont read the twitter, I hadn't realized that you were so sensitive! (Joke!) Still, I do read your comments every day I am here with great interest on all your company reviews and look forward to doing so and hope that you do feel ar**d to do so when you have the time.
Best regards
Ian
Ian,
I had a tirade of abuse on advfn's bulletin board, with people accusing me of all sorts of false motives - wanting to pump my own book, being in the pockets of management, you name it.
So in the end, I just threw my toys out of the pram & told them to F-off.
Let's just leave the subject for now please. Once I've calmed down, I may write a report. But frankly why the hell I should help people who have been so obnoxious to me elsewhere, is the question I can't quite reconcile. If there was any way to make it a subscriber only report here, then I'd be happy to write it.
Regards, Paul.
Paul, As someone who politely asked you for the Boohoo update 2 days ago -I am sorry if you feel hassled etc.
I would personally be more than happy to pay for a more detailed etc blog. No reason why you should do this all for free.
I have learnt tons from reading your daily report and really appreciate the effort.
Keep going!
Paul, why on earth are you apologising for going out on the lash and enjoying your life? You bloody enjoy yourself. Enjoy your wealth and enjoy your health. We The Unwashed will have to wait with baited breath for your posts! and bugger those nasty types on ADVFN.
Regards Nig.
Hi Paul
What about making a "Reports" section of Quality Small Caps subscriber-only? Then you can share your at-length thoughts with people who have passed some sort of quality barrier, whether that is an invitation, an application, or a payment. Just a thought.
Don't let negative feedback grind you down.
Jon
Thanks for that. Dont follow advfn's board. Understood. Still looking forward with hope. A loyal subscriber! Over and out. Ian
Paul,
Critics of you, Tom Winnifrith etc, and shorting in general are living in a state of ignorance. Many will see the light when they have lost enough money and been suckered into enough frauds. Of course, that doesn't excuse rudeness and trolling, but I should think that many will eventually see the light and come to regret their behaviour. Those that don't can get stuffed.
An army of us come here to learn and benefit from your insight every day. And I for one stay away from bulletin boards.
Thanks and regards,
Ed Miller
Re Boohoo, still waiting with avid interest your positive report on Boohoo based on your last weekend's trip, especially in the light of the not insignificant fgall off in SP today. Best regards
Ian
I may or may not write a report on Boohoo.Com (LON:BOO) - it's not helping when people keep chasing me on this.
P.
In future, I will endeavour to only go out on the lash at weekends...
Famous last words!
Hi Paul
I'd be interested in your thoughts about DX (Group) (LON:DX.) a few days since the profit warning. I noticed it bounced slightly on Monday to around the 26p/27p level, but has since fallen back to around 21p. Is this due an institutional investor selling down their stake? So far the only RNS I've seen is related to River and Mercantile so would be interested to get your thoughts.
UK Mail (LON:UKM) is an interesting stock as the chart suggests, that the stock does drop sharply on profit warnings, but there are buyers who buy the dip - not sure quite why as its still not cheap and they effectively said that the 2017 EPS forecast is not likely to be met, and would be revised downwards.
Secondly I've noticed Boohoo.Com (LON:BOO) has fallen slightly over the last couple of days. Is this due to the Black Friday and Xmas trading periods and investors feeling nervous about whether they'll be able to execute well over this period?
Best wishes,
Imran.