Small Cap Value Report (19 May 2016) - PMP, IND, RTN

Good morning.
Some absolutely superb posts in the comments section yesterday, terrific stuff! It's particularly good when readers with relevant sector experience post about companies from first hand experience as a customer or supplier.
All too often we just get our information about a listed company from that company itself. Yet this will obviously be a rose-tinted view! So these days I'm trying increasingly to search for info & views on companies from third party sources.
I've seen cases, e.g. Sprue Aegis (LON:SPRP) , where investors have picked up on poor product reviews online (hence publicly available, not insider information), and deduced that there was a serious problem. Some time later the company told the market that there was a serious problem and the shares more than halved.
Portmeirion (LON:PMP)
Share price: 1215p (down 4.1% today)
No. shares: 10.8m
Market cap: £131.2m
AGM Statement (trading update) - this is an uncharacteristically downbeat statement from this UK maker of pottery & associated products:
"Our two largest markets, the US and the UK have performed better than during the same period last year but sales to South Korea have not recovered as we had expected.
As a result total sales for the four months to the end of April were 2% below the corresponding period last year.
We have also experienced an unexpected decrease in demand from some of our other Asian markets. However, we do not believe that this is a permanent trend.
That's not good, sales overall being down - albeit not disastrously so, at 2% below last year.
I'm confused by the last section above. How do they know that weaker demand from other Asian countries is not a trend? Overall, this is a company which is reliable & trustworthy in its announcements, so I've found over the years that we can generally accept what they say at face value. This is not always the case for all small caps - I keep a mental note of which companies put out misleading announcements. Portmeirion isn't one of them thankfully.
Overall though, the company says it's on track to meet full year forecasts, so panic over:
We are taking action in response to the decrease in demand and we are confident that this, combined with our recent acquisition of Wax Lyrical, will provide overall growth for the Group this year. Consequently, we expect profit before tax to be in line with market expectations for the full year."
By "taking action" (somewhat vague) I presume the company means cutting costs, and having a sales push? If so, why not just say so?
Looking at the broker forecast graph on Stockopedia, below, it seems to me that forecasts were not increased enough to reflect the Wax Lyrical acquisition. So possibly a degree of finessing might have gone on here? So I suspect the company might have guided brokers lower on the core business, but indirectly - by getting them to under-forecast a bit for Wax Lyrical. Thereby avoiding a profit warning.
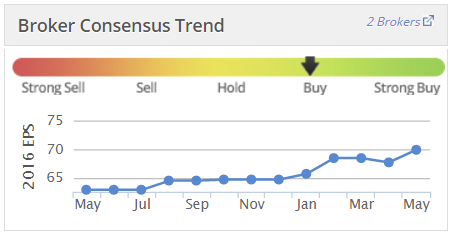
Valuation - broker consensus is only 69.9p for this year, not a big increase on last year's 65.5p. It should be noted though that last year was a particularly good year, with the company comfortably beating forecasts. So it's up against quite tough comparatives.
That drops out at a PER of 17.4 times 2016 forecast EPS.
My opinion - given the more hesitant update today, I'm less keen on this share, and think it's probably fully priced for now. So am taking it off my potential buys list for the time being, on valuation grounds. With a degree of uncertainty around its Asian markets, I feel a PER of 17.4 is looking perhaps a tad too warm now. Maybe time to take some profit? What do readers think? Comments in the comments below.
Bear in mind also that the cash pile has been used to buy Wax Lyrical, and that there is now modest net debt. So there is less balance sheet protection than there used to be. That said, the acquisition looks a sensible one - a good business, bought at a reasonable price.
Indigovision (LON:IND)
Share price: 140.5p (unchanged today)
No. shares: 7.6m
Market cap: £10.7m
(at the time of writing, I hold a long position in this share)
AGM trading update - we all know the history of this company, so I won't go over old ground again. All that matters now is interpreting today's update, and comparing it with the current valuation, to judge whether the share is worth selling, holding, or buying. So I'll work through the statement in sections:
"We indicated at the time of our annual results in March that the start to 2016 had been better than last year, although as the corresponding period was particularly subdued, this should be seen in context. This trading pattern has been broadly continued in the year to date.
To put that into context, in H1 2015, IND reported turnover of $22.6m (note that it now reports in US dollars), and a $1.3m loss before tax.
It then cut costs, and moved into profit in H2 2015, as set out in the table below (I have deduced the H2 figures by deducting H1 from FY):
| IND, $m's | H1 2015 | H2 2015 | FY 2015 |
| Revenue | 22.6 | 24.5 | 47.1 |
| Profit before tax | -1.26 | 0.51 | -0.75 |
The interesting thing is that the company's overheads are variable to a considerable extent. So the company can, and has, cut back overheads when turnover falls, thus stemming the losses. Note that in H2 last year, it actually moved back into profit, of $0.51m for the 6 months.
The company continues:
Revenues are a little behind last year, but operating performance is ahead as a result of action taken to adjust to market conditions. Efficiencies continue to be realised, cash balances are strong, and currency movements have benefited the Group in the year to date. Pricing pressure continues to be evident in the marketplace, but this has been ameliorated by higher sales volumes year on year and by product cost reductions aimed at maintaining gross margins.
"Revenues are a little behind" - so that means below the $22.6m reported in H1 last year. That represents a decline on the sequential half year ($24.5m in H2)
"Operating performance is ahead" - I would hope so! Last year's H1 was a disaster, at a loss of $1.26m. By my simple calculations, I reckon the performance for H1 2016 is heading for a small loss, of c.$0.5m. Not good, but not a disaster.
I'll summarise the other points in today's update, as follows:
Bull points
- Gross margins (51.4% last year) being maintained through product cost reductions
- Cost cutting (overheads) in 2015 has lowered the breakeven point
- Overheads are variable, so scope to cut further if required
- Cash balances strong, and balance sheet overall is good, underpinning current valuation (NAV = $23.3m at 31 Dec 2015)
- Positive impact from currency movements
- Higher sales volumes, but at lower prices
Bear points
- Revenue has fallen back again from H2 last year, and is slightly below H1 last year - a very poor half
- Competitive landscape - selling price deflation is ongoing
- Looks as if the company has moved back into (modest) losses, after a profit in H2 last year
- Little visibility on profits, as large lumpy orders skew results
My opinion - not a good update, but not a disaster either.
Given how far the share price has fallen, I'd say things are probably priced about right for now. If the company can demonstrate improved sales going forwards, then obviously there's scope for the valuation to potentially rise considerably. Although investors are tired of waiting, and have so many false dawns over the years.
I think the massive upside potential is long gone now. However, at just £10.7m market cap, with a very strong balance sheet, and relevant products, there's still plenty to play for. My view is that IND is still firmly in the game, winning decent contracts around the world - just not enough of them.
The company's sales & marketing has always been poor, and that's where its fundamental problems have come from. Things have improved on that front, and it's still a viable business, with a good set of products - note that it spent $4.4m on R&D last year, so IND is keeping pace with the sector.
It's a competitive sector though, so sales have to be hard fought for. I haven't given up hope here by any means, but I would like to see an exit through a trade sale, if a sufficient premium to the current share price was offered.
BREAKING NEWS!
Restaurant (LON:RTN)
(at the time of writing, I hold a long position in this share)
Rumoured bid approaches - Sky News & Betaville are both reporting that RTN is on the receiving end of (early stage) potential bid interest. In my view this is very credible, and hence I think this is an excellent opportunity. Although of course, these are only rumours at this stage.
I've mentioned before that, in my view RTN is a sitting duck for a takeover bid, since the valuation on a PER basis had fallen from a high level (about 20) to only about 10 when I flagged it at the UK Investor Show here as a bargain at 275p.
At the time, the PER (on lowered, most recent forecasts) was only 10, and the divi yield (twice covered) was 5%. Since then, the shares have risen 22% to 335p at the time of writing, but still look great value to me.
Sure, the company has had problems recently, but it remains highly profitable. Also it has an excellent balance sheet, with negligible debt. Freehold property is over £100m. This is the ideal situation to attract a private equity bid - since the acquisition cost can be partly funded through loading up the balance sheet with debt, selling off freeholds, etc.
I believe that the company needs new management, and a refresh of the brands & menus, at which point profit is likely to begin rising again.
Therefore I think this is a cracking opportunity at 335p. The valuation stacks up nicely even without a bid approach. With bid interest on top, risk:reward looks superb to me. So I've been buying more today. Obviously, as usual, please do your own research & make your own decisions.
The company will be forced to issue a statement imminently, to confirm or deny bid approaches. So if they say nothing is happening, then there could be 10-20% downside risk, I suppose. There again, this is such an obviously attractive situation for bidders, that I'd say it's unlikely such an announcement would be issued.
My guess is that the company is likely to confirm today or tomorrow, that it has received potential bid approaches, but that these are very early stage, and there's no certainty that any bid would be forthcoming. They might also say something about the company being undervalued, and bid approaches being optimistic. That's the type of thing companies say when management want to keep their well-paid jobs!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

38 comments
Communisis (LON:CMS) - Simon Thompson was indeed a champion of Communisis for few years, but has recently changed his recommendation (15 March 2016). He's given up - "the shares refuse to re-rate......it’s going to take some time yet to restore investors’ confidence", and the conclusion to his latest article is -
"I just can’t see a catalyst to get the share price moving near-term and feel that the shares could easily trade sideways for another six to eight months before there is firm evidence that the company is delivering.
So, having reinitiated coverage when the price at 69p ('Making the right communications', 3 Feb 2015), I am calling time on the holding and crystallising the loss. Sell."
Full article (for suscribers) -
http://www.investorschronicle.co.uk/2016/03/15/comment/simon-thompson/patience-running-short-at-communisis-8eJC1mgffl7HT5jOlo4ltL/article.html
I wasn't so patient and sold more than a year ago. Presumably Thompson's followers have contributed to the recent weakness by selling over the last few months, so now might be a good time to buy if you disagree strongly with him. I don't, and Paul's comments about balance sheet weakness (SCR 12/11/15) and the business area are enough to put me off for the time being.
Great paper, thanks. I shall enjoy reading it at leisure.
Here we are discussing fairly routine, high level Source Code, rather than focussed engineering control systems, for which input and output procedures might be identified by patterns in machine code.
But, I am now out of my depth.
apad
Paul
Do you or any subscribers have a current view of Communisis? Accepting balance sheet concerns around high Intangibles and significant debt accumulated from acquisitions, fact is with rising EPS and yield over 5% with P/E of 8 last year, forecast is for continuing EPS growth and yield and P/E falling further - why is share price continuing to be under pressure? Interesting that Richard Griffiths is now largest shareholder and Slater also significant holding. Is there a likely re-rating on the horizon or am I way off the mark here?
Peter
Peter
I don't have a position in Communisis (LON:CMS) but the Altman Z-1 score raises a question. The analysis says that "Communisis Details: Market Value of Equity/Book Value of Total Liabilities = 0.45" and that this means that CMS is insolvent, but I don't follow the reasoning. Why would the market value of equity be a valid measure of the assets? The book value of CMS seems to be nearly twice the market value. Maybe someone else can explain.
I also notice that the broker forecasts are steadily declining, which I find discouraging.
I used to hold Communisis (LON:CMS) until I joined here. I think its best to read Paul's articles on CMS and then you will see some of the problems, high debt, pension deficit, mostly intangible assets I seem to remember. The company does junk mail marketing, does not sound good for the future? Also they have had a couple of surprises which have not helped. Directors pay and share options seem quite generous considering. Shares are down over 4% today, think I will watch from the sidelines. High dividend and high debt are not a good combination in my opinion.
Hi
Thanks for your comment - I did read Paul's summary when posted and accept issue with debt and intangibles but think there is much more to company than junk mail marketing. They are active in print as traditional communication but also digital, web, mobile and social media channels and with major clients such as Barclays, Lloyds, Axa, Procter & Gamble, Centrica, EE, RBS, Legal & General - most on 3-5 year contracts with options to extend - there seems to be a strong pipeline of assured cashflow. Communication marketing to promote brands is a permanent feature of relationship building with consumers and demand for such services is growing - the successful companies will be those who can adapt to ever changing needs of both clients and consumers. Question is whether Communisis is well positioned to succeed in this environment. Dividend yield of above 5% has grown by 10% per annum in recent years and dividend cover is circa 3 times on 2015 figures. Debt reduction is recognised as a priority and continuing improvement in free cash should make positive impact in this area. Will have to wait and see if optimism of board in their outlook can be reflected in earnings and share price.
Thanks some fair points. I don't know if you read Investors Chronicle, if you do you will find Communisis (LON:CMS) was cover by Simon Thompson, not sure if he still has it as a buy tip as I'm no longer a subscriber. If they want to reduce debt then why not reduce the dividend?
Hi
Will check the IC article - reference dividend, fair point presume might be partly that having stated 'commitment' to progressive increase in dividends, reluctant to back track but presumably also comfortable that debt level will continue to be managed in terms of interest and repayment. Understanding that much of debt is direct result of acquisitions, clearly then a need for Board to demonstrate that such investment can be justified and offset with additional profit accruing from acquired business units.
I held PMP from 759P about 3 years ago as a sound investment with excellent brands.
However I was not happy about the Wax Lyrical acquisition as my gift company sold scented candles (not WL) but we got the feeling that they were no longer a growing market and could be a fashion thing rather than a solid long term item.
So I sold my holding a week or so ago , only to see the share rise further , but with the Asian demand not recovering I feel more relaxed aboyt selling.
It seems to me that they will do well to equal the 60P per share they earned last year and on that basis I would not be going back in much above 900p which would be 15X earnings.
I will probably not be able to buy at that level in the coming months, but differing views make a market.
Very good points, kalkanite.
It would be astonishing if management really don't know which chains are doing well and which ones are not.
Disclosure: I hold shares in RTN
I have picked up some shares in RTN today as the rumours do appear to have credibility and should also be a good LTBH. However, the investment is not without concerns judging by the Apr 29th conference call:
Management to carry out strategic review using external consultants! Surely no one should know the company better than current management, It's not like they are considering technological change that require external skill set? So that is a worry that management may be weak here.
Like for like revenues, management only know the overall LFL sales and not the individual restaurant chains that they own i.e. a lack of segmental figures. So how do they know which chain they should concentrate on expanding and which to run down/transfer the brand of in current outlets? Perhaps this is why the current FD has been kicked out?
Discussion over future dividends was very vague, to the point that either the CEO didn't know or was being elusive, either way not good.
Given the above I am now thinking that a completely new board is required, so hopefully it is the take over bid rumours that will 'out' the value in RTN.
The reply was meant to respond to Jones and it missed the first half, which was that it is almost impossible to do sensible research on the technology in such a rapidly moving area, subject......
:-)
"Few companies value each of their workers at £2.4m. But Arm (ARM) was happy to pay $350m (£243m) for Apical, a business with around 100 employees. The microchip designer expects the imaging and computer vision specialist to accelerate its progress in explosive markets such as robotics, smart cities and internet-connected vehicles.
Both companies license out their technology and collect royalties when customers deploy it in their devices. Apical counts Samsung, LG and Huawei among its customers. But it certainly didn’t come cheap: the deal price values it at over 14 times its turnover in the year to March 2015."
"I purchased IND without properly checking out their technology and their competitors offering. I hope not to repeat that mistake."
Hi
Well done for showing initiative. This cannot have been a trivial task for you and Id be interested in a brief summary of why the competition have a better offering. I assume you did a simple cost/benefit analysis of the various offerings etc.
subject to disruptive change. Just as difficult for the accountants who run the company as Zip comments.
It's the same issue with all the nano and graphene wet dreams.
apad
"There are three ways to ruin yourself -- gambling, women, and
technology. Gambling is the fastest. Women are the most
pleasurable. Technology is the most certain."
Georges Pompidou
"Well done for showing initiative. This cannot have been a trivial task for you and Id be interested in a brief summary of why the competition have a better offering. I assume you did a simple cost/benefit analysis of the various offerings etc."
No, it didn't happen like that. After figuring out I had made the mistake of not checking the competitors, I just sold out.
To check the competitors properly requires a lot of research and it could all be out of date if someone else makes an announcement next month.
To do the job properly is a lot of work and is best done by someone with sector expertise.
Even then, as an example, I suspect there were lots of companies with full time analysts invested in the likes of Nokia & Blackberry, until Apple & Google came along & ate their lunch, which was presumably not predicted by those analysts.
I figure my time is better spent looking for easier opportunities.
I sold out of IND several months back.
Overall, I consider my purchase to have been a mistake that was made without sufficient research.
With technology, any technical advantage might not last long, as just as soon as a better product comes along, the market share can collapse. e.g Nokia.
I purchased IND without properly checking out their technology and their competitors offering. I hope not to repeat that mistake.
Re Indigovision (LON:IND)
No understanding of technical position but have the following Sales& Marketing observations from annual report and real life experience
1. Board are all Accountants by formative background. CEO was CFO at IND before this role. NEDs are an ex-British diplomat and another Acct.
2. Only in Dec 15 did number of sales people exceed number in R&D (now 52 in 23 countries selling to 70+ ie thin and with rapid turnover)
3. Sales growth from £44 to £52Mn in 5 years. These long term results would normally get you the push somehow in a Sales role in such a big addressable market !!
The CEO needs to either
i) get in a strong NED with international Sales experience/contacts and / or
ii) look for trade sale to a better sales and distribution network
Otherwise no way back. CEO owns enough stock for it to be worthwhile for him to sell out.
"Cameras plus software are a behemoth out of America"
What can you say. Risible.
The underlying technology, both hardware and software, is translatable between Heathrow, cars, carparks, aircraft and fridges. Or whathaveyou.
If you are invested in this area, I urge you to be careful and research the bear case.
Think about what facts might make you change you mind, if there are any.
Enough from both of us I reckon.
apad
Cameras + software.
They all say it's special - it never is.
You don't need to patent algorithms - they are in machine code and nobody can read/steal them.
Unless you have technical skills don't trust your own judgement, you are so easily hoodwinked.
Cameras plus software are a behemoth out of America - don't get in the way, your phone will be doing it tomorrow.
I have seen so many research projects - they are like kids with Lego.
You have been warned.
Out.
apad
Yep I hear Heathrow are dumping their current CCTV system and replacing it with mobile phones and laptops with webcams.
apad: You can read machine code (and extract it from ROM chips if necessary - I have done it to assist a legal claim of copyright infringement between vendors of competing medical equipment.
Hi FREng,
I was aware that some specific information was extractable, but not that an efficient algorithm/coding could be extracted.
Am I incorrect?
Interesting,
I also did some research on the use of patents that are not defendable, but are useful to discourage others.
apad
apad
In most cases, you can read the whole binary, copy it, and examine it with editors, disassemblers and othet tools. Understanding the code may be a challenge, but it is achieved routinely by forensic software engineers such as those who work for anti-virus companies. The analysis of Stuxnet is a classic example, available online here: http://www.langner.com/en/wp-content/uploads/2013/11/To-kill-a-centrifuge.pdf
FREng
That's the type of thing companies say when management want to keep their well-paid jobs!
Cut the Restaurant (LON:RTN) board and there's a £3.8m pa saving to help PE make their numbers stack up.
(£128m Historic EBITDA + £3.8m management cost saving) x 7 multiple +£100m freehold - £30m net debt = £992m = £4.93/share.
I can see how a partially debt funded PE deal would make sense.
Yes I sold PMP at the outset. For a tad over 1200 (bought 950?) in Jan and had divis in there too. RNS came as a bit of a Surprise and whilst not a disaster, the price was getting rich. Glad I did as now off 10%
I must say I'm pretty skeptical about IND's technology, ok they're selling at higher margins, but if they're struggling to break even, and on a lowly valuation, wouldn't a US company for instance snap them up for their products if they were any good ?
K
Interesting observations in the comments about the pattern of slowing Asian trading. Has prompted me to review my exposure...
Totally agree with the analysis of Portmeirion (LON:PMP) While it wasn't quite a profit warning the prospect of one seems a lot more likely than yesterday. I think it still looks reasonably good value given the quality and long term growth prospects but I also think the short term risk / opportunity cost of holding it is too great so sold all my shares first thing. Sad to see it go but easy to buy back once the future is a bit clearer...
I would welcome your thoughts Paul on a point raised by someone else a couple of days ago regarding ZYT's cash position. The accounts show plenty of it yet the CEO in your interview implied that it was not available for special dividends etc?
Surely cash (or cash like investments) is either there or not?
Thanks
I think that it is very interesting that Portmeirion (LON:PMP) are only now saying that S Korea is weak, this was pointed out some time ago by Standard Chartered (LON:STAN) if memory serves, with issues about debt and the inability to pay it back.
What was more stark, for me at least was the comments from Zytronic (LON:ZYT) during Paul's interview with the CEO. He intimated that the Chinese people were being 'encouraged' to buy in house, whether that relates to domestic products too I'm not sure, but it will be interesting to see going forward - and hopefully not a trend for Portmeirion (LON:PMP) and others that do business in that neck of the woods.
Regards,
Sully.
The article is excellent.
One of my smallest holdings , in every sense , Titon Holdings (LON:TON) recently gave a weakish interim update blaming a slowdown in S.Korea for the marginall lower than expected result. So maybe that economy has had a wobble, Titon also see it bouncing back fwiw , maybe a bit of a currency translation issue as well?
http://www.investegate.co.uk/titon-holdings-plc--ton-/rns/interim-statement---6m-to-31-march-2016/201605120700079906X/
Seems Portmeirion (LON:PMP) has got its timing a bit wrong, expanding and building a new kiln last year and now cost cutting. I'm not a shareholder, if I was I would be taking some profits or even selling all with the concerns in the far east, the luxury end of the market is very vulnerable to any slow down.
IND
The world is full of able people who can put together software and a camera. Every university in the UK that I have visited (not all, but many) seems to have labs based on this premise. From a technical perspective I do not think this company has an advantage, that I can see, which will ensure its longevity.
FWIW
apad
A lot of people have little idea what this company actually do. Its not about a camera and a bit of software. I think people think IND do the same stuff as a webcam connected to the USB port on your PC. They design their own cameras, they have patented compression software and they have a whole suite of software products.
I have seen Indigovision (LON:IND) body cameras in action. Way superior to their rivals. There is even a facility to allow the camera to be turned on and start filming ten seconds ago! The problem here must be an inadequate sales team. It is no longer a case of 'build it and they will come'.
Have a look on YouTube for various demonstrations of their equipment. (I hold Indigovision (LON:IND) and have rather too many if I am honest!)
Morning Paul,
Was pleased to be able to contribute regarding the courier networks yesterday, and was very surprised how so many people found it interesting enough to give it a thumbs up, thanks!
Sadly I know nothing at all about Portmeirion (LON:PMP)... but reading your post I can't help thinking about one of my income holdings, Laura Ashley Holdings (LON:ALY). It will be interesting to see if continued struggles in Asian markets are mirrored in both companies, I suppose the businesses aren't actually too dissimilar.